










Syrma SGS raises FY27 annual revenue growth target to 40%-45%
Key highlights
- Syrma SGS raised FY27 revenue-growth guidance to 40%-45%, implying about Rs 7,000 crore of revenue.
- H1 FY27 PAT was Rs 230 crore, above the Rs 184 crore reported for full-year FY25.
- H1 FY27 export revenue was Rs 901 crore, up 80% year on year.
- Net working-capital days improved to 63 at September 2026 from 71 in the preceding quarter.
powered by IRIS
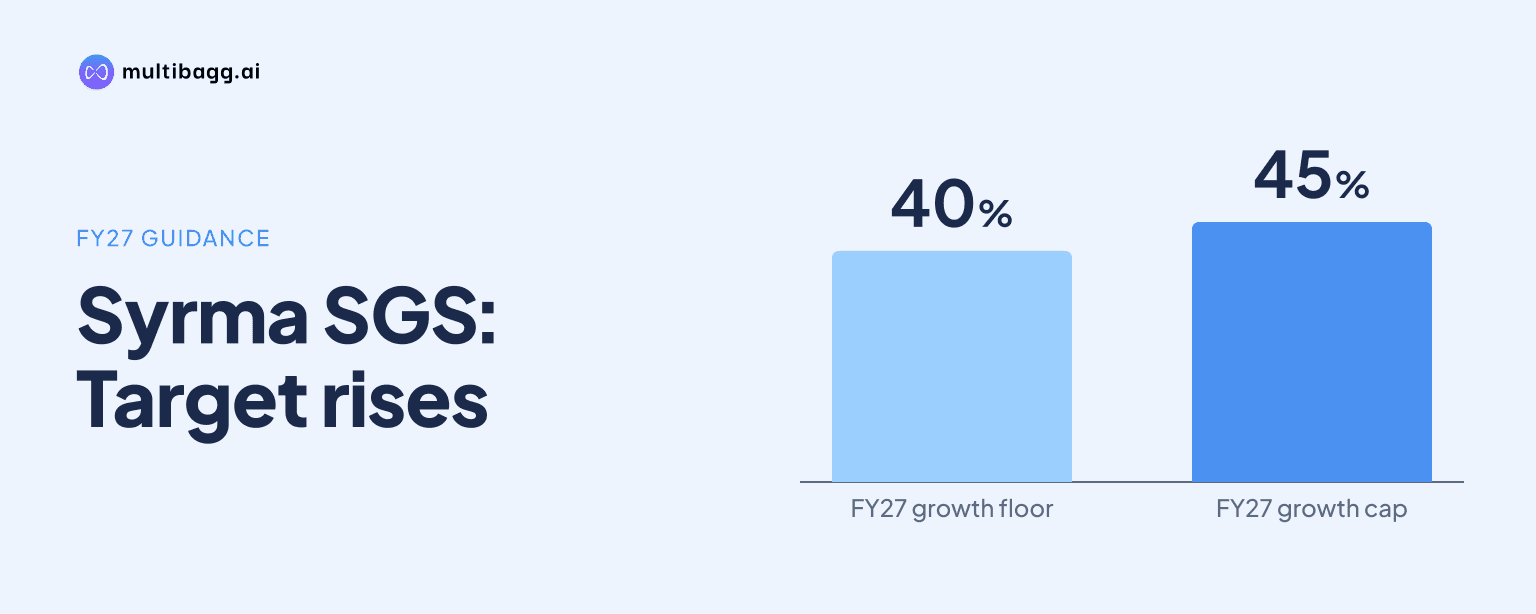
Syrma SGS Technology Limited raised FY27 revenue-growth guidance to 40%-45%, implying about Rs 7,000 crore of revenue, after H1 FY27 profit after tax reached Rs 230 crore, above FY25’s full-year Rs 184 crore. Management said the higher target reflects first-half execution but remains subject to supply-chain constraints.
Know Syrma SGS Technology inside out
Results, valuation, peers and who's buying, in one view.
Why did Syrma SGS raise its FY27 revenue growth target?
Syrma SGS raised its FY27 revenue-growth target to 40%-45%, which management said would translate to about Rs 7,000 crore of annual revenue. The revision followed H1 FY27 revenue from operations of Rs 3,578 crore, close to FY25’s full-year Rs 3,787 crore, while earnings before interest, tax, depreciation and amortisation (EBITDA), profit after tax (PAT), exports and original design manufacturing (ODM) sales exceeded their FY25 totals.
Management said the target should not be read as an annualisation of Q2 FY27 revenue of about Rs 2,000 crore, which rose 73% year on year and 25% sequentially. H1 FY27 consolidated total revenue was Rs 3,603 crore, up 71% year on year, but management said some consumer orders were front-loaded into the first half and quarterly seasonality could affect the second-half mix.
Which H1 FY27 measures exceeded Syrma SGS’s FY25 totals?
Syrma SGS’s H1 FY27 EBITDA of Rs 355 crore, PAT of Rs 230 crore, exports of Rs 901 crore and ODM revenue of Rs 591 crore each exceeded the corresponding FY25 full-year figure. Revenue from operations was the exception, at Rs 3,578 crore in H1 FY27 versus Rs 3,787 crore in FY25, leaving it Rs 209 crore short of the prior full-year total.
PAT increased 98% year on year in H1 FY27, while profit before tax rose 95% to Rs 306 crore. Profit-before-tax margin increased to 8.5% from 7.4% a year earlier, and PAT margin rose to 6.4% from 5.5%. Management attributed the bottom-line change to higher operating profit and operating leverage.
EBITDA increased 68% year on year to Rs 355 crore in H1 FY27, although EBITDA margin moved to 9.9% from 10.1% a year earlier. Management said supply-chain cost increases can be passed through to customers, but the company does not receive additional value addition on that higher cost base. That mechanism can reduce the margin percentage while absolute EBITDA rises.
What segments are driving Syrma SGS’s growth?
Syrma SGS reported Q2 FY27 growth across automotive, industrial, healthcare, consumer, information technology and railways. Automotive revenue rose 91% year on year and represented about 26% of operating revenue, while consumer contributed about 29%. Industrial revenue grew 86% year on year and 31% sequentially, and management expects that segment to grow faster in the second half.
Healthcare revenue increased 61% year on year in Q2 FY27, while information technology and railways revenue rose 69% year on year and 82% sequentially. Information technology and railways accounted for about 14% of quarterly operating revenue. Management said healthcare maintained a stable contribution and described it as a higher-margin business.
The open order book was Rs 7,420 crore at the end of September 2026. Automotive accounted for about 30% of that order book, consumer and industrial each represented about 24.5% to 25%, healthcare accounted for 8%, and information technology and railways contributed more than 12%. These figures show disclosed order visibility by segment rather than committed revenue in a specific period.
Got a follow-up? Ask IRIS
How could ODM sales and the PCB project affect Syrma SGS?
Syrma SGS reported H1 FY27 ODM revenue of Rs 591 crore, up 117% year on year from Rs 273 crore in H1 of the previous year. Management expects FY27 ODM revenue to reach Rs 1,000 crore to Rs 1,100 crore, compared with Rs 825 crore in FY26. It said the ODM share of sales has stayed broadly unchanged because non-ODM revenue is also increasing.
Management identified healthcare, defence, power electronics, radio-frequency identification, magnetics and industrial products as ODM development areas. It said these are longer-gestation programmes and expects a larger contribution over the next two to three years. Export revenue, meanwhile, is expected to exceed Rs 1,700 crore in FY27, after Rs 901 crore in H1 FY27 and Rs 1,200 crore in FY26.
The printed circuit board (PCB) project is management’s main disclosed margin-accretive initiative. Syrma SGS spent about Rs 140 crore of its Rs 200 crore Q2 FY27 capital expenditure on the PCB project, and said more than Rs 200 crore had already been spent on it. Management expects another Rs 200 crore of PCB spending during the balance of FY27.
Management targets equipment power-on and trial production by March 2027, with commercial production targeted from April 2027. It said customer approvals and quality certifications could take three to six months, making volume production around September 2027 the expected timeline. Management expects the project to contribute to margins in FY28 and FY29 once production and customer approvals are established.
What do supply-chain constraints mean for Syrma SGS’s outlook?
Syrma SGS expects FY27 EBITDA margin of 10% to 10.5%, after reporting a 9.9% margin in H1 FY27. Management said the revenue-growth target incorporates concerns about supply availability, not demand. A customer may be unable to sell a finished product because another component is unavailable, which can in turn delay Syrma SGS’s production or sales.
Management cited industry and trade expectations that supply-chain constraints could last six to nine months and potentially stabilise or ease in the first quarter of FY28. It also said uncertainty surrounding conditions after midterm elections and in the Middle East informed its cautious guidance. These were management’s assessments of external risks rather than a forecast of market demand.
Working-capital days improved to 63 at September 2026 from 71 in the preceding quarter and 73 at September 2025. H1 FY27 net operating cash flow was about Rs 120 crore, equivalent to about 34% of EBITDA, after management said operating cash flow was negative in Q1. The company reported net cash of Rs 258 crore, treasury balances of about Rs 1,000 crore and gross debt of Rs 746 crore at September 2026.
Conclusion
The FY27 guidance upgrade is supported by H1 FY27 EBITDA, PAT, export and ODM figures that moved above their respective FY25 full-year totals. The comparison also shows a distinction between earnings and revenue: revenue from operations of Rs 3,578 crore had not yet surpassed FY25’s Rs 3,787 crore, while PAT had already reached Rs 230 crore.
The next disclosed milestones are the PCB project’s March 2027 trial-production target, April 2027 commercial-production target and expected volume production around September 2027. Investors will also watch whether supply-chain conditions ease during the first quarter of FY28, as management expects, and whether Syrma SGS remains within its stated FY27 EBITDA-margin range of 10% to 10.5%.