










Syrma SGS Technology Q2 revenue reaches Rs 1,999.5 crore
Key highlights
- Syrma SGS Technology reported record Q2 FY27 revenue of Rs 1,999.5 crore, up 73.2% year on year.
- Q2 FY27 PAT rose 87.2% to Rs 124.2 crore, while EBITDA increased 63.9% to Rs 203.1 crore.
- Q2 FY27 EBITDA margin declined 58 basis points year on year to 10.2%, while PAT margin rose 47 basis points to 6.2%.
- H1 FY27 revenue increased 70.9% to Rs 3,603.2 crore and PAT rose 97.7% to Rs 229.9 crore.
powered by IRIS
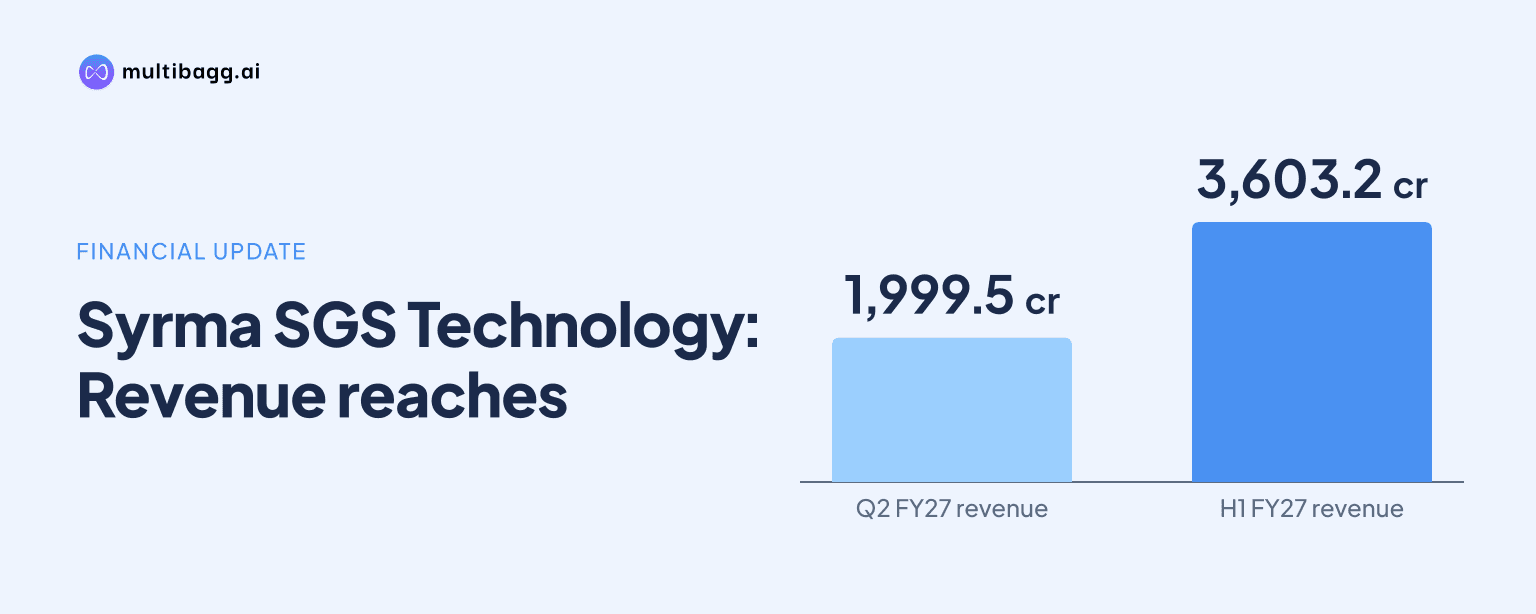
Syrma SGS Technology Limited reported its highest quarterly revenue of Rs 1,999.5 crore in Q2 FY27, up 73.2% from Rs 1,154.6 crore a year earlier. Profit after tax, or PAT, increased 87.2% to Rs 124.2 crore, while earnings before interest, tax, depreciation and amortisation, or EBITDA, margin declined 58 basis points to 10.2%.
Know Syrma SGS Technology inside out
Results, valuation, peers and who's buying, in one view.
How did Syrma SGS Technology perform in Q2 FY27?
Syrma SGS Technology recorded consolidated total revenue of Rs 1,999.5 crore for Q2 FY27, compared with Rs 1,603.7 crore in Q1 FY27 and Rs 1,154.6 crore in Q2 FY26. Revenue increased by Rs 395.8 crore sequentially and by Rs 844.9 crore year on year in the quarter ended September 30, 2026.
Syrma SGS Technology reported Q2 FY27 EBITDA of Rs 203.1 crore, against Rs 176.6 crore in Q1 FY27 and Rs 124 crore in Q2 FY26. PAT was Rs 124.2 crore, compared with Rs 105.7 crore in the preceding quarter and Rs 66.3 crore a year earlier, meaning reported PAT growth of 87.2% exceeded the 73.2% increase in revenue.
Syrma SGS Technology described the September 2026 quarter as its highest-ever quarterly performance. The reported revenue of Rs 1,999.5 crore was Rs 0.5 crore below Rs 2,000 crore, although Managing Director Jasbir Singh Gujral said in the release that quarterly total revenue had reached Rs 2,000 crore.
The release said export revenue represented 26% of operating revenue in Q2 FY27 and rose 91% year on year. It did not provide an absolute rupee value for quarterly export revenue, operating revenue, or the contribution of exports to the Rs 1,999.5 crore total-revenue figure.
Why did Syrma SGS Technology's Q2 margins differ from PAT growth?
Syrma SGS Technology reported an EBITDA margin of 10.2% in Q2 FY27, down from 10.7% in Q2 FY26 and 11.0% in Q1 FY27. The year-on-year movement was a decline of 58 basis points, with 100 basis points equal to one percentage point.
EBITDA rose by Rs 79.1 crore from Q2 FY26 to Rs 203.1 crore in Q2 FY27, but its 63.9% growth rate was below the 73.2% revenue increase. The release reports the margin movement but does not provide a detailed cost, pricing, product-mix or other reconciliation for the change.
Syrma SGS Technology's PAT margin increased to 6.2% in Q2 FY27 from 5.7% in Q2 FY26, a rise of 47 basis points. The PAT margin was nevertheless below the 6.6% reported in Q1 FY27, while PAT increased by Rs 57.9 crore year on year to Rs 124.2 crore.
The difference between the EBITDA and PAT trends is visible in the reported growth rates for Q2 FY27: EBITDA grew 63.9%, while PAT grew 87.2%. The October 30, 2026 release does not explain why PAT expanded faster than EBITDA, so the figures establish the outcome rather than its underlying drivers.
What were Syrma SGS Technology's H1 FY27 results?
Syrma SGS Technology reported consolidated revenue of Rs 3,603.2 crore in H1 FY27, up 70.9% from Rs 2,108.7 crore in H1 FY26. The first-half revenue increase was Rs 1,494.5 crore, following Q1 FY27 revenue of Rs 1,603.7 crore and Q2 FY27 revenue of Rs 1,999.5 crore.
H1 FY27 EBITDA rose 67.6% to Rs 379.8 crore from Rs 226.6 crore in H1 FY26. PAT increased 97.7% to Rs 229.9 crore from Rs 116.3 crore, a gain of Rs 113.6 crore and a faster rate of increase than the 70.9% revenue growth.
Syrma SGS Technology's H1 FY27 EBITDA margin was 10.5%, compared with 10.7% in H1 FY26, a decline of 21 basis points. Its PAT margin rose to 6.4% from 5.5%, an 87-basis-point increase, extending the distinction between the operating-margin and PAT-margin movements reported for Q2 FY27.
Export revenue accounted for 25% of operating revenue in H1 FY27 and increased 80% year on year, according to the release. Mr. Gujral said Automotive and Industrials contributed to revenue growth, while the filing did not disclose separate revenue, profit or growth figures for either segment.
Got a follow-up? Ask IRIS
What operational updates did Syrma SGS Technology disclose?
Syrma SGS Technology said it met customer commitments amid industry-wide component constraints and brought working capital back to 63 days during H1 FY27. Mr. Gujral also said operating cash flow turned strongly positive for the half year, but the release does not state the cash-flow amount or provide a prior-period working-capital-days comparison.
Syrma SGS Technology said it serves more than 270 customers across more than 20 countries. Its manufacturing footprint includes Chennai, Bengaluru, Manesar, Gurgaon, Pune and Baddi, while its research and development centres are located in Chennai, Pune, Gurgaon and Stuttgart, Germany.
The company inaugurated a new Bengaluru facility of Syrma SGS Elemaster Private Limited, its joint venture with Elemaster S.P.A. Tecnologie Elettroniche. Syrma SGS Technology said the facility expands manufacturing capabilities and supports its presence in high-growth sectors, but did not disclose investment, capacity, commissioning details or projected revenue.
Its subsidiary, Syrma Johari MedTech, inaugurated a medical plastics and precision-moulding facility in Jodhpur. Syrma SGS Technology said the facility is intended to strengthen MedTech manufacturing capabilities and support global medical-device programmes, without disclosing programme values, customers, capacity or a financial contribution.
What is Syrma SGS Technology planning next?
Syrma SGS Technology management said it plans to expand its global footprint, scale niche technology-intensive segments and advance its printed circuit board, or PCB, project as a next growth pillar. These are management plans disclosed on October 30, 2026, not revenue, margin or profit forecasts.
The company provides electronic systems design and manufacturing services, including product design, printed circuit board assembly and box-build work, quick prototyping and tester development. It also provides original equipment manufacturer solutions for radio-frequency identification tags and inlays, high-frequency magnetic components and electro-mechanicals.
The Q2 FY27 release identifies the Bengaluru joint-venture facility and the Jodhpur MedTech facility as manufacturing additions alongside the PCB project. It does not set a timeline, spending figure, output target or expected sales contribution for the PCB project or either newly inaugurated facility.
Management's reported pipeline focus follows H1 FY27 revenue of Rs 3,603.2 crore and PAT of Rs 229.9 crore. The release does not disclose orders, backlog, customer wins, capacity utilisation, or a financial outlook that would quantify the effect of its expansion plans.
Conclusion
Syrma SGS Technology delivered record quarterly revenue of Rs 1,999.5 crore in Q2 FY27 and PAT of Rs 124.2 crore, with PAT increasing faster than revenue. The reported results also show contrasting margins: EBITDA margin fell to 10.2% from 10.7% a year earlier, while PAT margin rose to 6.2% from 5.7%.
Next, readers can watch management's stated PCB project, the scaling of technology-intensive segments, and the operational development of the Bengaluru and Jodhpur facilities. The October 30, 2026 release leaves their timing, investment, capacity and financial contribution unresolved, while management also highlighted working capital of 63 days and strongly positive H1 FY27 operating cash flow without quantifying the cash flow.