










Syrma SGS Technology Limited Q2 Revenue Rises 73% to ₹2,000 Crore
Key highlights
- Syrma SGS Technology reported Q2 FY27 consolidated revenue of ₹1,999.5 crore, up 73.2% year-on-year.
- Q2 FY27 profit after tax rose 87.2% year-on-year to ₹124.2 crore.
- H1 FY27 revenue reached ₹3,603.2 crore, up 70.9% year-on-year.
- FY27 revenue-growth guidance was raised to 40%-45%, implying revenue above ₹7,000 crore.
powered by IRIS
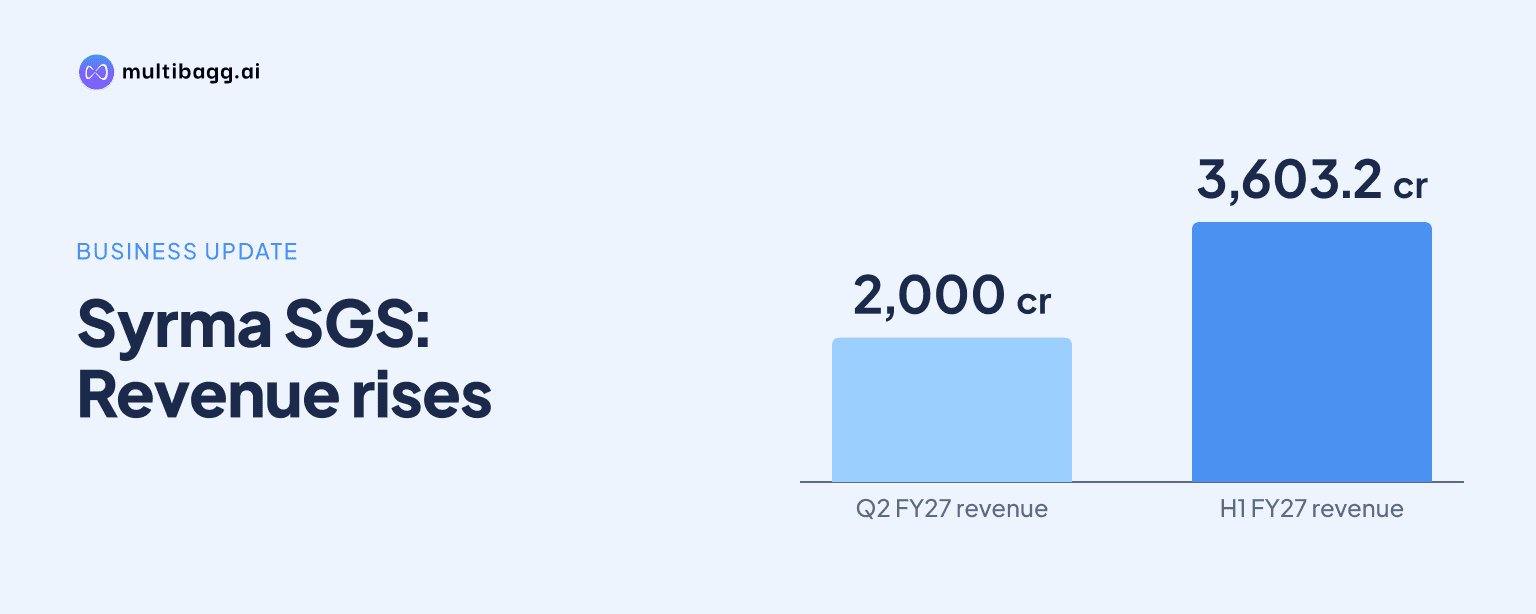
Syrma SGS Technology Limited reported consolidated Q2 FY27 revenue of ₹1,999.5 crore, up 73.2% year-on-year, while profit after tax increased 87.2% to ₹124.2 crore. The electronics manufacturing services company said the July-September quarter and first half marked record levels for revenue, EBITDA, profit before tax and profit after tax.
Know Syrma SGS Technology inside out
Results, valuation, peers and who's buying, in one view.
How did Syrma SGS Technology perform in Q2 FY27?
Syrma SGS Technology delivered strong year-on-year and sequential revenue growth in Q2 FY27, supported by broad-based demand across its reported industry segments. Consolidated total revenue was ₹1,999.5 crore, up 73.2% from the year-earlier quarter and about 25% higher sequentially. Revenue from operations stood at ₹1,989.7 crore, an increase of 73.6% year-on-year.
Profitability also increased in absolute terms. Total EBITDA rose 63.9% year-on-year to ₹203.1 crore, while profit before tax rose to ₹165.2 crore. Consolidated profit after tax reached ₹124.2 crore, compared with growth of 87.2% from the corresponding quarter of the previous year. Management described the period as its highest quarterly performance across key financial measures.
The company had declared its second-quarter results on October 30, 2026, with earnings-call materials and a presentation released on November 2, 2026. In the earnings call, Managing Director J.S. Gujral said revenue growth reflected the company's operating performance in both the quarter and the first half.
What were Syrma SGS Technology's margins and half-year numbers?
Syrma SGS Technology's earnings growth was accompanied by a modest moderation in margins. Operating EBITDA was ₹193.3 crore in Q2 FY27, up 67.7% year-on-year, but the operating EBITDA margin was 9.7%, compared with 10.1% a year earlier. Total EBITDA margin was 10.2%, versus 10.7% in the prior-year quarter.
The difference between operating EBITDA and total EBITDA reflects the metrics presented by the company in its quarterly materials. Gross margin was reported at 21.1% in Q2, lower than 24.5% in the preceding quarter. The reported figures indicate that profit growth remained ahead of revenue growth even as percentage margins softened.
For H1 FY27, total revenue rose 70.9% year-on-year to ₹3,603.2 crore. Total EBITDA increased 67.6% to ₹379.8 crore, while profit after tax nearly doubled, rising 97.7% to ₹229.9 crore. H1 operating EBITDA was ₹355 crore, with an operating EBITDA margin of 9.9%, compared with 10.1% in the previous year.
Got a follow-up? Ask IRIS
Which business segments supported the quarterly growth?
Syrma SGS Technology reported growth across automotive, industrial, consumer, healthcare, and IT and railways businesses. Automotive revenue rose 91% year-on-year and 31% sequentially, contributing 26% of total revenue in Q2. Industrial revenue increased 86% year-on-year and 31% quarter-on-quarter, accounting for 25% of quarterly revenue.
Consumer was the largest reported segment by share, contributing 29% of revenue after growing 57% year-on-year. IT and railways recorded 69% year-on-year growth and 82% sequential growth, the strongest quarter-on-quarter increase among the reported segments. Healthcare revenue increased 61% year-on-year, though its sequential performance was broadly flat.
Exports were another major contributor. Q2 export revenue increased 91% year-on-year to about ₹514 crore and represented 26% of operating revenue. H1 export revenue rose 80%, according to the company's presentation. These figures show that the quarter's expansion was not dependent on one end-market alone.
What is Syrma SGS Technology's FY27 and FY28 outlook?
Syrma SGS Technology increased its FY27 revenue-growth guidance to 40%-45%, implying revenue of more than ₹7,000 crore for the full year. The company also retained FY27 EBITDA margin guidance of 10%-10.5%. Management said it is targeting revenue above $1 billion in FY28.
For FY28, the company expects EBITDA margin to be 10.5%-11% or higher as margin-accretive projects ramp up. Its stated growth priorities include the PCB project, broader global presence and scaling technology-intensive product categories. The outlook is management guidance rather than a reported financial result.
Capacity additions continued during the period. Syrma SGS Technology inaugurated a Bengaluru facility for Syrma SGS Elemaster and a medical plastics and precision-moulding facility in Jodhpur. These projects are relevant to the company's efforts to increase manufacturing capability across specialised electronics and related segments.
How did working capital and borrowings change?
Syrma SGS Technology reported a positive H1 operating cash flow of ₹119.7 crore, compared with an operating cash outflow of ₹114.9 crore in H1 FY26. Management also said working-capital days improved to 63 days from 71 days at the end of Q1 FY27, indicating improvement during the first half.
However, inventory and borrowings increased and remain relevant financial measures for investors. Borrowings were approximately ₹746 crore, compared with about ₹353 crore at March 2026. The company identified supply constraints and working-capital discipline as considerations while pursuing its higher growth plan.
The results did not include a share-price movement or a specific market reaction. For investors, the key reported trade-off is rapid revenue and profit growth alongside lower margins than the comparable periods and a higher funding requirement for inventory and expansion.
Conclusion
Syrma SGS Technology delivered a record Q2 FY27, with consolidated revenue nearing ₹2,000 crore and profit after tax reaching ₹124.2 crore. Growth was broad-based across automotive, industrial, consumer and export businesses, while the first-half numbers showed continued momentum in revenue, EBITDA and earnings.
The next disclosures to watch are progress toward the FY27 guidance of more than ₹7,000 crore in revenue and 10%-10.5% EBITDA margin. Investors will also track whether working-capital improvement continues, how borrowings and inventory evolve, and the contribution from the PCB project and newly inaugurated facilities.