










TANFAC EBITDA margin falls to 14.4% as assets reach Rs 1,006 crore
Key highlights
- TANFAC's EBITDA margin was 14.4% in H1FY27, compared with 23.6% in FY25.
- TANFAC's total assets reached Rs 1,006 crore in H1FY27, versus Rs 426.4 crore in FY25.
- TANFAC states that Rs 400 crore of capital expenditure was completed over the past 2.5 years.
- TANFAC's net working-capital cycle increased to 104 days in H1FY27 from 91 days in FY26.
powered by IRIS
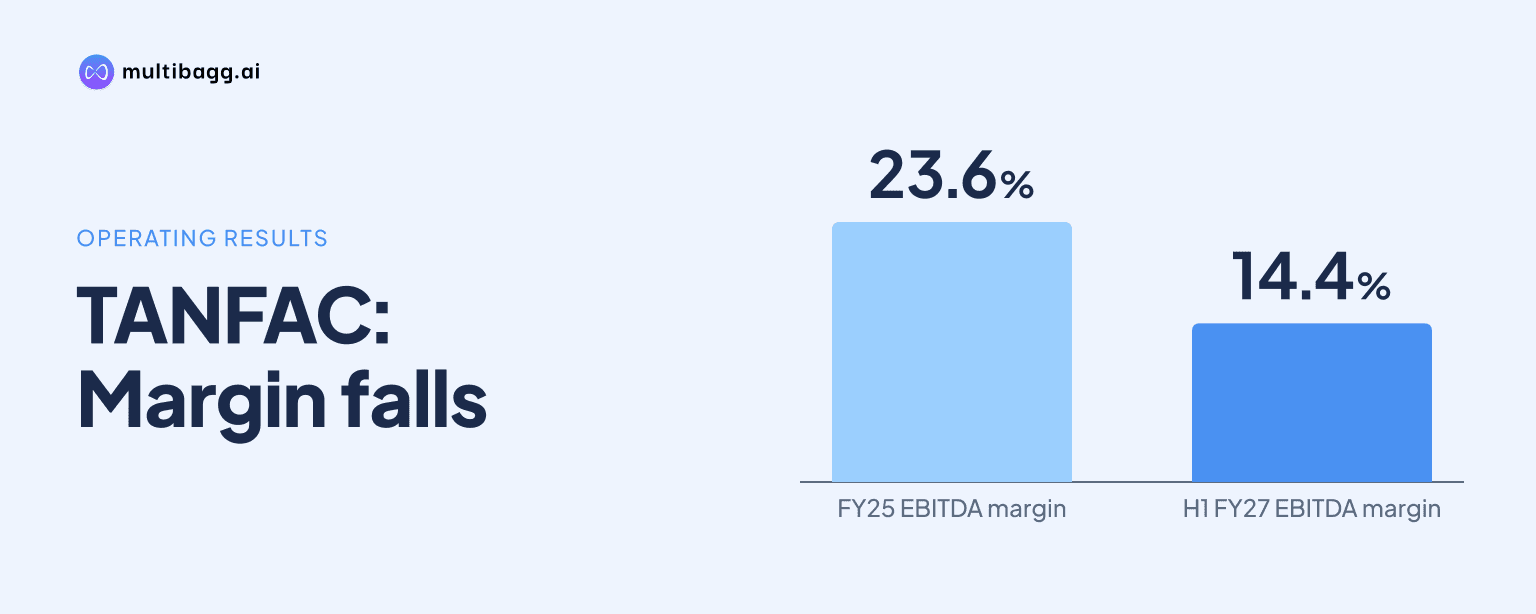
TANFAC INDUSTRIES LTD. reported an EBITDA margin of 14.4% in H1FY27, down from 23.6% in FY25, while total assets increased to Rs 1,006 crore from Rs 426.4 crore. Revenue from operations was Rs 417.7 crore in H1FY27, and the presentation states that Rs 400 crore of capital expenditure was completed over the past 2.5 years.
Know Tanfac Industries inside out
Results, valuation, peers and who's buying, in one view.
Why did TANFAC's EBITDA margin decline?
TANFAC's EBITDA margin declined to 14.4% in H1FY27 from 23.6% in FY25, while gross margin fell to 34.0% from 45.0%. EBITDA was Rs 60.6 crore on total revenue of Rs 422.4 crore in H1FY27, compared with EBITDA of Rs 132 crore on total revenue of Rs 560 crore in FY25. The presentation provides the margin and cost data but does not identify a specific reason for the decline.
The decline was already visible in FY26, when revenue from operations rose to Rs 711.1 crore from Rs 557 crore in FY25, but EBITDA decreased to Rs 114.5 crore from Rs 132 crore. EBITDA margin consequently reduced by 7.5 percentage points to 16.1% in FY26. Profit after tax also declined to Rs 70.1 crore from Rs 88.1 crore, and the profit-after-tax margin moved to 9.9% from 15.8%.
Cost of goods sold was Rs 273.9 crore in H1FY27, equal to 65.6% of total revenue, versus Rs 305.2 crore in FY25. Power and fuel cost was Rs 35.9 crore, employee cost was Rs 15.2 crore and other expenses were Rs 36.8 crore in H1FY27. Since H1FY27 is a half-year period and FY25 is a full year, the cost amounts are not directly comparable without annualisation.
How much has TANFAC's capital base increased?
TANFAC's total assets rose to Rs 1,006 crore in H1FY27 from Rs 527.7 crore in FY26 and Rs 426.4 crore in FY25. Total non-current assets reached Rs 497.7 crore, while current assets were Rs 508.3 crore. The increase coincided with Rs 400 crore of capital expenditure completed over the past 2.5 years, according to the presentation.
Property, plant and equipment stood at Rs 235.9 crore in H1FY27, up from Rs 167.8 crore in FY25 and Rs 211.7 crore in FY26. Capital work-in-progress increased more sharply, reaching Rs 153 crore from Rs 8.4 crore in FY25 and Rs 28.5 crore in FY26. Other non-current assets also rose to Rs 103.6 crore from Rs 2.1 crore in FY25.
TANFAC's fixed-asset turnover ratio was 3.5 times in H1FY27, compared with 3.4 times in FY26, 3.3 times in FY25 and 6.9 times in FY23. The ratio measures revenue relative to fixed assets. It has remained close to FY25 and FY26 levels despite the reported increase in property, plant and equipment and capital work-in-progress.
On the funding side, total equity increased to Rs 736.8 crore in H1FY27 from Rs 312 crore in FY25. Total non-current liabilities rose to Rs 76.4 crore from Rs 6.8 crore, including non-current borrowings of Rs 66.1 crore. Current borrowings were Rs 69.5 crore in H1FY27, compared with Rs 41.4 crore in FY25.
Got a follow-up? Ask IRIS
What happened to TANFAC's returns and working capital?
TANFAC reported annualised adjusted return on equity, or ROE, of 18% in H1FY27, down from 28% in FY25, while adjusted return on capital employed, or ROCE, was 19%, down from 34%. The presentation states that both measures exclude net proceeds from the qualified institutional placement and preferential issue. In FY26, adjusted ROE was 19% and adjusted ROCE was 20%.
TANFAC's net working-capital cycle increased to 104 days in H1FY27 from 91 days in FY26 and 99 days in FY25. Debtor days rose to 72 from 57 in FY26, while inventory days increased to 64 from 48. Creditor days rose to 33 from 13, partly offsetting the increase in debtor and inventory days.
The balance sheet reflects these working-capital movements. Inventories were Rs 147.3 crore at H1FY27, compared with Rs 92.8 crore at FY26, and trade receivables were Rs 165.8 crore, compared with Rs 110.5 crore. Trade payables reached Rs 75.9 crore in H1FY27, versus Rs 25.1 crore at FY26.
TANFAC reported negative net debt in H1FY27 and said this reflected its cash and cash-equivalent position. Cash and cash equivalents were Rs 99.1 crore, up from Rs 21.1 crore in FY26, while current investments were Rs 58.4 crore. Current and non-current borrowings together were Rs 135.6 crore at H1FY27.
Which projects could alter TANFAC's product mix and capacity?
TANFAC plans to commission a 20,000 metric-tonnes-per-annum, or MTPA, HFC-32 refrigerant-gas plant at Cuddalore in Q3FY27. The project carries planned investment of Rs 495 crore. Management describes it as a downstream portfolio expansion supported by in-house availability of anhydrous hydrogen fluoride, or AHF, and supply arrangements.
The presentation lists three fluorinated-product arrangements starting in January 2027. They comprise a 7,500-MTPA Japanese-customer contract valued at Rs 337.5 crore a year for seven years, a 5,000-MTPA memorandum of understanding valued at Rs 250 crore a year for five years, and an agreement valued at Rs 61 crore a year with an air-conditioning and commercial-refrigeration company. Together, these arrangements are presented as more than 12,500 MTPA and about Rs 649 crore annually.
TANFAC has also increased solar-grade diluted hydrofluoric acid, or DHF, capacity to 25,000 MTPA from 20,000 MTPA through debottlenecking. The presentation says the platform involved Rs 47 crore of investment through internal accruals. It has two long-term agreements worth Rs 1,068 crore, with orders planned for execution within 3.5 years and revenue visibility through FY29.
Conclusion
TANFAC's reported figures show that revenue expansion has coincided with lower operating margins, return ratios and a longer working-capital cycle. Revenue from operations increased from Rs 557 crore in FY25 to Rs 711.1 crore in FY26, but EBITDA margin declined from 23.6% to 16.1%, before reaching 14.4% in H1FY27. Total assets, meanwhile, rose to Rs 1,006 crore and net working-capital days reached 104.
The next disclosed milestones are the targeted Q3FY27 commissioning of the Rs 495 crore HFC-32 project and the January 2027 start dates for fluorinated-product supply arrangements. Execution of the Rs 1,068 crore solar-grade DHF agreements through FY29, along with movements in fixed-asset turnover from 3.5 times and working-capital days from 104, are the disclosed measures to watch as new capacity is deployed.