










Vijaya targets 42%-plus FY27 EBITDA margin from leverage
Key highlights
- Vijaya reported a Q2 FY27 EBITDA margin of about 44%, up 350 basis points year on year.
- Management expects Vijaya to deliver an EBITDA margin of 42% and above for full-year FY27.
- Vijaya said 65%-70% of expenses are fixed and operating leverage emerges when revenue grows above 15%-18%.
- H1 FY27 revenue grew close to 25% year on year, including about 16%-16.5% volume growth.
powered by IRIS
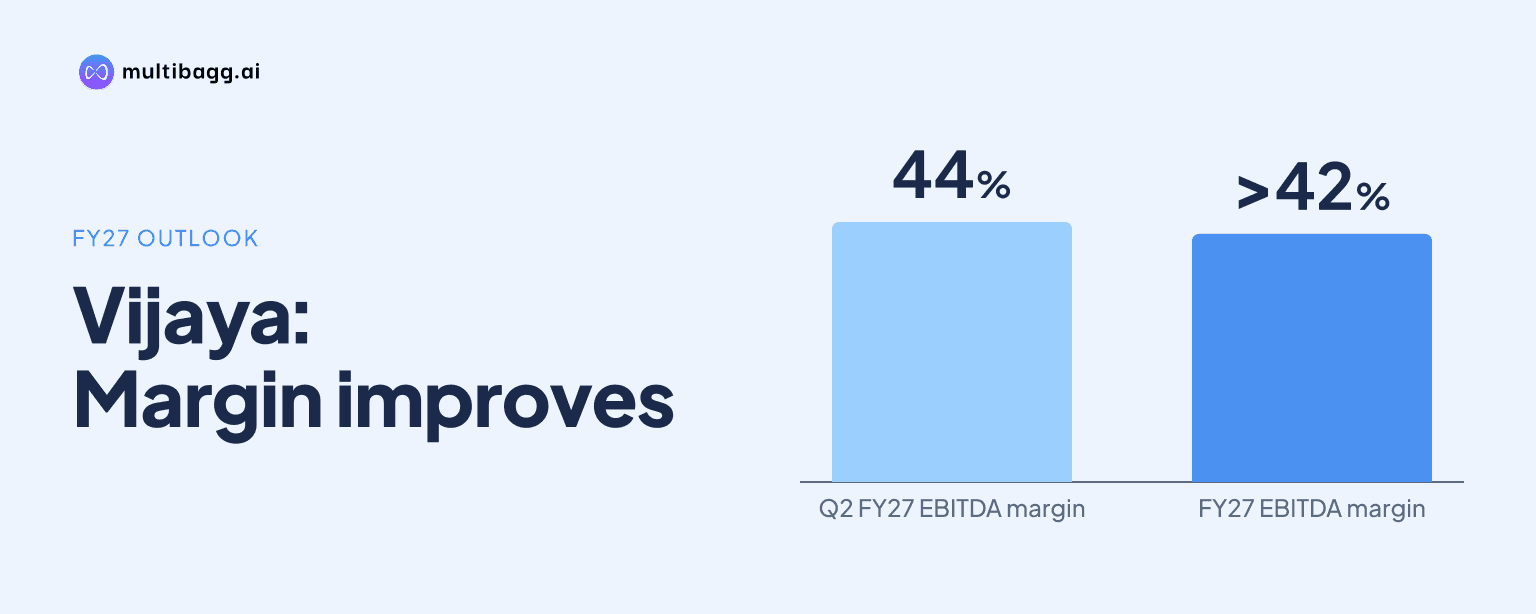
Vijaya Diagnostic Centre Limited expects an earnings before interest, tax, depreciation and amortisation (EBITDA) margin of 42% and above in FY27 after reporting about 44% in Q2 FY27, up 350 basis points year on year. Management said 65%-70% of expenses are fixed, allowing operating leverage when revenue growth exceeds 15%-18%.
Know Vijaya Diagnostic Centre inside out
Results, valuation, peers and who's buying, in one view.
Why did Vijaya's Q2 FY27 EBITDA margin rise to 44%?
Vijaya said Q2 FY27 EBITDA margin reached about 44%, a 350-basis-point expansion from Q2 of the previous year, chiefly because revenue growth exceeded the level at which its predominantly fixed cost base begins to generate operating leverage. A basis point is one-hundredth of a percentage point, so the stated improvement equals 3.5 percentage points.
Management said approximately 65%-70% of Vijaya's expenses are fixed in nature. It identified revenue growth beyond roughly 15%-18% as the threshold at which additional revenue increasingly contributes at the EBITDA level. This mechanism, rather than a stated broad reduction in operating costs, was management's primary explanation for the Q2 improvement.
The quarter also included an estimated benefit of about 2% from the Central Government Health Scheme, or CGHS, tariff increase implemented around October or November of the prior year. Management therefore attributed the 44% result to both operating leverage and the tariff effect, while presenting the fixed-cost structure as the recurring feature of its model.
Can Vijaya sustain an EBITDA margin of 42% and above in FY27?
Vijaya said it is fairly confident of achieving an EBITDA margin of 42% and above for the full FY27, based on an H1 FY27 margin of 43%-44%. The full-year target is therefore below the Q2 result of about 44%, indicating that management is not simply annualising the quarterly margin.
The company linked its confidence to revenue growth, rather than disclosing a separate cost-savings programme. H1 FY27 revenue rose close to 25% year on year, and management said at least 20% revenue growth is achievable for FY27. That reported H1 growth sits above the 15%-18% revenue-growth range that management identified as its operating-leverage threshold.
Vijaya explained that the H1 revenue increase was predominantly volume-led. Management quantified volume growth at about 16%-16.5%, estimated a 4%-5% contribution from a favourable test mix, and attributed about 3% to the CGHS tariff increase. The movement toward advanced radiology, including computed tomography, or CT, and CT angiography, contributed to the mix benefit through higher-realisation tests.
Got a follow-up? Ask IRIS
What revenue growth does Vijaya need for operating leverage?
Vijaya said growth above 15%-18% is the point at which its fixed-cost structure allows operating leverage to add to EBITDA, and management considers at least 20% FY27 revenue growth achievable. The relationship makes volume growth central to the margin outlook because management said long-term growth will be driven mainly by volumes rather than price.
For the next three to five years, Vijaya said revenue growth above 15% is a sustainable target as it expands in Pune, Kolkata and Bengaluru and adds further centres. Management said its historical compound annual growth rate in price realisation has been close to 2%, and it had not yet implemented a price rise in FY27 as of the November 4, 2026 call.
Management said it would assess market prices before deciding whether to raise prices in Q3 or Q4 FY27. That possible action was described as an additional lever, not as a component of the long-term 15%-plus revenue outlook. Vijaya instead pointed to growth from the existing network and volumes from new centres as the underlying drivers.
The network had about 168 centres, comprising 51 hubs and 117 spokes, at the time of the call. Hyderabad accounted for close to 100 centres, including 19 hubs, while the rest of Andhra Pradesh and Telangana had 33 centres, including 15 hubs. Kolkata had 12 centres, made up of seven hubs and five spokes, providing a base for the planned expansion-led volume growth.
How do new markets and test mix affect Vijaya's margins?
Vijaya said Hyderabad's revenue contribution declined to about 67% in Q2 FY27 from 69% in the corresponding previous-year quarter, while other markets increased their share. Management specifically said Kolkata had reached 5% of revenue, Pune was stable and Karnataka was growing, and it expects Hyderabad dependence to fall by roughly 3%-4% each year as other markets contribute more.
The company plans to focus on deeper expansion in Pune, Bengaluru and West Bengal rather than entering another new geography, apart from the disclosed acquisition transaction in Assam. Management said Assam would become Vijaya's seventh state and a platform for serving the northeast. This plan could add revenue capacity, but the call did not quantify its margin effect.
Within existing markets, management described equipment upgrades and added capacity as ways to support higher-realisation testing. Vijaya upgraded two CT machines to high-end 160-slice cardiac CT equipment because demand for complex CTs had increased. It also cited a high-end dual-source CT at Panjagutta and stated that CT coronary angiography and coronary calcium test volumes have grown.
In Hyderabad and other locations, Vijaya said it adds equipment when demand warrants it. Management gave the example of adding a second ultrasound machine where a spoke centre with Rs 3 crore-Rs 3.5 crore of revenue has heavy ultrasound footfall. It also said Kurnool received a second magnetic resonance imaging, or MRI, machine, while a decision on a second MRI in Tirupati could be taken within six months.
Conclusion
Vijaya's FY27 margin outlook rests on a disclosed operating model: with 65%-70% of expenses fixed, management said revenue growth above 15%-18% generates operating leverage. The 44% Q2 FY27 EBITDA margin and 43%-44% H1 range support management's expectation of 42% and above for the full year, although about 2% of the quarterly margin benefit was linked to the earlier CGHS tariff increase.
The next items to watch are whether Vijaya sustains at least 20% FY27 revenue growth, whether it introduces a price increase in Q3 or Q4, and the execution of its centre additions. Management targeted eight hubs and 14 spokes by Q1, had completed 50% of the spokes at the time of the call, and said a new Pune Market Yard hub with a central laboratory is expected to launch during FY27.