










Vinati Organics targets 15%-20% return on Rs 500 crore capex
Key highlights
- Vinati Organics plans to fund its confirmed Rs 500 crore specialty-chemicals capex entirely through internal accruals.
- Management expects the confirmed project to commercialise in two years and generate a 15%-20% ROI.
- Vinati Organics expects 65%-70% of sales from the new specialty products to come from exports.
- A separate potential Rs 500 crore project remains subject to land acquisition and pilot trials, with clarity expected within six months.
powered by IRIS
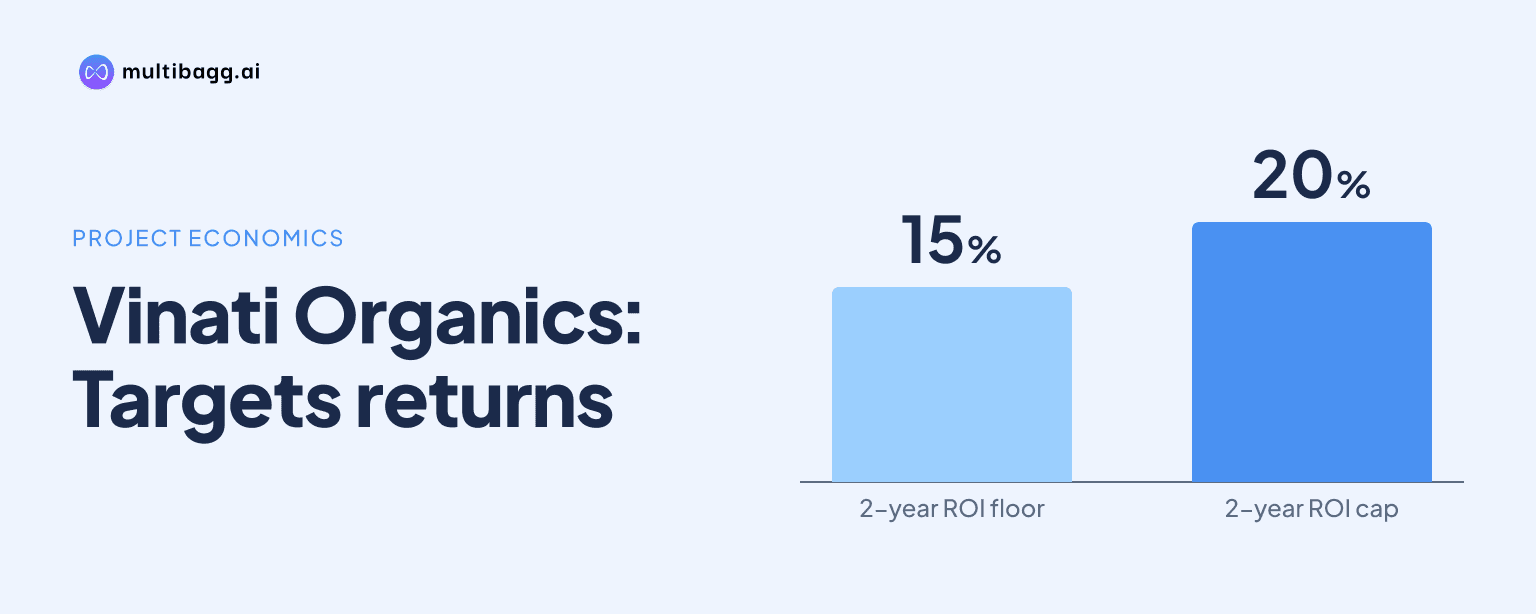
Vinati Organics Limited said on November 5, 2026 that its Rs 500 crore specialty-chemicals project, planned for commercialisation in two years, is expected by management to generate a 15%-20% return on investment, with 65%-70% of sales aimed at export markets. The project will be funded entirely through internal accruals.
Know Vinati Organics inside out
Results, valuation, peers and who's buying, in one view.
What is Vinati Organics investing Rs 500 crore in?
Vinati Organics is investing Rs 500 crore to develop and commercialise new specialty chemicals for fragrances, personal care, water-treatment solutions, oil fields, resins and other applications. Management said the project fits its long-term growth plan and could create scope for further expansion into adjacent product segments as market opportunities develop.
The products are related to Vinati Organics’ existing chemistries through backward, forward or horizontal integration, depending on the product. Managing Director Vinati Saraf Mutreja said the company had tested them for about one year before announcing the project, which management cited as the basis for moving towards commercial implementation.
The investment will create dedicated plants, rather than only extending existing lines. Management said most processes are familiar to Vinati Organics, although the facilities will involve some different technologies and processes. It shortlisted the products partly because they have end-use synergies with existing segments and can serve some current customers.
How will Vinati Organics fund and schedule the expansion?
Vinati Organics plans to fund the confirmed Rs 500 crore project entirely through internal accruals and expects commercialisation in two years. The company did not disclose a phased spending schedule, installed capacity, product-wise revenue forecast or a specific commercial-production date during the November 5 call.
Management also discussed a possible additional Rs 500 crore investment, but said it remains conditional. Vinati Organics is working on land acquisition and pilot trials for that proposal. In its opening remarks, management referred to more clarity in the next couple of months, while in the question-and-answer session it said clarity could come over the next six months after the land acquisition and pilot trials are completed.
The two proposals are at different stages. The confirmed Rs 500 crore project follows about one year of testing, whereas the potential second project still depends on land and pilot outcomes. Management said it had devoted substantial research, development and pilot-trial effort to the proposed investments and had incorporated lessons from past project execution when selecting suppliers, technology and process engineers.
What returns does Vinati Organics expect from the capex?
Vinati Organics expects the announced Rs 500 crore project to deliver a 15%-20% return on investment, or ROI, according to management. Ms. Mutreja indicated asset turnover of about 1.0 times capital employed, with potential to reach 1.2 times to 1.5 times because the products are connected to the company’s established chemistries.
Management cited a similar 15%-20% ROI range for the potential additional Rs 500 crore project, with asset turnover potentially around 1.5 times. These are management expectations rather than reported returns: Vinati Organics did not disclose expected annual revenue, utilisation levels, product-level costs or a timetable for reaching the stated economics.
An analyst asked whether the new lines could retain an earnings before interest, tax, depreciation and amortisation, or EBITDA, margin around 25%. Management said the products are generally more specialised, though not all are, and agreed with the suggested broad margin profile. The response was not formal product-level margin guidance, and Vinati Organics gave no separate EBITDA forecast for the Rs 500 crore project.
Got a follow-up? Ask IRIS
Where will Vinati Organics sell the new specialty chemicals?
Vinati Organics expects exports to account for 65%-70% of sales from the announced specialty-chemicals project, with the remaining sales directed to domestic customers. Management said the plan addresses both Indian and overseas markets, making exports the principal expected outlet for the new products.
The competitive position will differ across three major product segments. Management said Vinati Organics expects to be the only producer in India for some products, while in one segment it could be the second or third producer. It also expects to be fairly large in two of the three segments, while other players will be present in the third.
Management’s rationale is that product adjacency could provide some cost advantage, while access to technology supports entry into products with relatively few global participants. These are management assessments, not independently verified market-share projections. Vinati Organics did not name the chemicals, identify competitors, disclose addressable market sizes or provide country-wise export targets.
How does the expansion fit with Vinati Organics’ current business?
Vinati Organics is advancing the new project while seeking a second-half recovery in ATBS, which accounted for about 27%-28% of first-half FY2027 revenue. For the same period, isobutyl benzene, or IBB, contributed about 12%-15%, Butyl Phenols about 16%-20%, and antioxidants about 15%-17%, showing that the capex is intended to add to a portfolio with several existing segments.
ATBS demand did not recover as expected in the first half because customers were destocking, but management said it was seeing an improvement in volumes and that the third quarter was looking stronger. Vinati Organics described IBB and antioxidants as strong performers in the first half and Butyl Phenols as stable, while expecting the specialty project to broaden its product platform over the two-year commercialisation period.
Vinati Organics reported a 21% EBITDA margin in Q2 FY2027. Management attributed the margin to ATBS sales shifting from the second quarter to the third and fourth quarters, as well as logistics and power costs that were not fully passed through to customers. It said logistics rates had started cooling in Q3 and expected further reductions in Q4, while guiding for a 24%-25% EBITDA margin for FY2027 and expecting 25%-26% in the next financial year.
Conclusion
Vinati Organics has specified the intended economics of its confirmed Rs 500 crore specialty-chemicals expansion: commercialisation in two years, management-targeted ROI of 15%-20%, indicative asset turnover of about 1.0 times to 1.5 times, and export sales of 65%-70%. The strategy relies on products adjacent to existing chemistries, dedicated plants and positions that range from sole Indian producer in some lines to competing with other players in others.
The next disclosed milestone is management’s update within six months on the separate potential Rs 500 crore project, after land acquisition and pilot trials. Vinati Organics’ progress towards commercialising the confirmed project, the recovery in ATBS volumes during the second half of FY2027, and its stated FY2027 EBITDA-margin range of 24%-25% are the other disclosed developments to watch.