










Vinyas Innovative Technologies Limited reports integration margins
Key highlights
- System integration represented 35%-40% of Vinyas business in H1 FY27.
- System-integration programmes carried 24%-26% gross margins, 300-400 basis points above the company gross-margin profile.
- Vinyas targets system integration at 45%-50% of revenue over the next financial years.
- Vinyas expects its 25,000-square-foot system-integration expansion to be ready by the end of FY27.
powered by IRIS
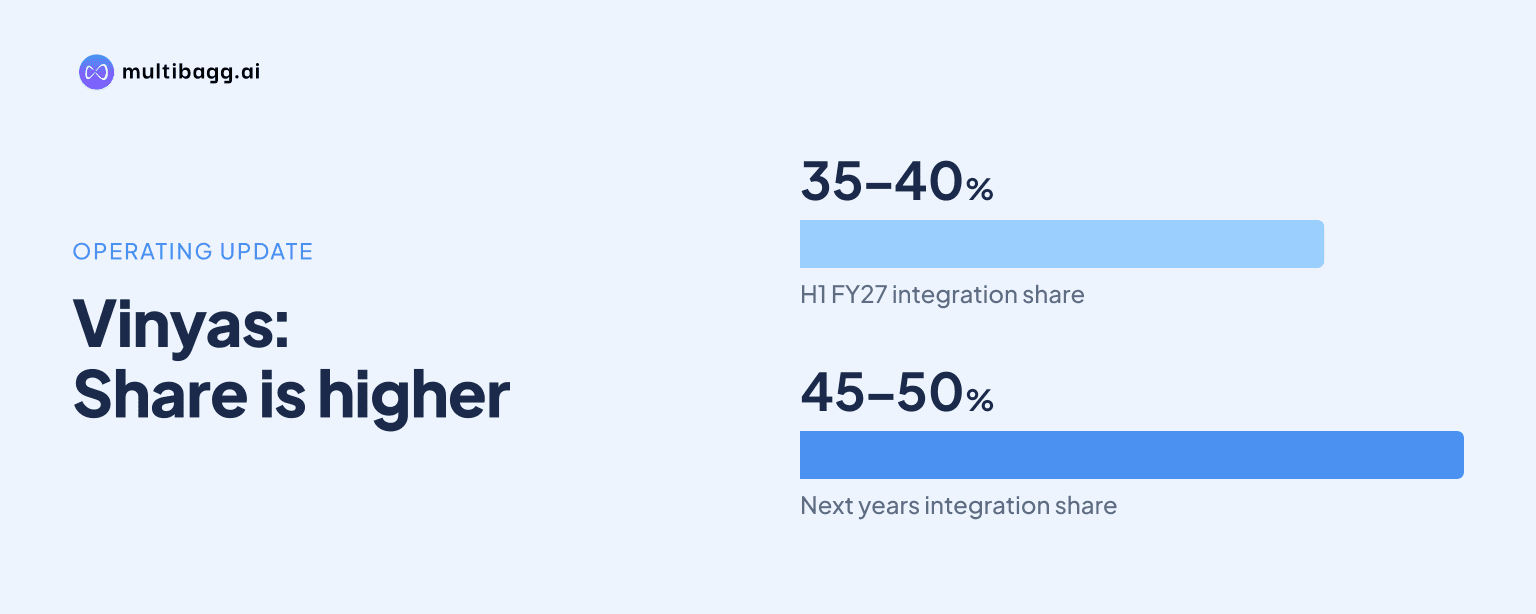
Vinyas said system integration generated 35% to 40% of its business in H1 FY27 and carried gross margins of 24% to 26%, a 300 to 400 basis-point premium over the company gross-margin profile. Management is targeting system integration at 45% to 50% of revenue over the next financial years.
Know Vinyas Innovative Technologies inside out
Results, valuation, peers and who's buying, in one view.
How much of Vinyas business comes from system integration?
Vinyas said system integration accounted for 35% to 40% of business during H1 FY27, following progress made over the previous two years. Management described the work as building a subsystem that combines printed circuit board assembly, or PCBA, cable harnesses and mechanical integration, followed by testing and delivery to the customer.
Management’s target is to lift system integration to 45% to 50% of revenue in the next financial years. That would be an increase of 5 to 15 percentage points from the 35% to 40% H1 FY27 range, depending on where the business mix ended within that range. Vinyas linked the change to its plan to move from a pure PCBA assembly house towards subsystem and system-level manufacturing.
The H1 FY27 measure refers to business, while management framed the longer-term objective as a share of revenue. The call did not disclose a separate rupee revenue figure for system integration, nor did it state the precise mix within the 35% to 40% range. The comparison therefore shows management’s intended direction rather than a reported segment-revenue bridge.
What margin premium does Vinyas earn on system integration?
Vinyas said system-integration programmes carry gross margins of 24% to 26%, about 300 to 400 basis points above the company gross-margin profile. A basis point is one-hundredth of a percentage point, so the stated difference equals 3 to 4 percentage points. The transcript initially recorded “3 to 4 basis points,” but its errata clarified that the intended figure was 300 to 400 basis points.
The premium reflects the added scope of supplying a tested subsystem rather than only assembling the PCBA. Vinyas said this scope can include electronic boards, cable harnesses and mechanical integration before final testing and supply. Management did not provide separate revenue, gross-profit or gross-margin figures for PCBA, so the disclosed 24% to 26% range cannot establish a standalone PCBA margin.
The 24% to 26% figure is a gross-margin disclosure, whereas management’s 11% to 12% expectation for the immediate year concerns earnings before interest, tax, depreciation and amortisation, or EBITDA, margin. The two measures cover different levels of profitability. Management said business mix was the primary current driver of operating-margin improvement.
Will the mix shift raise Vinyas EBITDA margin in FY27?
Vinyas said business mix, rather than operating leverage, is primarily driving operating-margin improvement, but management expects the FY27 mix to remain broadly similar enough for EBITDA margin to stay near 12%. For the immediate year, management guided to EBITDA margins of 11% to 12%, while specifying 11.5% to 12% for the second half of FY27.
The second half normally contributes about 60% to 65% of Vinyas revenue, according to management, but it also expects a larger PCBA mix in that period. As a result, management did not project a second-half margin increase despite higher revenue volume. It said the combination of PCBA and system integration should keep EBITDA margin in the 11.5% to 12% range during H2 FY27.
Management also said operating leverage had improved in the previous half year, but it expected margins to remain in the same range going forward. That stance places the near-term focus on the mix of PCBA and integrated work rather than on a forecast of scale-led expansion. The 45% to 50% integration target applies to coming financial years, not specifically to H2 FY27.
Got a follow-up? Ask IRIS
How is Vinyas adding capacity for system integration?
Vinyas is preparing an additional 25,000 square feet of manufacturing space for mechanical assembly and system integration, with completion expected by the end of FY27. Management said the floor is intended to address a change in business mix, not to raise the company’s stated overall growth expectation of 30% to 35%.
The expansion is within Vinyas’s existing Mysore manufacturing setup, allowing electronics produced on one floor to move to a separate integration floor in the same building. Management put the associated capital expenditure at Rs 2 crore to Rs 3 crore, largely for workstations, work tables and preparing the floor for mechanical assembly rather than for major machinery. It said the dedicated floor would include higher levels of digitisation.
The 25,000-square-foot project separates integration work from the manufacturing floor where it is currently performed. Management said rising business volume and vertical expansion over the previous year supported the need for dedicated space. It did not provide a revenue-capacity figure for the new floor, and reiterated a 30% to 35% growth expectation rather than a revised target linked to the expansion.
What does the system-integration plan mean for Vinyas customer strategy?
Vinyas said it is seeking to begin new customer relationships as a subsystem manufacturer and, where customers have a strategic interest, to pursue system-level manufacturing. Management expects subsystem manufacturing to form the larger share of this work. This approach applies to its plan over the next three to five years to serve global defence programmes as well as Indian defence programmes.
Aerospace and defence will remain a large part of Vinyas business, while management is also pursuing commercial aerospace, transport, medical and industrial manufacturing. The company said its high-mix, low-volume and medium-volume manufacturing focus will continue. It also said system integration should not have a negative working-capital effect because it remains a manufacturing business and expects part of additional requirements to be funded through improved gross margins and internal accruals.
Management said it had seen a broader customer base, particularly in defence and aerospace, after receiving NADCAP certification. It expects initiatives taken in the prior year to support a larger customer base in FY28. The company also said it was strengthening its recently established North American expansion, while Europe remained at an initial-discussion stage with a potential foothold envisaged in 12 to 18 months.
Conclusion
Vinyas has quantified its move up the manufacturing value chain: system integration represented 35% to 40% of H1 FY27 business, delivered 24% to 26% gross margins and carried a stated 300 to 400 basis-point premium. The 45% to 50% revenue-mix objective indicates that management expects integration, testing and mechanical assembly to become a larger part of the business alongside PCBA.
The next items to watch are completion of the 25,000-square-foot system-integration floor by the end of FY27 and whether the mix advances while management maintains its 11.5% to 12% H2 FY27 EBITDA-margin expectation. Management also expects H2 FY27 order inflows of Rs 500 crore to Rs 550 crore, while government programme renewals could lead to purchase orders mainly in Q1 FY28.