










VTM’s Q2 EBITDA rose 39% as material intensity fell 516 bps
Key highlights
- VTM reported Q2 FY27 net sales of Rs 98.17 crore, up 9.2% year on year and down 0.2% sequentially.
- VTM’s Q2 FY27 EBITDA was Rs 6.94 crore, up 38.9% year on year, and its EBITDA margin rose to 7.1% from 5.6%.
- Materials represented 59.8% of Q2 FY27 sales, down 516 basis points year on year from 65.0%.
- VTM’s Q2 FY27 PAT rose 26.6% year on year to Rs 2.94 crore, while finance cost increased 116.2% to Rs 86.05 lakh.
powered by IRIS
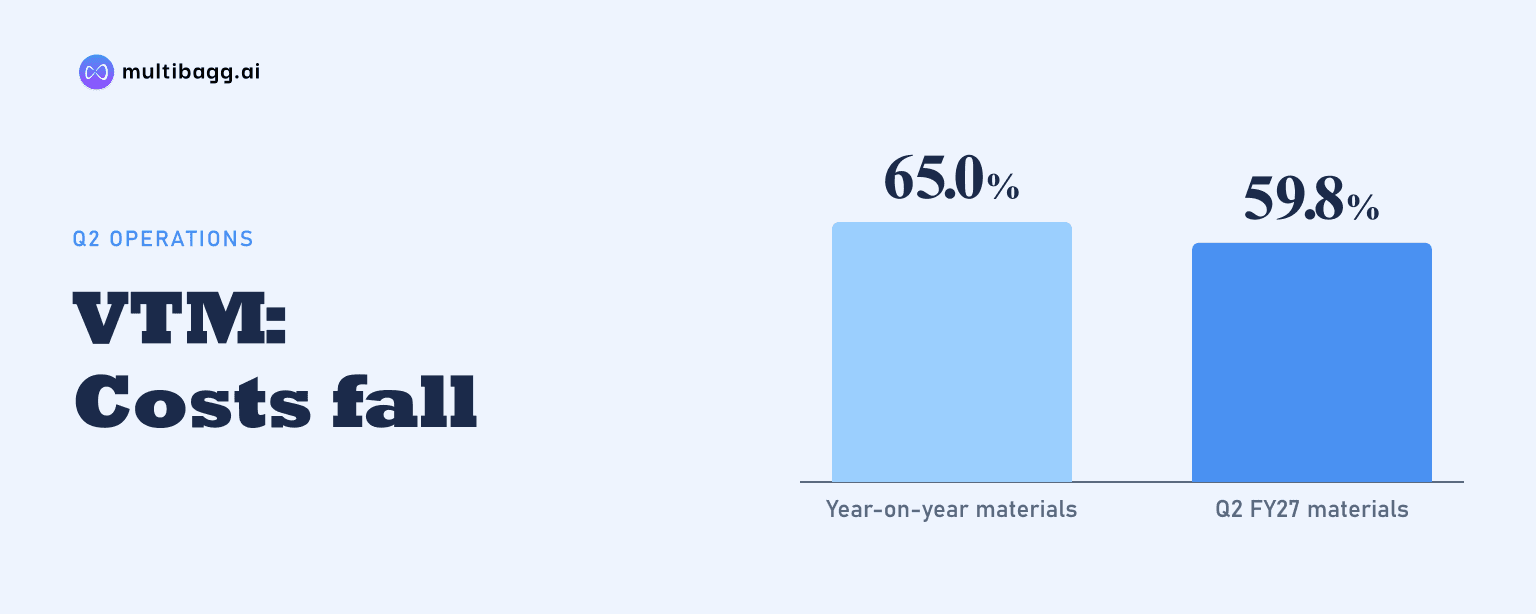
VTM Limited reported Q2 FY27 EBITDA of Rs 6.94 crore, up 38.9% year on year, after material cost fell to 59.8% of sales from 65.0%, while net sales were almost flat sequentially at Rs 98.17 crore for the quarter ended September 30, 2026. Management attributed the material ratio change to product mix.
Know VTM inside out
Results, valuation, peers and who's buying, in one view.
How did VTM’s Q2 FY27 operating profit recover?
VTM’s operating profit recovered as gross margin expanded faster than revenue. Net sales were Rs 98.17 crore in Q2 FY27, up 9.2% from Rs 89.88 crore in Q2 FY26 but 0.2% below Rs 98.40 crore in Q1 FY27. EBITDA, or earnings before interest, tax, depreciation and amortisation, increased from Rs 5.00 crore a year earlier and Rs 5.83 crore in Q1 FY27 to Rs 6.94 crore.
The EBITDA margin reached 7.1% in Q2 FY27, compared with 5.6% in Q2 FY26 and 5.9% in Q1 FY27. The increase was 151 basis points year on year and 114 basis points sequentially. However, the Q2 FY27 margin remained below VTM’s FY26 EBITDA margin of 7.5%.
VTM’s gross margin, defined as net sales less materials consumed adjusted for inventory change, rose 25.3% year on year to Rs 39.47 crore. It also increased 24.8% from Q1 FY27 despite the Rs 0.23 crore sequential decline in sales. The difference between broadly unchanged quarterly revenue and higher gross profit was the main operating change in Q2 FY27.
Why did VTM’s material intensity decline in Q2 FY27?
VTM’s material intensity declined because materials rose only 0.5% year on year while net sales increased 9.2%. Materials net of inventory change were Rs 58.70 crore in Q2 FY27, compared with Rs 58.38 crore in Q2 FY26. Management said that the lower material-to-sales ratio reflected a change in product mix.
Materials represented 59.8% of Q2 FY27 sales, versus 65.0% in Q2 FY26 and 67.9% in Q1 FY27. VTM reported a 516-basis-point year-on-year decline and an 808-basis-point sequential decline in this ratio. Gross margin consequently reached 40.2% of sales, compared with 35.0% a year earlier, 32.1% in Q1 FY27 and 37.1% for FY26.
The sequential movement was driven by materials falling Rs 8.09 crore from Rs 66.79 crore in Q1 FY27 while sales declined only Rs 0.23 crore. The presentation does not identify the individual products behind the mix change or quantify their respective contribution. Management’s disclosed explanation is limited to the change in product mix.
Got a follow-up? Ask IRIS
Which costs absorbed VTM’s gross-margin improvement?
VTM’s other expenses and employee benefits absorbed part of the gross-margin improvement. Other expenses rose 21.6% year on year to Rs 24.19 crore and increased 39.2% from Rs 17.38 crore in Q1 FY27. Management said this reflected additional selling and distribution spending to retain existing customers and explore new markets.
Employee benefits were Rs 8.34 crore in Q2 FY27, up 26.1% from Rs 6.61 crore in Q2 FY26, although they were 0.7% below Rs 8.40 crore in Q1 FY27. Management attributed the year-on-year rise to human-resources additions and the effect of labour-code compliance changes. Employee benefits accounted for 8.5% of sales in both Q2 FY27 and Q1 FY27, compared with 7.4% a year earlier.
VTM’s year-on-year EBITDA bridge records a Rs 8.29 crore gain from higher net sales, while materials expense increased by Rs 32 lakh. Higher employee cost reduced EBITDA by Rs 1.73 crore and higher other expenses reduced it by Rs 4.30 crore. These movements reconcile EBITDA from Rs 5.00 crore in Q2 FY26 to Rs 6.94 crore in Q2 FY27.
How did higher fixed charges affect VTM’s Q2 FY27 profit?
VTM’s profit after tax rose 26.6% year on year to Rs 2.94 crore, slower than EBITDA growth because depreciation, amortisation and finance cost increased. Depreciation and amortisation were Rs 3.59 crore, up 25.8% from Rs 2.85 crore in Q2 FY26 and 16.7% from Rs 3.07 crore in Q1 FY27. Finance cost rose 116.2% year on year to Rs 86.05 lakh from Rs 39.80 lakh.
Profit before tax before exceptional items was Rs 3.63 crore, up 24.8% year on year and 40.0% sequentially. Other income was Rs 1.14 crore, compared with Rs 63.67 lakh in Q1 FY27 and Rs 1.16 crore in Q2 FY26. VTM reported no exceptional items in Q2 FY27, Q1 FY27 or Q2 FY26.
PAT increased 52.1% from Rs 1.93 crore in Q1 FY27, and the PAT margin rose to 3.0% from 2.0% sequentially and 2.6% a year earlier. Basic earnings per share were Rs 0.29, against Rs 0.19 in Q1 FY27 and Rs 0.23 in Q2 FY26. Total comprehensive income rose only 4.6% year on year to Rs 3.71 crore because other comprehensive income declined to Rs 77 lakh from Rs 1.23 crore, according to management.
Conclusion
VTM’s Q2 FY27 margin recovery came principally from a lower material share of revenue rather than sequential sales growth. Net sales were Rs 98.17 crore, nearly unchanged from Q1 FY27, while gross margin increased to 40.2% and EBITDA rose to Rs 6.94 crore. Higher selling, distribution, employee, depreciation and finance costs limited the conversion of gross-margin growth into PAT.
The next reported quarter will indicate whether the Q2 FY27 product-mix effect persists alongside spending on customer retention and new markets. Management identified raw-material prices, domestic and export textile demand, foreign-exchange movements and regulatory changes as factors that could affect results, while providing no quantified operating target or forward guidance.