










Symbiotec gross margin rose as PAT margin declined in FY26
Key highlights
- Symbiotec's gross margin increased to 63.7% in FY26 from 55.2% in FY24.
- Symbiotec's revenue rose to Rs 869.1 crore in FY26 from Rs 716.2 crore in FY24.
- Symbiotec's PAT margin declined to 12.6% in FY26 from 14.0% in FY24.
- Symbiotec recorded Rs 226.9 crore of investing cash outflow and Rs 10.0 crore of closing cash in FY26.
powered by IRIS
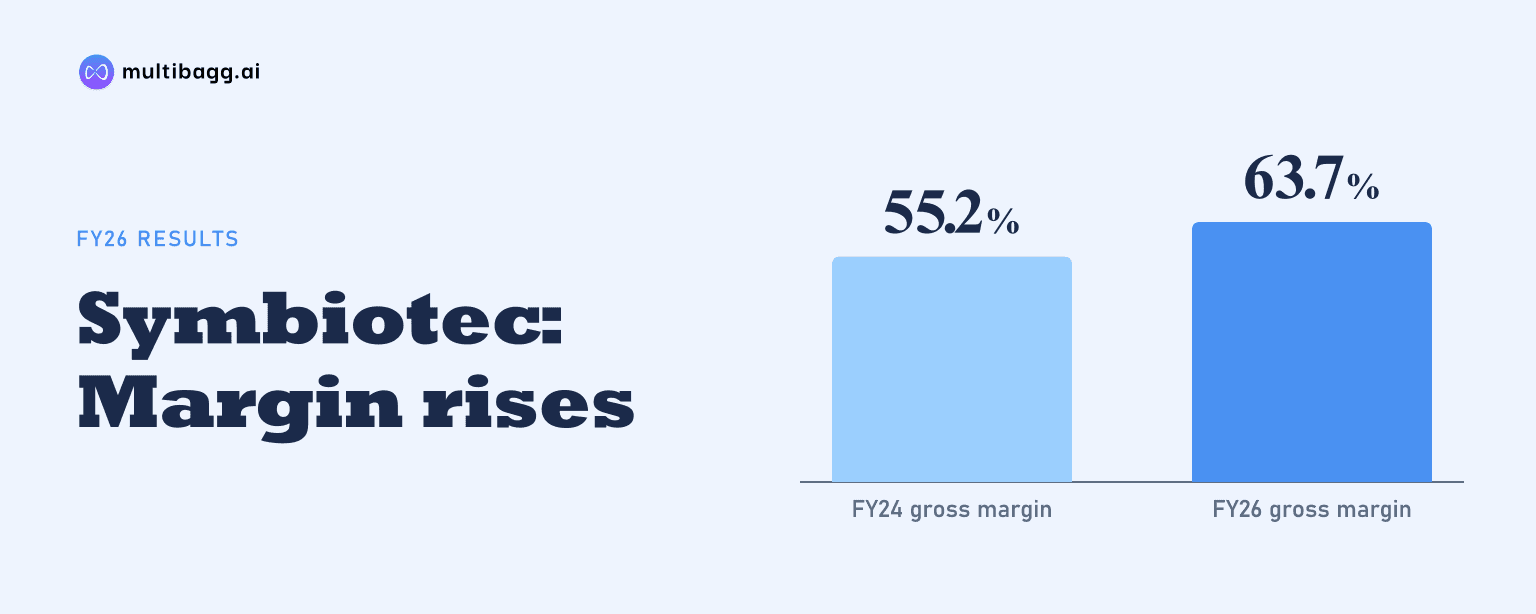
In FY26, Symbiotec Pharmalab Ltd. lifted gross margin to 63.7%, from 55.2% in FY24, but its profit after tax (PAT) margin fell to 12.6% from 14.0%. Revenue rose to Rs 869.1 crore and gross profit to Rs 553.7 crore, while finance cost reached Rs 25.3 crore and a Rs 9.0 crore exceptional loss was recorded.
Know Symbiotec Pharmalab inside out
Results, valuation, peers and who's buying, in one view.
How did Symbiotec's gross margin change from FY24 to FY26?
Symbiotec's gross margin increased by 8.5 percentage points over FY24 to FY26, as revenue rose by Rs 152.9 crore while cost of goods sold declined by Rs 5.5 crore. Gross profit increased by Rs 158.5 crore to Rs 553.7 crore in FY26, compared with Rs 395.2 crore in FY24.
The improvement occurred in both years. Gross margin reached 60.4% in FY25, up from 55.2% in FY24, and then increased to 63.7% in FY26. Revenue rose from Rs 751.6 crore in FY25 to Rs 869.1 crore in FY26, while cost of goods sold increased from Rs 297.4 crore to Rs 315.5 crore.
Why did Symbiotec's PAT margin decline despite gross-margin expansion?
Symbiotec's PAT margin declined because the higher gross profit did not fully flow through costs below the operating-profit level. PAT rose by Rs 9.8 crore to Rs 109.9 crore between FY24 and FY26, but revenue grew by Rs 152.9 crore, taking PAT margin down 1.4 percentage points to 12.6%.
Finance cost rose from Rs 7.2 crore in FY24 to Rs 25.3 crore in FY26, while depreciation and amortisation increased from Rs 38.8 crore to Rs 53.3 crore. FY26 also included a Rs 9.0 crore exceptional loss related to the impact of the new wages code on gratuity and leave encashment, and other income fell from Rs 7.1 crore to Rs 3.1 crore.
Reported earnings before interest, tax, depreciation and amortisation (EBITDA) rose to Rs 237.9 crore in FY26 from Rs 171.3 crore in FY24, lifting EBITDA margin to 27.4% from 23.9%. Earnings before interest and tax (EBIT) increased from Rs 139.6 crore to Rs 187.7 crore, while its margin rose from 19% to 22%.
What does Symbiotec's cash flow show about expansion spending?
Symbiotec generated Rs 174.6 crore of net cash from operating activities in FY26, compared with Rs 47.3 crore in FY25 and Rs 187.5 crore in FY24. The FY25 decline coincided with a Rs 126.8 crore working-capital outflow, whereas FY26 recorded a Rs 2.5 crore outflow and Rs 236.3 crore of cash generated from operations.
Investing cash outflows exceeded net operating cash inflows in all three reported years: Rs 206.4 crore in FY24, Rs 306.5 crore in FY25 and Rs 226.9 crore in FY26. Financing activities provided Rs 36.0 crore in FY26 after providing Rs 278.2 crore in FY25, while cash and cash equivalents fell to Rs 10.0 crore at the end of FY26 from Rs 26.4 crore a year earlier.
The balance sheet records a shift from capital work-in-progress to property, plant and equipment. Property, plant and equipment increased to Rs 1,084.4 crore in FY26 from Rs 401.5 crore in FY25, while capital work-in-progress decreased to Rs 64.5 crore from Rs 568.2 crore. The presentation says the Ujjain facility has been commissioned and has started research and development and pilot-scale operations for large-volume fermentation manufacturing.
Got a follow-up? Ask IRIS
How did Symbiotec's leverage, capital base and efficiency ratios move?
Symbiotec reported debt to equity of 0.3 times in FY26, down from 0.6 times in FY25 and equal to FY24's 0.3 times. Total equity rose to Rs 1,149.6 crore in FY26 from Rs 814.7 crore in FY25, while FY26 borrowings comprised Rs 68.4 crore of non-current borrowings and Rs 319.5 crore of current borrowings.
The maturity mix changed during FY26. Non-current borrowings declined from Rs 253.0 crore in FY25 to Rs 68.4 crore, whereas current borrowings increased from Rs 287.9 crore to Rs 319.5 crore. Current assets were Rs 485.5 crore at FY26-end, below current liabilities of Rs 527.6 crore; the corresponding FY25 figures were Rs 492.9 crore and Rs 472.6 crore.
Adjusted return on capital employed (ROCE) increased to 30% in FY26 from 25% in FY24. Symbiotec defines adjusted ROCE by excluding capital employed attributable to Knovea Pharmaceutical Private Limited and Symbiotec Zenfold Private Limited, and making corresponding EBIT adjustments. Operating cash flow to EBITDA was 0.8 times in FY26, versus 0.2 times in FY25 and 1.1 times in FY24, while gross fixed asset turnover was 1.5 times compared with 1.4 times in each of the preceding two years.
Conclusion
Symbiotec's FY24-to-FY26 results show a widening gap between operating-margin improvement and net-profit conversion. Gross margin increased 8.5 percentage points and EBITDA margin rose 3.5 percentage points, but PAT margin declined 1.4 percentage points as finance cost, depreciation and amortisation, lower other income and the Rs 9.0 crore exceptional loss affected earnings after operating profit.
What to watch next is the commercial contribution and funding requirement of the expansion programme. Symbiotec plans to use the commissioned Ujjain facility for fermentation manufacturing, industrial biotechnology contract development and manufacturing organisation opportunities and backward integration, while pursuing two double chamber vial products and additional products under the 505(b)(2) pathway.