










Symbiotec says ₹1,000 crore capex revenue starts in 6–12 months
Key highlights
- Symbiotec estimates total gross capex of ₹1,672 crore by the end of FY27, compared with ₹1,509 crore on 30 September 2026.
- About ₹1,000 crore, or 60% of estimated FY27 gross capex, is expected to begin generating revenue within 6–12 months.
- CDMO services account for ₹584 crore of estimated end-FY27 gross capex, while dual chamber vials account for ₹377 crore.
- H1FY27 consolidated revenue rose 25% to ₹498 crore, while API revenue increased 11% to ₹442 crore.
powered by IRIS
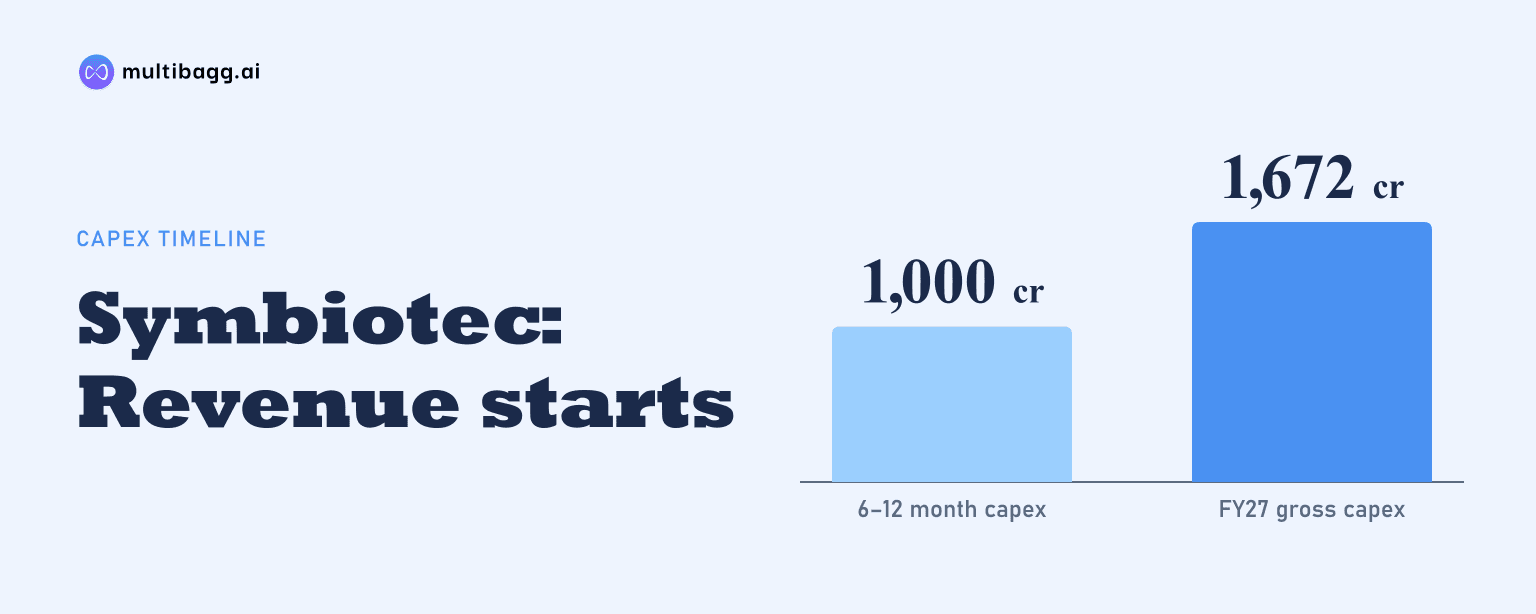
Symbiotec Pharmalab Limited expects about ₹1,000 crore, or 60% of its estimated ₹1,672 crore FY27 gross capital expenditure, to begin generating revenue within 6–12 months from 30 September 2026. The expected commercialisation is centred on dual chamber vials and contract development and manufacturing organisation, or CDMO, capacity supported by partner reservations and take-or-pay arrangements.
Know Symbiotec Pharmalab inside out
Results, valuation, peers and who's buying, in one view.
What capex does Symbiotec expect to begin generating revenue?
Symbiotec expects approximately ₹1,000 crore of capex, representing about 60% of estimated FY27 gross capex, to begin generating revenue in the next 6–12 months. Gross capex stood at ₹1,509 crore on 30 September 2026, and the company estimates total gross capex of ₹1,672 crore by the end of FY27.
The capex presentation separates ₹649 crore of existing steroids-and-hormones active pharmaceutical ingredients, or API, capacity from newer projects. The existing API business, which already caters to revenue, represents 39% of estimated FY27 gross capex. The remaining 61% is allocated to complex injectables, CDMO services and new API projects that the company identifies as new-project capex yet to generate revenue.
The newer projects total ₹1,024 crore on the estimated end-FY27 capex figures in the table. Of this, CDMO services are the largest component at ₹584 crore, ahead of ₹377 crore for dual chamber vials and ₹63 crore for new API capacity. The company describes the revenue start estimate as applying to about ₹1,000 crore, or roughly 60%, of total capex.
How is Symbiotec supporting the new capacity commercially?
Symbiotec says a majority of dual chamber vial capacity is reserved with a strategic partner, while take-or-pay customer arrangements cover a majority of CDMO capacity. Its capex slide also states that revenue for a majority of new capacities is already contracted, although it does not disclose customer names, contract values, pricing or capacity-specific revenue commitments.
In industrial biotechnology, Symbiotec has a 10-year take-or-pay agreement with a US-based alternative-protein customer, with project capex on track. It also reported that a 10-year take-or-pay term sheet with a Europe-based alternative-protein company was at an advanced stage of agreement signing, and that initial manufacturing was expected to commence in Q4.
The pharmaceutical CDMO project for insulin drug substance has a five-year take-or-pay agreement, with capex on track. Symbiotec also says 750 kilolitres of new CDMO capacity is to be initiated and backed by customer agreement. These arrangements provide the stated commercial framework, but the presentation does not quantify the revenue expected from individual agreements.
Got a follow-up? Ask IRIS
How did Symbiotec perform while the new projects were built?
Symbiotec reported consolidated revenue of ₹498 crore in H1FY27, up 25% from ₹399 crore in H1FY26, while profit after tax rose 34% to ₹66 crore from ₹49 crore. Reported earnings before interest, tax, depreciation and amortisation, or EBITDA, increased 26% to ₹136 crore from ₹108 crore over the same period.
The API business remained the main reported operating base, with H1FY27 revenue of ₹442 crore, up 11% from ₹399 crore in H1FY26. API EBITDA rose 15% to ₹137 crore from ₹119 crore. Management attributed API revenue growth to volume growth and a favourable product mix, and stated that API gross margins were above 60% and API EBITDA margin was about 30%.
New businesses recorded ₹53 crore of milestone revenue, which management said was partly recognised in Q2FY27 following completed milestones under a US distribution licensing agreement for two dual chamber vial products. The H1FY27 highlights list ₹57 crore of new-business operating expenditure, including abbreviated new drug application, or ANDA, filing fees, and ₹24 crore of depreciation. The detailed profit and loss statement rounds new-business operating expenses to ₹58 crore, versus ₹10 crore in H1FY26.
What injectable and CDMO milestones are scheduled next?
Symbiotec expects commercial supplies for two US dual chamber vial products to commence next year after signing a distribution licensing agreement. The first ANDA for a dual chamber vial molecule has been filed and accepted by the US Food and Drug Administration, or USFDA, and the company describes it as the first generic filing for that product in the US market.
The second ANDA filing is scheduled for Q4 FY27. Symbiotec says it submitted a pre-submission facility correspondence, or PFC, intended to qualify for expedited Priority Review. Apart from the ₹53 crore milestone revenue partly recognised in Q2FY27, these regulatory and licensing developments are not reported as commercial supply revenue.
For CDMO, the insulin drug-substance project is expected to file for regulatory approval in Q4 FY27 or Q1 FY28. Initial manufacturing for the Europe-based alternative-protein project is expected in Q4, subject to the agreement signing progressing as management described. These dates are management plans and expectations rather than confirmation that full commercial production has begun.
How does current revenue-generating capex compare with the pipeline?
Symbiotec reports that 39% of its estimated ₹1,672 crore FY27 gross capex is currently generating revenue, compared with 61% in new projects. The ₹649 crore API steroids-and-hormones base is the revenue-generating portion identified on the capex slide, which also cites asset turns of about 1.5 times for this existing business.
The pipeline is weighted towards CDMO and complex injectables, with estimated end-FY27 capex of ₹584 crore and ₹377 crore respectively. By comparison, API revenue of ₹442 crore represented most of consolidated H1FY27 revenue of ₹498 crore, while the newer businesses recorded ₹53 crore of milestone revenue and ₹24 crore of depreciation. The disclosed shift is therefore from an API-led revenue base toward capacity that is awaiting further commercial supply and contract execution.
Conclusion
Symbiotec’s presentation identifies about ₹1,000 crore of capex as expected to start generating revenue within 6–12 months, against estimated total FY27 gross capex of ₹1,672 crore. The commercialisation plan rests chiefly on ₹377 crore of dual chamber vial capex and ₹584 crore of CDMO capex, where the company cites strategic-partner reservations or take-or-pay customer arrangements for a majority of capacity.
The next disclosed milestones are the second ANDA filing in Q4 FY27, initial manufacturing for the Europe-based alternative-protein project in Q4, and the insulin drug-substance regulatory filing planned for Q4 FY27 or Q1 FY28. Management also expects US commercial supplies for the dual chamber vial products to commence next year, which will indicate how the existing ₹53 crore milestone contribution develops into supply revenue.