










Wakefit Innovations Limited to Report Q2 FY27 November 12
Key highlights
- Wakefit Innovations Limited is scheduled to announce Q2 FY27 results on November 12, 2026.
- The supplied Q2 FY27 revenue range is ₹460-475 crore, implying 16-18% year-on-year growth.
- Q1 FY27 revenue from operations was ₹404.91 crore, up 16.65% year on year.
- Wakefit is targeting 80 retail-store additions in FY27, with 40-45 estimated net additions in H1.
powered by IRIS
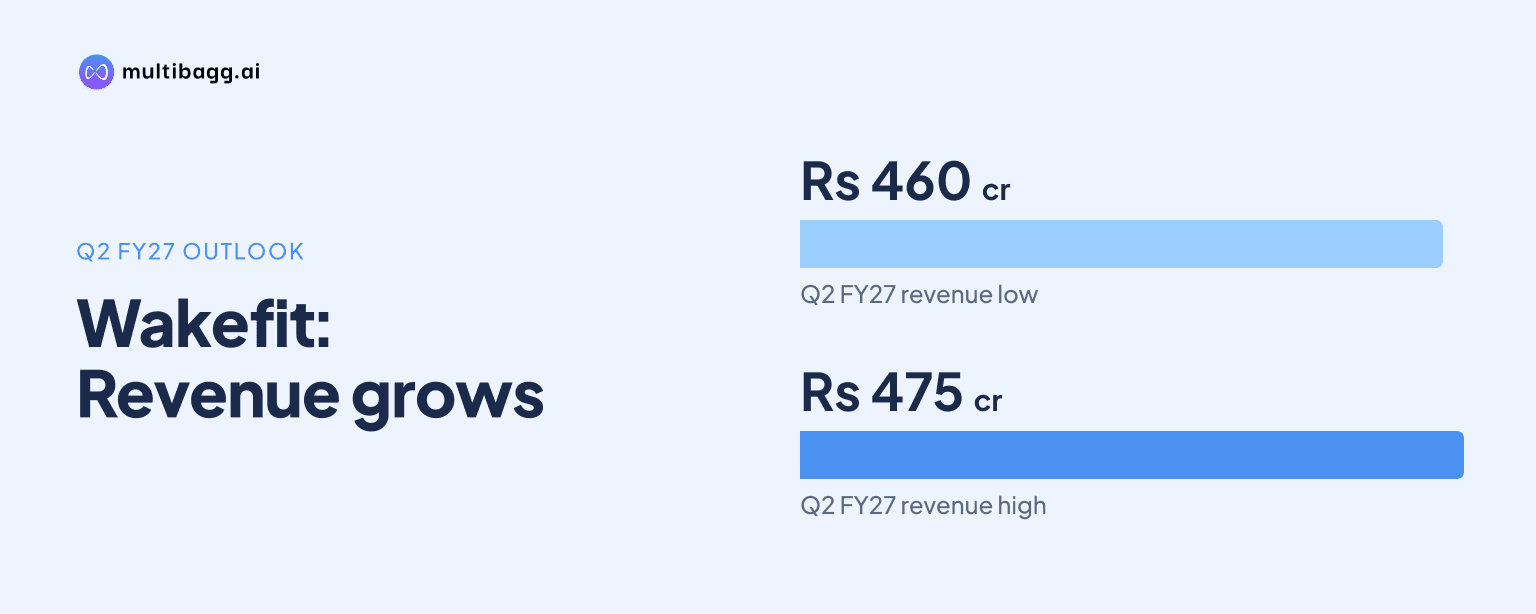
Wakefit Innovations Limited is scheduled to report its Q2 FY27 results on November 12, 2026, with revenue expected at ₹460-475 crore and investors focused on whether its planned 80-store FY27 expansion is sustaining growth without weakening margins. The result will follow 16.65% year-on-year revenue growth in Q1 FY27.
Know Wakefit Innovations inside out
Results, valuation, peers and who's buying, in one view.
What will Wakefit report for Q2 FY27?
Wakefit Innovations Limited is expected to announce unaudited financial results for the quarter ended September 30, 2026, on November 12. The supplied earnings preview places Q2 revenue guidance at about ₹460 crore to ₹475 crore, representing expected year-on-year growth of 16% to 18%. It also indicates profit after tax expectations of ₹25 crore to ₹28 crore.
The company is due to hold a virtual earnings conference call on November 13 at 11:00 AM IST. Management, including the Chairman, Chief Executive Officer and Chief Financial Officer, is expected to discuss the quarter after the release. The call gives shareholders and analysts an opportunity to seek details on business performance, retail expansion and the outlook disclosed by the company.
The Q2 release falls in a busy earnings period, with 1,270 companies, including Ola Electric, Garden Reach Shipbuilders & Engineers, Cochin Shipyard and Kalyan Jewellers, scheduled to announce Q2 FY27 results between November 10 and 13. For Wakefit, the key question is whether growth has remained consistent while its physical retail network expands.
Why are revenue growth and margin under scrutiny?
The central test for Wakefit is whether revenue can stay within the indicated 16% to 18% growth range while costs associated with new stores are absorbed. The supplied preview says EBITDA margin is expected in a 9% to 10% range and identifies store capital expenditure and labour inflation as key cost pressures. It adds that an EBITDA margin above 8.5% would indicate that expansion-related costs are not causing a sharp margin decline.
Wakefit reported revenue from operations of ₹404.91 crore in Q1 FY27, up 16.65% year on year and 17.84% sequentially from ₹343.60 crore in Q4 FY26. Total income for the June quarter was ₹420.53 crore. These are separate measures, with revenue from operations excluding other income while total income includes it.
The company reported Q1 FY27 EBITDA, excluding other income, of ₹56.40 crore and an EBITDA margin of 13.9%. Profit after tax was ₹23.38 crore, up 19.2% year on year, while basic earnings per share were ₹0.71. The earnings preview separately refers to a 9.1% Q1 operating EBITDA margin, so investors may seek clarification on the margin definition used in the Q2 discussion.
How important is Wakefit's retail expansion plan?
Wakefit's retail expansion is important because management has set a target of adding 80 retail stores in FY27. The supplied preview estimates net additions of about 40 to 45 stores during the first half, making the Q2 update a checkpoint on the pace of execution. Investors will look for management's reported store count and its account of new-store operating costs.
The retail channel was already a significant source of growth in FY26. Chairman, CEO and Executive Director Ankit Garg said the company's retail-channel growth was 49% during that year. In the same FY26 commentary, he said the mattress segment grew about 17% year on year and the furniture category grew about 24%.
A larger store base can widen product access and support customer engagement, but it also requires spending on leases, fit-outs, staff and local operations. The Q2 result and conference call may therefore be assessed not only for the number of openings, but also for the retail versus direct-to-consumer sales mix and like-for-like store performance. Those metrics were specifically identified as items to watch in the supplied preview.
Got a follow-up? Ask IRIS
What does Wakefit's recent financial record show?
Wakefit recorded revenue from operations of ₹1,488.94 crore in FY26, compared with ₹1,273.69 crore in FY25, a year-on-year increase of 16.90%. FY26 total income was ₹1,534.37 crore, while the company reported profit for the year of ₹189.18 crore after a ₹35.00 crore loss in FY25.
Quarterly performance has varied with seasonality and category conditions. Revenue was ₹377 crore in September 2025, ₹421 crore in December 2025, ₹344 crore in March 2026 and ₹405 crore in June 2026. Q4 FY26 revenue from operations of ₹343.60 crore was lower sequentially than ₹421.34 crore in Q3 FY26, though it was 13.55% higher than the corresponding quarter a year earlier.
The company said after Q1 FY27 that the mattress category remained a key driver, while furniture faced temporary headwinds. It also said it was managing raw-material volatility through calibrated pricing actions and anticipated some margin compression in the first half of FY27. These factors make the Q2 category mix and margin commentary relevant to the assessment of the full-year plan.
What could Q2 FY27 mean for investors and operations?
Q2 FY27 will show whether Wakefit is progressing toward its stated FY27 growth ambition of 18% to 20%. The supplied preview notes that growth in the 16% to 18% range would keep that objective on track, while growth below 15% would likely prompt closer scrutiny of the full-year target. This is an assessment framework rather than a company-confirmed forecast.
For investors, the key reported measures will be revenue from operations, profitability, margin definitions and net store additions. The prior Q1 result generated little immediate share-price movement in the data supplied, with the stock moving from ₹127.90 to ₹127.76 on August 7, 2026, a decline of 0.1%. That single-day reaction does not establish a broader market trend.
For customers and operations, the store rollout could affect availability of Wakefit's mattress and furniture products across more locations. But the provided material does not identify the cities or regions for planned openings. Management's Q2 remarks may provide more information on geographic expansion, store productivity and the balance between physical retail and direct-to-consumer sales.
Conclusion
Wakefit enters its Q2 FY27 announcement with a clear operating trade-off: maintain revenue growth while funding a faster retail rollout and managing cost pressure. The supplied range of ₹460 crore to ₹475 crore in revenue, ₹25 crore to ₹28 crore in profit after tax, and an estimated 40 to 45 H1 store additions will frame the market's review of execution.
The next scheduled event is the November 13, 2026 earnings call at 11:00 AM IST. Investors will watch for confirmed Q2 figures, the reported progress toward the 80-store FY27 target, the retail and direct-to-consumer mix, like-for-like store performance, and management's comments on raw-material and labour costs.