










Western Carriers (India) Limited reports Q2 revenue of ₹448.6 crore
Key highlights
- Western Carriers reported Q2 FY27 revenue of ₹448.6 crore, up 2.0% year-on-year.
- Q2 FY27 EBITDA rose 16.5% year-on-year to ₹21.9 crore, with a 4.88% margin.
- Q2 FY27 net profit was ₹9.1 crore and the net profit margin was 2.03%.
- H1 FY27 revenue stood at ₹913.5 crore and net profit was ₹17.8 crore.
powered by IRIS
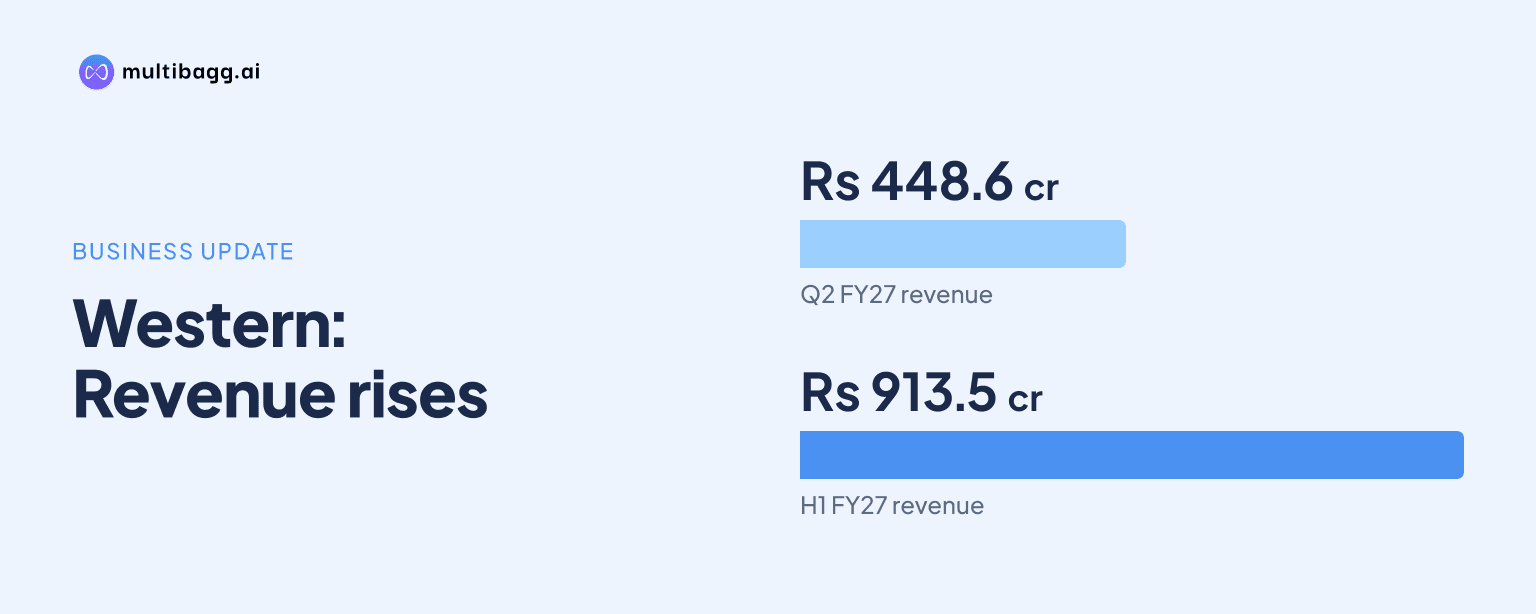
Western Carriers (India) Limited reported revenue from operations of ₹448.6 crore in Q2 FY27, up 2.0% year-on-year, while EBITDA rose to ₹21.9 crore and net profit reached ₹9.1 crore. The result reflects higher domestic volumes, which helped offset a decline in export-import activity during the quarter ended September 30, 2026.
Know Western Carriers (India) inside out
Results, valuation, peers and who's buying, in one view.
What did Western Carriers report for Q2 FY27?
Western Carriers reported consolidated revenue from operations of ₹448.6 crore for Q2 FY27, compared with ₹439.6 crore in Q2 FY26. The 2.0% year-on-year increase was modest, but it came alongside an improvement in operating profit. EBITDA was ₹21.9 crore, compared with ₹18.8 crore a year earlier, representing growth of 16.5%.
Net profit for the quarter was ₹9.1 crore, compared with approximately ₹8.9 crore in the corresponding quarter of FY26. The company reported a net profit margin of 2.03% and an EBITDA margin of 4.88% for the quarter. The results were discussed during the company’s earnings call held on November 16, 2026.
For the first half of FY27, Western Carriers recorded revenue of ₹913.5 crore and net profit of ₹17.8 crore. The half-year net profit margin stood at 1.95%, according to the investor presentation. These figures provide the financial context for the company’s operating performance in the September quarter.
How did domestic volumes support the quarterly performance?
Domestic volume growth supported Western Carriers’ Q2 FY27 performance, with call summaries indicating that domestic volumes increased by more than 21% sequentially. This growth helped the company manage the effect of lower export-import, or EXIM, activity on its revenue mix during the quarter.
The available call material describes domestic volumes as the principal offset to an EXIM decline. That distinction matters because logistics companies can face differing demand conditions across domestic freight, industrial supply chains, ports and cross-border cargo. Western Carriers’ quarter showed that growth in one part of its network could support revenue even when another segment was weaker.
The company did not provide numeric guidance for the second half of FY27 during the earnings call. As a result, the disclosed figures indicate what was achieved in the September quarter but do not establish a formal revenue, profit or margin target for the remainder of the financial year.
Got a follow-up? Ask IRIS
What operational developments did the company disclose?
Western Carriers cited terminal commissioning at Kolkata and Morbi in its Q2 FY27 results update. The disclosure confirms operational progress at these locations, although the supplied information does not specify investment amounts, handling capacity, expected revenue contribution or commissioning dates for the individual terminals.
Terminal infrastructure is relevant to an integrated logistics operator because it can support cargo handling and network operations. However, the company has not disclosed a quantified financial impact from the Kolkata and Morbi commissioning in the available material. Investors should therefore separate the confirmed operational update from any assumptions about future volumes or profitability.
The earnings call was conducted after the company’s earlier results communication dated November 7, 2026. A recording of the November 16 call was made available through the company’s website, while the provided summaries note that no company-filed full transcript was available in the cited material.
Why do the Q2 results matter for investors?
The Q2 figures matter because EBITDA increased faster than revenue. Revenue grew 2.0% year-on-year, while EBITDA increased 16.5% to ₹21.9 crore. This indicates that the quarter delivered a higher operating profit level despite limited topline expansion, though the available information does not identify the precise cost or pricing factors behind the improvement.
Net profit of ₹9.1 crore also remained close to 2% of revenue. For investors, the difference between the 4.88% EBITDA margin and the 2.03% net profit margin highlights the importance of tracking costs beyond operating EBITDA, including finance costs, depreciation, taxes and other items, none of which are detailed in the supplied call summary.
Domestic demand and EXIM conditions will remain important for the logistics sector. Western Carriers’ reported results show that domestic volume growth was sufficient to cushion weaker EXIM activity in Q2, but the company did not give a numerical outlook that would allow investors to measure expected second-half growth against a stated management target.
Conclusion
Western Carriers delivered Q2 FY27 revenue of ₹448.6 crore, EBITDA of ₹21.9 crore and net profit of ₹9.1 crore. Domestic volumes, reported to be up more than 21% sequentially, supported the quarter and helped offset softer EXIM activity, while operating profit growth exceeded revenue growth.
The next areas to watch are the company’s subsequent disclosures on domestic and EXIM volumes, the operational contribution from the Kolkata and Morbi terminals, and any quantified outlook for H2 FY27. Management did not provide numeric second-half guidance on the November 16 earnings call.