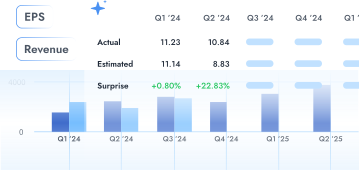
Escorts Kubota Limited manufactures agricultural tractors, engines, farm machinery, construction equipment, material-handling products, and railway equipment, with current performance primarily driven by agri machinery and construction equipment. Its portfolio spans Farmtrac, Powertrac, Digitrac, and Kubota-branded tractors, alongside engines, implements, harvesters, cranes, backhoe loaders, compactors, and related services. The company gained domestic tractor market share despite a roughly 3% industry contraction in the second quarter. Escorts Kubota Limited’s domestic tractor volumes rose marginally to 32,628 units, supported by refreshed products, stronger channel execution, and new offerings across Farmtrac, Powertrac, Digitrac, and Kubota, demonstrating relative resilience during a regionally uneven rural slowdown. Construction equipment was the standout growth engine, with volumes increasing approximately 54% and revenue rising 58.6% year-on-year. Operating leverage and repeated price increases lifted segment EBIT margin to 7.9% from 3.8%, although management expects industry growth to moderate from the exceptionally strong current trajectory as the comparison base rises. Profitability remains under significant pressure despite revenue growth. Second-quarter EBITDA margin fell to 9.0% from 13.1%, as commodity inflation, manpower costs, process expenses, and higher manufacturing overheads outweighed price increases. Management expects the third quarter to remain difficult, with more meaningful margin recovery anticipated from the fourth quarter as cumulative pricing takes effect. The medium-term strategic agenda combines product broadening, localization, Kubota collaboration, and substantial manufacturing expansion. A proposed INR 2,000 crore Uttar Pradesh project will be phased across tractors, construction equipment, and spare-parts logistics, while upcoming four-wheel-drive launches and localized Kubota products target higher-growth application segments.