










Amrutanjan H1 profit fell despite 12.47% sales growth in FY27
Key highlights
- Amrutanjan’s H1 FY27 net sales rose 12.47% to Rs 238.15 crore from Rs 211.75 crore.
- Amrutanjan’s H1 FY27 profit after tax fell to Rs 21.65 crore from Rs 22.27 crore.
- Women’s Hygiene & Personal Care sales rose 25.17% to Rs 76.84 crore in H1 FY27.
- Other expenses increased 32.17% to Rs 35.21 crore in H1 FY27.
powered by IRIS
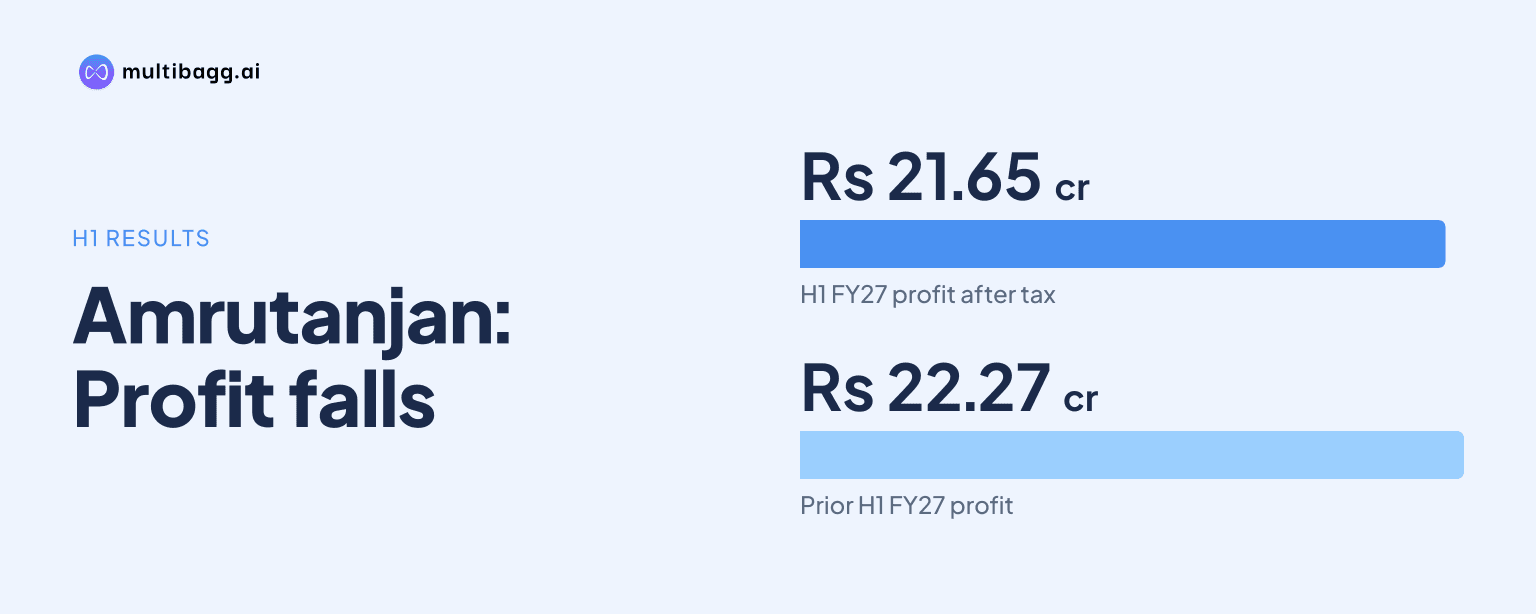
Amrutanjan’s profit after tax fell to Rs 21.65 crore in H1 FY27 from Rs 22.27 crore in H1 FY26, even as net sales rose 12.47% to Rs 238.15 crore. Higher raw-material and packing-material prices, a 32.17% increase in other expenses and higher Comfy advertising coincided with the lower half-year profit.
Know Amrutanjan Health Care inside out
Results, valuation, peers and who's buying, in one view.
What did Amrutanjan report for H1 FY27?
Amrutanjan reported H1 FY27 net sales of Rs 238.15 crore, up from Rs 211.75 crore in H1 FY26, while profit after tax declined by Rs 0.62 crore to Rs 21.65 crore. Profit before tax was Rs 29.17 crore, compared with Rs 30.51 crore a year earlier. Sales therefore increased Rs 26.40 crore without producing a higher reported half-year profit.
Amrutanjan’s profit before exceptional item and tax rose 2.23% to Rs 31.19 crore in H1 FY27, substantially slower than the 12.47% sales growth. Reported profit before tax was Rs 2.02 crore below that measure in H1 FY27, while both measures were Rs 30.51 crore in H1 FY26. The presentation does not state the nature of the exceptional item behind the difference.
Which Amrutanjan businesses drove H1 FY27 sales growth?
Amrutanjan’s Women’s Hygiene & Personal Care business was its fastest-growing reported segment, with H1 FY27 sales up 25.17% to Rs 76.84 crore from Rs 61.39 crore. Women’s Hygiene sales rose 19.81% to Rs 73.55 crore, while over-the-counter, or OTC, sales increased 8.18% to Rs 148.20 crore. The hygiene and personal-care business added Rs 15.45 crore of sales year on year.
Amrutanjan’s beverages sales declined to Rs 11.66 crore in H1 FY27 from Rs 12.05 crore in H1 FY26, unlike OTC and Women’s Hygiene & Personal Care. Hydration drinks, which are included in beverages, grew 1.21% to Rs 10.91 crore from Rs 10.78 crore. That Rs 0.13 crore gain did not offset the Rs 0.39 crore decline in total beverages sales.
Why did Amrutanjan’s half-year profit not match sales growth?
Amrutanjan said that a majority of raw-material and packing-material prices were higher in H1 FY27 than in H1 FY26, including menthol crystal prices. Employee benefit expenses rose 11.45% to Rs 35.62 crore, advertisement and selling expenses increased 6.34% to Rs 22.46 crore, and other expenses climbed 32.17% to Rs 35.21 crore. Other expenses had the largest percentage increase among these disclosed categories.
Amrutanjan’s stated H1 FY27 advertisement spend was Rs 12.76 crore, compared with Rs 10.63 crore in H1 FY26, while Comfy advertising increased to Rs 5.54 crore from Rs 2.71 crore. In beverages, advertisement spend fell to Rs 0.56 crore from Rs 2.36 crore. The higher Comfy spend occurred alongside the Rs 15.45 crore increase in Women’s Hygiene & Personal Care sales.
Got a follow-up? Ask IRIS
How did Amrutanjan’s second quarter compare with the half year?
Amrutanjan’s Q2 FY27 performance was ahead of the aggregate H1 trend, with net sales rising 14.85% to Rs 135.18 crore and profit after tax increasing 23.78% to Rs 17.28 crore. In Q2 FY26, net sales were Rs 117.70 crore and profit after tax was Rs 13.96 crore. Quarterly profit growth therefore contrasted with the Rs 0.62 crore decline in H1 profit after tax.
Amrutanjan reported Q2 FY27 profit before tax of Rs 23.10 crore, up 20.25% from Rs 19.21 crore in Q2 FY26. Management said operating margin expanded by 200 basis points, despite cost-of-goods-sold inflation, because of operating leverage. It also said the sanitary-napkin production asset became fully operational in Q2, with average gross margin at 41% against historical averages of 30% to 32% and September reaching its 50% target.
What is Amrutanjan management’s FY27 outlook?
Amrutanjan management guided for FY27 revenue growth of 12% to 15% and projected a 200-basis-point decline in enterprise-level gross margin. It cited packaging-material inflation, with plastic prices at 1.5 times last-year levels, and a 20% rise in pulp prices for sanitary pads. Management said price increases had mitigated the impact of these costs to a large extent.
Management’s stated goal is to sustain a 12% operating profit margin, which it said Amrutanjan achieved last year. It also said Comfy had reached household penetration of 1.4 crore homes, citing Nielsen and Kantar. For pain management, management said Rubs and Balms continued to record negative consumer-level growth, although the rate of decline reduced in Q2 compared with Q1.
Conclusion
Amrutanjan’s H1 FY27 result combined Rs 26.40 crore of additional sales with a Rs 0.62 crore decline in profit after tax. Women’s Hygiene & Personal Care was the principal reported growth engine, rising 25.17%, while higher material costs, employee costs and other expenses limited the translation of revenue growth into half-year profit.
The next results will test management’s 12% to 15% FY27 revenue-growth guidance and its goal of sustaining a 12% operating profit margin. Management has also projected a 200-basis-point decline in enterprise-level gross margin, making the continuation of Q2’s 41% average gross margin and the effect of higher plastic and pulp prices relevant measures to watch.