










Anlon reiterates Rs 380-400 crore FY27 target as H1 tops FY26
Key highlights
- Anlon reported Rs 193.17 crore of consolidated revenue in H1 FY27, up 125.9% from Rs 85.5 crore in H1 FY26.
- Q2 FY27 EBITDA margin rose to 23.9% from 17.8% in Q1 FY27 after customer price revisions.
- Management reiterated FY27 revenue guidance of Rs 380 crore to Rs 400 crore.
- Net operating cash used narrowed to Rs 7.94 crore in H1 FY27 from Rs 79.44 crore in FY26.
powered by IRIS
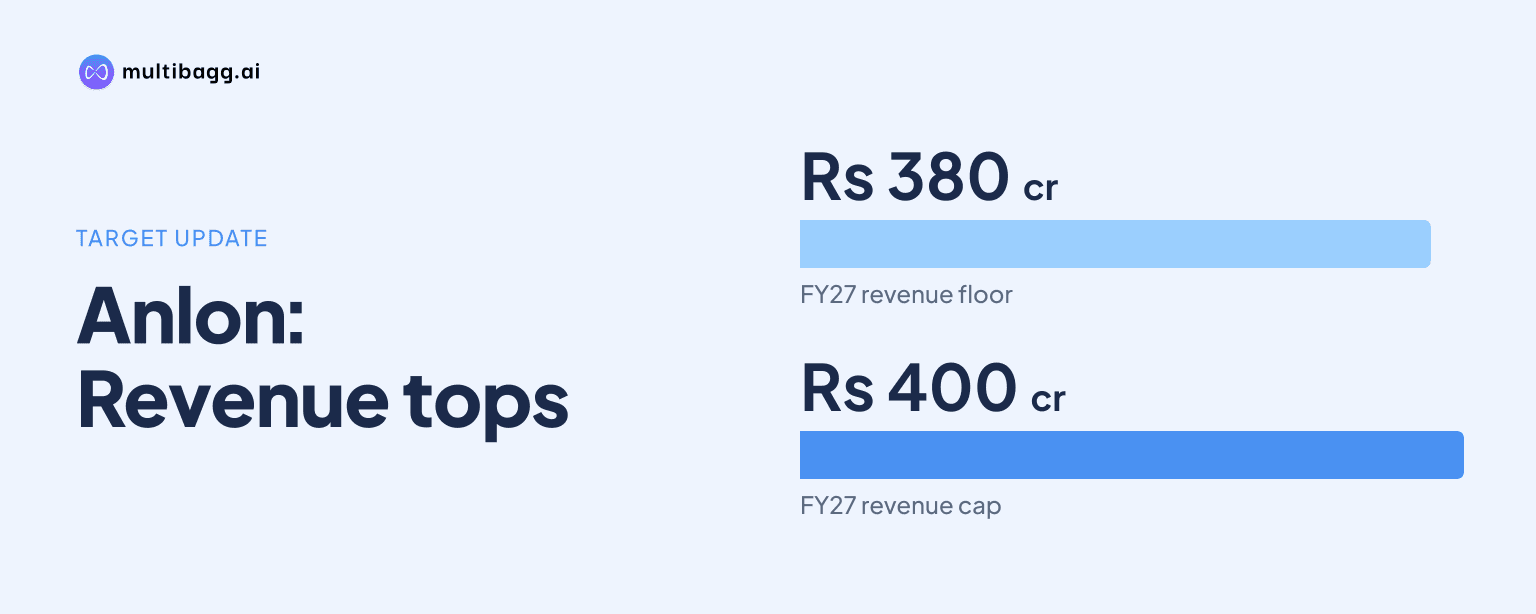
Anlon Healthcare Limited reported consolidated revenue of Rs 193.17 crore in H1 FY27, exceeding its revenue for the whole of FY26, and management reiterated its Rs 380 crore to Rs 400 crore FY27 target. Q2 FY27 EBITDA margin recovered to 23.9% from 17.8% in Q1 after customer price revisions.
Know Anlon Healthcare inside out
Results, valuation, peers and who's buying, in one view.
What did Anlon report for H1 FY27?
Anlon reported consolidated revenue from operations of Rs 193.17 crore for the half year ended September 2026, compared with Rs 85.5 crore in H1 FY26, an increase of 125.9%. EBITDA, or earnings before interest, tax, depreciation and amortisation, rose 104.7% to Rs 40.83 crore, while profit after tax increased 97.9% to Rs 25.46 crore.
Anlon said its H1 FY27 revenue had already surpassed revenue for all of FY26, although it did not disclose the FY26 revenue figure on the call. Q2 FY27 contributed Rs 105.61 crore of revenue, versus Rs 52.2 crore in Q2 FY26, while Q2 EBITDA increased 84.1% to Rs 25.24 crore from Rs 13.71 crore.
How did Anlon’s EBITDA margin recover in Q2 FY27?
Anlon’s Q2 FY27 EBITDA margin recovered to 23.9% from 17.8% in Q1 FY27, an improvement of more than 600 basis points sequentially. Management attributed the recovery mainly to price increases passed through to customers, rather than to a reduction in raw-material costs.
Management said crude-linked petrochemical solvents and other raw-material prices remained around the higher levels reached after the geopolitical disruption it cited in March. Q2 EBITDA increased 61.9% quarter on quarter, compared with revenue growth of 20.6%, which management said reflected operating leverage as revised pricing flowed into contracts.
For H1 FY27, Anlon’s EBITDA margin was 21.1%, below the Q2 level because of the lower first-quarter margin. Management had previously indicated a 25% to 30% range for Q2 and Q3 FY27, but said on the call that it expected a sustainable range of 25% to 27%, while current conditions supported a 23% to 24% level.
Can Anlon meet its Rs 380-400 crore FY27 target?
Anlon management reiterated its FY27 revenue expectation of Rs 380 crore to Rs 400 crore and said the company was almost in line with that target. With Rs 193.17 crore reported in H1 FY27, revenue of Rs 186.83 crore to Rs 206.83 crore in the second half would be required to reach management’s stated range.
Management also gave an FY28 revenue expectation of Rs 650 crore to Rs 700 crore, based on projects and expansion activity. It said the FY27 and FY28 ranges exclude revenue from the contract development and manufacturing organisation, or CDMO, business because commercialisation depends on customer requirements, market acceptance and other variables.
One CDMO molecule had completed validation quantities but its first commercial supply was delayed by one or two months, according to management. Anlon expected the first commercial segment by the end of the final month of Q3 FY27 or in the first month of Q4 FY27, while it expected the other two molecules to commercialise after H1 FY28.
Got a follow-up? Ask IRIS
Which businesses and capacity additions support Anlon’s plan?
Anlon’s stand-alone business contributed 44.6% of consolidated revenue during H1 FY27, Apiqo Organics contributed 43.7%, and Bizotic Lifescience contributed 11.7%. Within Anlon’s stand-alone portfolio, intermediates represented 81.1% of revenue, active pharmaceutical ingredients, or APIs, represented 17.1%, and nutraceutical and other products made up the balance.
The group’s installed manufacturing capacity was approximately 1,900 to 2,000 metric tonnes per annum, compared with 400 metric tonnes per annum at the Anlon parent facility. A Rajkot greenfield project is planned to add about 1,200 metric tonnes per annum through eight clean lines in Q1 FY28, allowing eight APIs to operate simultaneously, while a further 500 metric tonnes per annum of group expansion is planned.
Anlon has filed 21 drug master files, or DMFs, with global authorities and expects five to seven products to commercialise in FY27. Management said four products were already commercialised and validated, three filings were planned by December, and the remainder by February and March, alongside a target for three to five additional DMF filings in FY27.
What could affect Anlon’s FY27 execution?
The Rajkot project was on track for Q1 FY28 completion, with construction started and equipment installation planned after the first floor was completed by end-November, management said. A public hearing scheduled for December could cause a one- or two-month delay if regulatory procedures are postponed, and management expects revenue from the added capacity from Q2 FY28.
The expansion has planned capital expenditure of Rs 130 crore, of which Anlon said about Rs 15 crore to Rs 20 crore had been spent or committed at the initial stage. Separately, net cash used in operating activities narrowed to Rs 7.94 crore in H1 FY27 from Rs 79.44 crore in FY26, helped by collection of receivables and shorter customer credit terms.
Management said customer credit terms had been reduced to 90 to 100 days from 130 to 140 days, while a normal working-capital cycle for its current manufacturing operations was 170 to 180 days. It reiterated an objective of delivering positive operating cash flow by the end of FY27, which depends on collections and second-half execution.
Conclusion
Anlon’s H1 FY27 revenue of Rs 193.17 crore exceeded its full-year FY26 revenue, while EBITDA of Rs 40.83 crore and profit after tax of Rs 25.46 crore both more than doubled from H1 FY26. The principal operating change in Q2 was the EBITDA margin recovery to 23.9%, driven mainly by price pass-through despite elevated raw-material costs.
The next disclosed markers are delivery of the Rs 380 crore to Rs 400 crore FY27 revenue target, progress toward management’s 25% to 27% sustainable EBITDA-margin range, and the December public hearing for the 1,200-metric-tonne Rajkot expansion. Management also expects the delayed first CDMO commercial supply around late Q3 FY27 or early Q4 FY27 and is targeting positive operating cash flow by FY27-end.