










Anlon Healthcare Limited Delays CDMO Supply, Excludes FY28 Upside
Key highlights
- Anlon Healthcare expects its first CDMO commercial shipment in late Q3 FY27 or early Q4 FY27, a delay of one to two months.
- Management said the Rs 650 crore to Rs 700 crore FY28 revenue outlook currently excludes CDMO value addition.
- The second and third CDMO molecules are validated at Anlon Healthcare’s end, with commercialisation expected after H1 FY28.
- Anlon Healthcare reported Q2 FY27 revenue of Rs 105.61 crore and a 23.9% EBITDA margin.
powered by IRIS
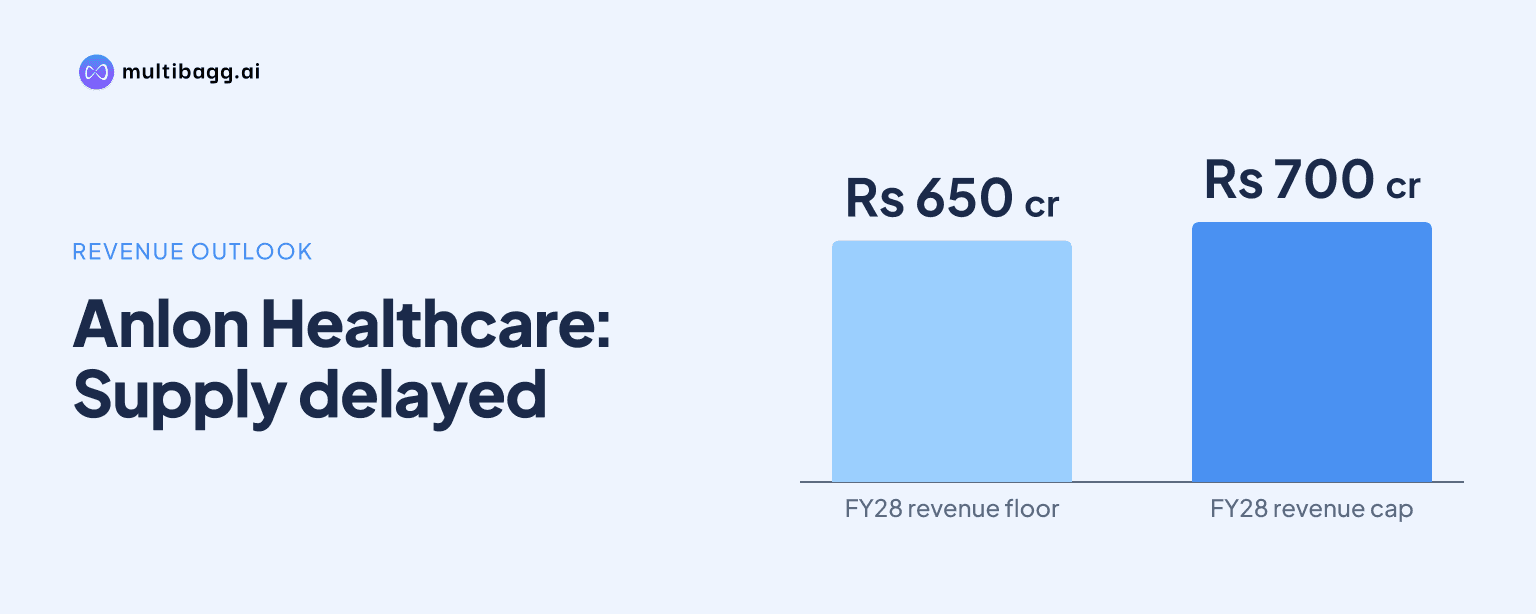
On November 3, 2026, Anlon Healthcare Limited said its first commercial contract development and manufacturing organisation supply would move to late Q3 FY27 or early Q4 FY27, while its Rs 650 crore to Rs 700 crore FY28 revenue forecast excludes CDMO value addition because the revenue ramp remains uncertain.
Know Anlon Healthcare inside out
Results, valuation, peers and who's buying, in one view.
When will Anlon Healthcare begin its first CDMO commercial supply?
Anlon Healthcare now expects the first commercial CDMO supply in the last month of Q3 FY27 or the first month of Q4 FY27. On the November 3, 2026 earnings call, management said it had received the commercial quantity and details from the customer, but the planned supply was delayed by one or two months. This revises the earlier target of commercial supplies from Q3 FY27 after validation quantities for the first molecule had already been supplied.
The change concerns Anlon Healthcare’s initial commercial step in a programme involving three molecules for two global innovator companies. Management said CDMO projects typically require a minimum of three to four years from development to commercial revenue. The company has validated the first product, but said the customer will need to assess market response and patient acceptance after its end product is sold before the CDMO contribution becomes clearer.
Is CDMO revenue included in Anlon Healthcare’s FY28 forecast?
No, management said Anlon Healthcare is not currently considering CDMO value addition in either its Rs 380 crore to Rs 400 crore FY27 revenue expectation or its Rs 650 crore to Rs 700 crore FY28 expectation. Management described those forecasts as based on the existing business and customer commitments it considers certain, rather than on CDMO commercialisation that depends on multiple external and market-acceptance parameters.
That treatment separates the published FY28 outlook from the uncertain timing and scale of the CDMO ramp. Management nevertheless said it expects one molecule to make a significant revenue contribution in Q4 FY28 if the programme progresses as anticipated. It did not quantify that potential contribution and said it would be able to comment further on the other two molecules only after their validation quantities are submitted and commercialisation timing becomes clearer.
The forecast methodology means a first shipment in late Q3 FY27 or early Q4 FY27 would not necessarily become a material near-term revenue stream. Management said customer sales, patient response and product acceptability can take one to three years to develop. Anlon Healthcare therefore positioned CDMO as potential additional revenue rather than as a component supporting the Rs 650 crore to Rs 700 crore FY28 target.
What has changed for Anlon Healthcare’s other CDMO molecules?
Anlon Healthcare said validation for the second and third CDMO molecules has been completed at its end, but commercialisation is now expected after H1 FY28. Management said it is ready to submit material to the customer, while the remaining commercialisation process will take at least six to eight months. This is later than the prior indication of commercialisation between Q4 FY27 and Q1 FY28.
The company did not disclose molecule names, anticipated volumes, contract values or customer identities for the three-molecule programme. It said the first molecule has moved beyond validation-quantity supply, whereas the other two remain subject to customer-side progress after Anlon Healthcare’s validation work. The commercial timeline is therefore differentiated: the first supply is expected around the Q3 FY27 to Q4 FY27 transition, while the other two are expected only after the first half of FY28.
The delayed timelines do not alter Anlon Healthcare’s stated FY28 revenue range because management says that range excludes CDMO. They do, however, set the milestones management identified for evaluating the programme: first commercial supply for molecule one, customer submission for molecules two and three, and a later indication of how quickly these products are commercialised. Management’s Q4 FY28 expectation for one significant contributor remains an expectation rather than quantified guidance.
Got a follow-up? Ask IRIS
What will support Anlon Healthcare’s FY28 revenue target without CDMO?
Anlon Healthcare’s Rs 650 crore to Rs 700 crore FY28 expectation is tied to its existing operations, expansion projects and committed customer business rather than CDMO. For FY27, management reiterated a Rs 380 crore to Rs 400 crore revenue expectation after reporting Rs 193.17 crore of revenue from operations in H1 FY27, compared with Rs 85.50 crore in H1 FY26. Management said H1 FY27 revenue had already exceeded the company’s full-year FY26 revenue.
The main capacity project is the Rajkot greenfield expansion, which is intended to add about 1,200 metric tonnes per annum through eight clean lines in Q1 FY28. Management said the expansion would enable eight active pharmaceutical ingredients, or APIs, to be run simultaneously, with revenue expected from Q2 FY28. Group installed capacity was about 1,900 to 2,000 metric tonnes per annum, while a further 500 metric tonnes per annum of expansion was planned across the group.
The project remained on track at the call date, but management identified a regulatory dependency. Construction had started, with completion of the first floor expected by the end of November 2026 and parallel equipment installation planned. A public hearing was due in December 2026; management said a delay or postponement by the regulatory agency could postpone the expansion by one or two months. Anlon Healthcare had spent about Rs 15 crore to Rs 20 crore of the Rs 130 crore expansion capital expenditure at that point.
How are revenue growth and margins tracking before the CDMO ramp?
Anlon Healthcare reported consolidated Q2 FY27 revenue from operations of Rs 105.61 crore, up 102.3% from Rs 52.20 crore in Q2 FY26. Quarterly earnings before interest, tax, depreciation and amortisation, or EBITDA, rose 84.1% to Rs 25.24 crore, while profit after tax increased 84.4% to Rs 17.18 crore. The quarter’s EBITDA margin was 23.9%, recovering from 17.8% in Q1 FY27.
For H1 FY27, revenue rose 125.9% to Rs 193.17 crore and EBITDA increased 104.7% to Rs 40.83 crore, producing an EBITDA margin of 21.1%. Management attributed the Q2 margin recovery mainly to finished-goods price increases passed to customers, rather than lower raw-material prices. It said raw-material costs had not normalised after increases in crude and petrochemical solvents, and projected a 25% to 26% EBITDA margin for full-year FY27 based on projections and orders in hand.
Capacity utilisation also shows why the Rajkot schedule is relevant to the FY28 outlook. Consolidated utilisation was about 65% to 67%, but Anlon Healthcare’s stand-alone facility was operating at 85% to 86%, which management described as optimum capacity. Within the stand-alone portfolio during the half year, intermediates contributed 81.1% of revenue and APIs contributed 17.1%, with nutraceutical and other products accounting for the balance.
Conclusion
The first CDMO commercial supply has moved from the initial Q3 FY27 target to late Q3 FY27 or early Q4 FY27, and the two subsequent molecules now have a post-H1 FY28 commercialisation expectation. Anlon Healthcare’s stated Rs 650 crore to Rs 700 crore FY28 forecast is therefore based on existing operations, capacity expansion and committed customer business rather than uncertain CDMO revenue, while management sees scope for one molecule to contribute significantly in Q4 FY28.
The next disclosed milestones are the December 2026 public hearing for the Rajkot project, targeted Q1 FY28 completion of its 1,200-metric-tonne annual capacity addition and revenue from that expansion from Q2 FY28. For CDMO, the items to watch are the first commercial shipment around the Q3 FY27 to Q4 FY27 transition, submission of the other two validated products to customers, and management’s later assessment of their commercialisation progress.