










Antony Waste Posts Q2 Loss as EBITDA Margin Falls to 17.6%
Key highlights
- Antony Waste reported a Rs 1.7 crore PAT loss in Q2FY27, compared with a Rs 17.3 crore profit in Q2FY26.
- Total operating revenue rose 25% year on year to Rs 321.2 crore in Q2FY27.
- EBITDA margin declined to 17.6% in Q2FY27 from 21.6% a year earlier.
- Antony Waste recognised a Rs 20 crore exceptional item related to the July 2026 PCMC facility incident.
powered by IRIS
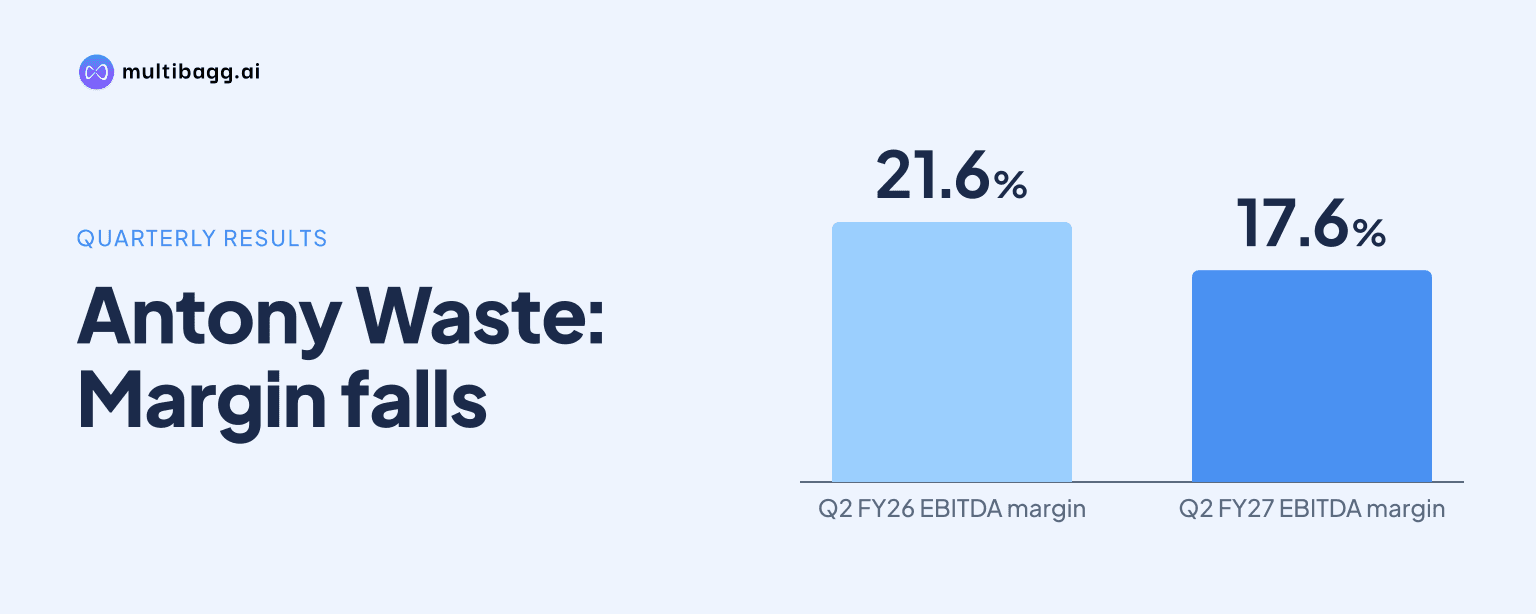
Antony Waste Handling Cell Limited reported a consolidated Rs 1.7 crore loss in Q2FY27 despite 25% year-on-year growth in total operating revenue to Rs 321.2 crore, as earnings before interest, tax, depreciation and amortisation (EBITDA) margin fell to 17.6% from 21.6%. Antony Waste cited expected credit loss provisioning on approved escalation claims as a factor limiting margin growth.
Know Antony Waste Handling Cell inside out
Results, valuation, peers and who's buying, in one view.
How did Antony Waste perform in Q2FY27?
Antony Waste recorded a consolidated profit after tax (PAT) loss of Rs 1.7 crore in Q2FY27, compared with PAT of Rs 17.3 crore in Q2FY26. Its PAT margin moved to negative 0.5% from positive 6.5% a year earlier, while revenue from operations increased 25% to Rs 330.3 crore from Rs 264.1 crore.
EBITDA increased 2% year on year to Rs 58.3 crore from Rs 57.1 crore, which was slower than the 25% increase in total operating revenue. EBITDA margin declined by 4 percentage points to 17.6% in Q2FY27 from 21.6% in Q2FY26, while the operating-revenue base increased by Rs 63.5 crore.
What drove Antony Waste's Q2FY27 revenue growth?
Antony Waste's municipal solid waste collection and transportation (C&T) revenue rose 42% year on year to Rs 227.5 crore in Q2FY27 from Rs 160.5 crore. Management attributed the increase to the ramp-up of newly commenced Mumbai operations awarded by Brihanmumbai Municipal Corporation, higher volumes at existing projects and recognition of cost escalations under contracted terms.
Other operating income grew 78% to Rs 44.7 crore from Rs 25.1 crore, while municipal solid waste processing revenue declined 32% to Rs 49 crore from Rs 72.1 crore. The Rs 63.5 crore increase in total operating revenue therefore reflected higher C&T revenue and other operating income, partly offset by a Rs 23.1 crore decline in processing revenue.
For H1FY27, total operating revenue was Rs 582.2 crore, up 15% from Rs 505 crore in H1FY26. C&T revenue rose 26% to Rs 393.8 crore, processing revenue fell 14% to Rs 123.7 crore, and other operating income increased 32% to Rs 64.7 crore.
Why did Antony Waste's EBITDA margin decline?
Antony Waste said Q2FY27 revenue included certain past escalation claims approved by a client during the quarter, but it recognised an expected credit loss (ECL) provision against the resulting receivables. The provision was made under Indian Accounting Standard 109 and applicable audit requirements, which management said meant margins rose less than they otherwise would have after the revenue recognition.
Management said the ECL provisions are expected to be written back as receivables are realised from the client. It also said EBITDA growth and margin expansion would have been higher excluding the provision, but did not disclose the provision amount or an adjusted EBITDA figure for Q2FY27.
The decline was also evident in H1FY27, when EBITDA fell 13% to Rs 103.3 crore from Rs 119.3 crore despite a 15% rise in operating revenue. H1FY27 EBITDA margin was 17.2%, compared with 23.0% in H1FY26, while PAT changed to a Rs 1 crore loss from a Rs 40.2 crore profit.
Got a follow-up? Ask IRIS
How did Antony Waste's waste volumes change in Q2FY27?
Antony Waste handled about 1.28 million tonnes of municipal solid waste in Q2FY27, an increase of about 0.8% year on year. C&T volumes grew about 11.5% to about 0.60 million tonnes, while processing volumes declined about 7.2% to about 0.68 million tonnes.
Antony Waste sold about 49,000 tonnes of refuse-derived fuel and about 2,000 tonnes of compost during Q2FY27. The difference between growing C&T volumes and lower processing volumes coincided with C&T revenue increasing 42% and processing revenue declining 32%, although the release gives no segment-level profitability or pricing data.
In H1FY27, total municipal solid waste handled increased about 4.5% to about 2.71 million tonnes. C&T volume rose about 9.4% to about 1.16 million tonnes, processing volume was stable at 1.54 million tonnes, refuse-derived fuel sales were about 89,000 tonnes and compost sales were about 8,000 tonnes.
What was the impact of the PCMC waste-to-energy incident?
Antony Waste said an incident at its PCMC waste-to-energy facility in July 2026 disrupted operations, leaving energy operations suspended during Q2FY27. It recognised a Rs 20 crore exceptional item related to the incident, comprising impairment of property, plant and equipment, restoration and other related costs, and compensation paid to employees or their next of kin.
While energy operations remained suspended, material recovery facility and composting operations resumed and processed about 33,600 tonnes of waste. Restoration and recommissioning are underway with PCMC, relevant authorities and original equipment manufacturer partners, and management said the facility is expected to be functional by December 2026.
Management said its priorities include restoring the facility, improving operating efficiencies and continuing the Mumbai C&T ramp-up. It also cited traction in construction and demolition processing, existing projects, an order book and a project pipeline, but did not disclose their values or expected FY27 financial contribution.
Conclusion
Antony Waste's Q2FY27 result combined 25% growth in total operating revenue with a move to a Rs 1.7 crore loss, as EBITDA increased only 2% and margin declined to 17.6%. C&T growth from Mumbai operations, higher volumes and recognised escalations offset the fall in processing revenue, but ECL provisioning and the Rs 20 crore exceptional item coincided with lower earnings.
The next disclosed milestone is management's expectation that the PCMC waste-to-energy facility will be functional by December 2026. Antony Waste also expects ECL provisions to be written back as client receivables are realised, while Mumbai C&T operations continue to ramp up.