










Aptus 30-Plus-Day Delinquency Reaches 7.08% in Q2 FY27
Key highlights
- Aptus reported 30+ DPD of 7.08% in Q2 FY27, up from 6.87% in Q1 FY27.
- Aptus’s gross Stage 2 loans were Rs 699.9 crore, or 5.4% of the portfolio, at 30 September 2026.
- Aptus’s gross NPA ratio eased to 1.68% in Q2 FY27 from 1.70% in Q1 FY27.
- Aptus’s consolidated profit after tax rose 18% year on year to Rs 267 crore in Q2 FY27.
powered by IRIS
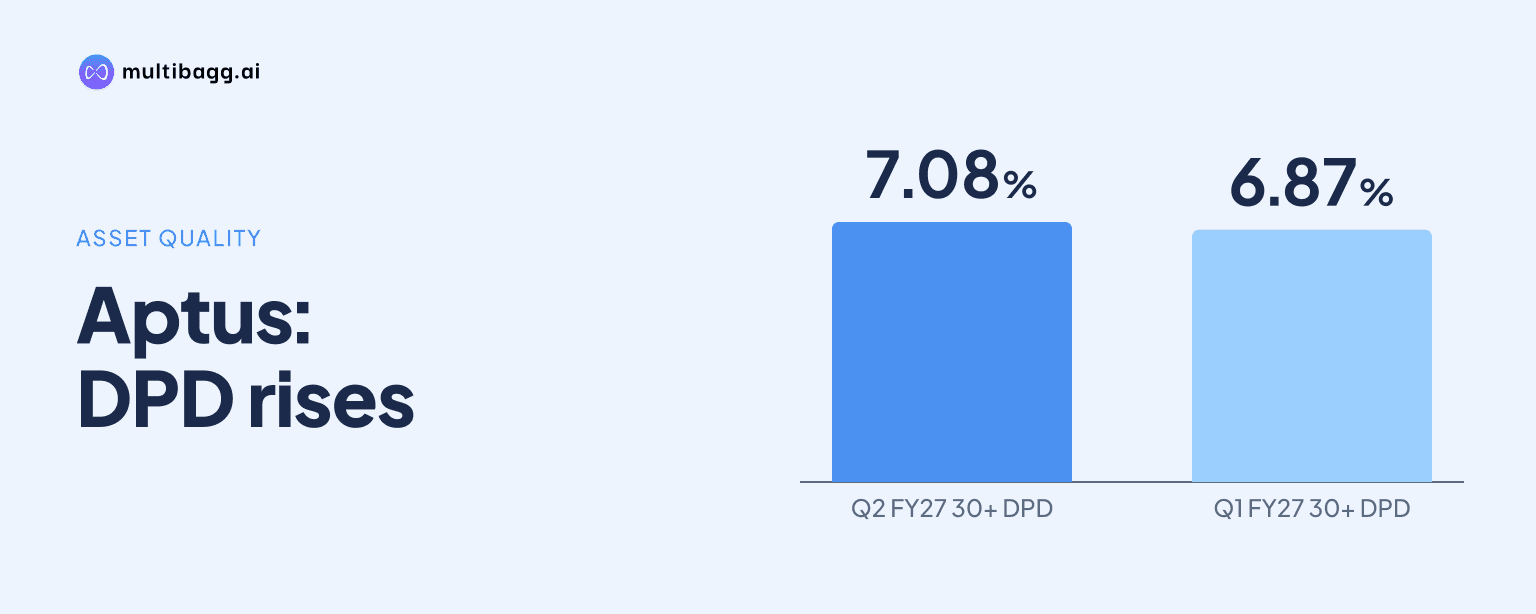
Aptus Value Housing Finance reported a 7.08% 30-plus-days-past-due rate in Q2 FY27, up from 6.87% in Q1 FY27, while gross Stage 2 loans reached 5.4% of its Rs 12,966.7 crore consolidated loan book on 30 September 2026; gross non-performing assets eased to 1.68% from 1.70%.
Know Aptus Value Housing Finance India inside out
Results, valuation, peers and who's buying, in one view.
What changed in Aptus’s delinquency measures in Q2 FY27?
Aptus’s earlier-stage repayment stress increased in Q2 FY27, as the 30-plus-days-past-due, or 30+ DPD, ratio rose by 0.21 percentage points sequentially to 7.08%. The ratio was also above 6.34% in Q2 FY26 and 6.21% in Q4 FY26, after increasing to 6.87% in Q1 FY27. Gross non-performing assets, or gross NPA, were reported separately at 1.68% in Q2 FY27.
Aptus’s gross NPA ratio declined by 0.02 percentage points from Q1 FY27, while net NPA declined by the same amount to 1.27%. Both measures nevertheless remained above their Q2 FY26 levels of 1.55% and 1.17%, respectively. The sequential decline in the NPA ratios alongside the higher 30+ DPD ratio shows that the reported movement was in the earlier overdue measure rather than the reported NPA ratios.
How did Aptus’s Stage 2 loans change?
Aptus’s gross Stage 2 loans rose to Rs 699.9 crore as of 30 September 2026, representing 5.4% of the portfolio, from Rs 656.5 crore, or 5.2%, on 30 June 2026. At 30 September 2025, gross Stage 2 loans were Rs 546.6 crore and represented 4.8% of the portfolio. The Stage 2 share therefore rose by 0.2 percentage points quarter on quarter and 0.6 percentage points year on year.
The net Stage 2 balance was Rs 649.2 crore at 30 September 2026, compared with Rs 608.1 crore on 30 June 2026 and Rs 505.4 crore a year earlier. Expected credit loss, or ECL, provision against Stage 2 was Rs 50.7 crore, versus Rs 48.5 crore in the preceding quarter and Rs 41.2 crore a year earlier. Its provision coverage ratio, or PCR, was 7.24%, compared with 7.38% in June 2026 and 7.54% in September 2025.
What does Aptus’s Stage 3 data show?
Aptus reported gross Stage 3 loans of Rs 217.8 crore at 30 September 2026, or 1.7% of the portfolio, compared with Rs 215.3 crore and 1.7% three months earlier. The Stage 3 amount was Rs 176.9 crore, or 1.5%, at 30 September 2025. The Stage 3 portfolio share was unchanged sequentially but 0.2 percentage points higher year on year, while the quarterly gross NPA ratio eased to 1.68% from 1.70%.
ECL provision on Stage 3 was Rs 54.5 crore at the September 2026 reporting date, against Rs 53.8 crore in June 2026 and Rs 44.2 crore in September 2025. PCR on this portfolio was 25.00% at each of the three disclosed dates. Net Stage 3 was Rs 163.4 crore at 30 September 2026, compared with Rs 161.5 crore in the prior quarter and Rs 132.7 crore a year earlier.
Got a follow-up? Ask IRIS
Did Aptus’s collections improve as overdue loans rose?
Aptus’s collection efficiency fell to 98.35% in Q2 FY27 from 98.52% in Q1 FY27 and 99.36% in Q2 FY26. The ratio was 100.50% in Q4 FY26 before declining in each of the following two quarters shown in the presentation. This movement coincided with the rise in 30+ DPD from 6.21% in Q4 FY26 to 7.08% in Q2 FY27.
Aptus reported total ECL provision of Rs 133.7 crore at 30 September 2026, compared with Rs 130.2 crore at 30 June 2026 and Rs 117.5 crore a year earlier. Total PCR was 1.0% at all three reporting dates. Gross Stage 1 loans stood at Rs 12,049 crore and formed 92.9% of the portfolio at 30 September 2026, versus 93.1% in June 2026 and 93.7% a year earlier.
How did Aptus’s growth and profit compare with asset quality?
Aptus’s consolidated assets under management, or AUM, were Rs 14,177 crore in Q2 FY27, up 20% from Rs 11,767 crore in Q2 FY26. Quarterly disbursements also increased 20% to Rs 1,153 crore from Rs 963 crore. Over the same year-on-year comparison, gross NPA increased by 0.13 percentage points to 1.68%, while 30+ DPD increased by 0.74 percentage points to 7.08%.
Consolidated profit after tax rose 18% year on year to Rs 267 crore in Q2 FY27 from Rs 227 crore. Credit cost was Rs 24 crore in the quarter, compared with Rs 18 crore in Q2 FY26, while net income margin increased to Rs 463 crore from Rs 389 crore. The loan book disclosed for ECL measurement was Rs 12,966.7 crore at 30 September 2026, versus Rs 12,690.8 crore at 30 June 2026 and Rs 11,412.6 crore at 30 September 2025.
Conclusion
Aptus’s Q2 FY27 data show divergent asset-quality measures: gross and net NPA ratios were modestly lower than in Q1 FY27, but 30+ DPD, Stage 2 exposure and the Stage 2 portfolio share increased. Collection efficiency fell to 98.35%, while consolidated AUM and quarterly profit after tax rose 20% and 18%, respectively, from Q2 FY26.
The unresolved issue for the next reported period is whether the rise in earlier overdue loans is contained or extends further through the portfolio. The disclosed measures to watch are the 7.08% 30+ DPD ratio, the 5.4% Stage 2 share, collection efficiency of 98.35%, and the Stage 3 portfolio share of 1.7%.