










Ardee Industries Limited prioritises volume over EBITDA recovery
Key highlights
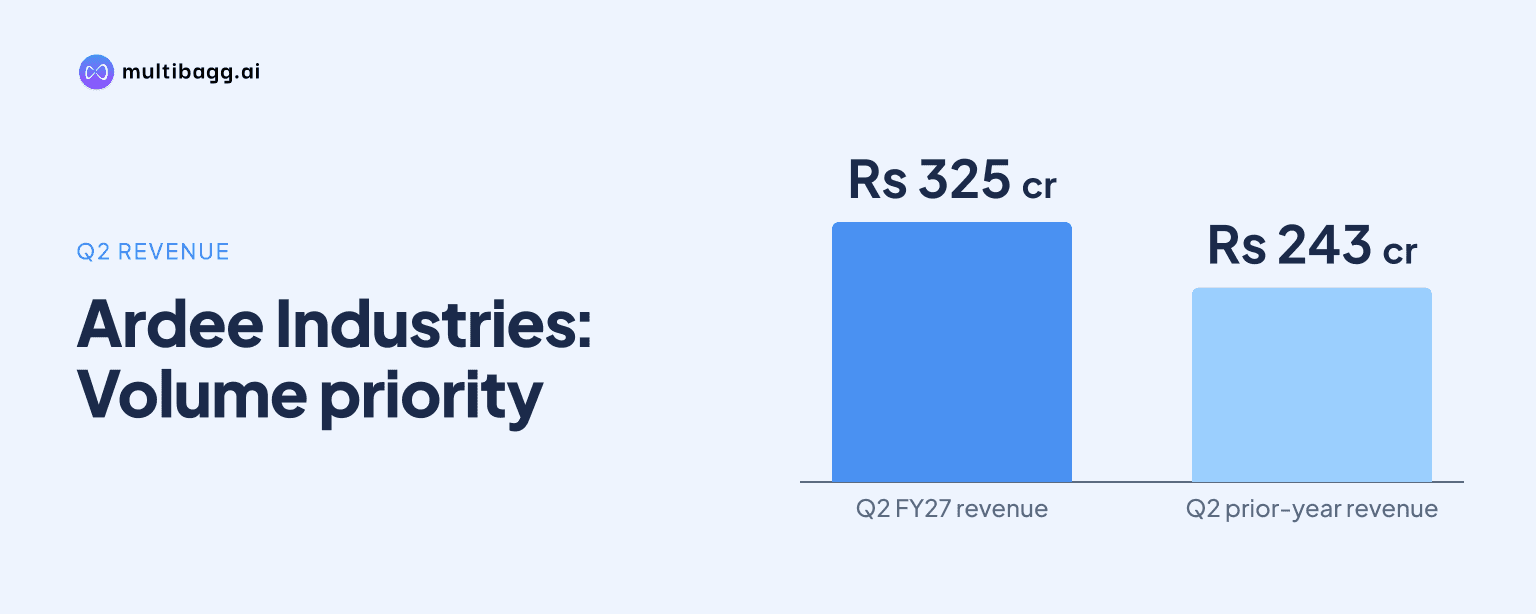
- Ardee Industries reported Q2 FY27 revenue of Rs 325 crore, up 33.5% year on year from Rs 243 crore.
- Management expects FY27 EBITDA per tonne to remain near Q2 FY27's Rs 18,000 level.
- Ardee Industries maintained its FY27 sales-volume growth target of 10% to 15% after H1 volume of about 33,300 metric tonnes.
- Domestic raw-material procurement increased to about 27% to 28% from around 15% last year.
powered by IRIS
Ardee Industries expects earnings before interest, tax, depreciation and amortisation (EBITDA) per tonne to remain near Rs 18,000 in Q2 FY27, while maintaining its 10% to 15% full-year volume-growth target despite higher imported-scrap, freight and fuel costs.
Know Ardee Industries inside out
Results, valuation, peers and who's buying, in one view.
Why is Ardee Industries keeping EBITDA per tonne near Rs 18,000?
Ardee Industries is keeping EBITDA per tonne near current levels because costlier raw material procured in the preceding three to four months is still entering production. Management said imported material generally takes two to three months to arrive and be processed, meaning higher procurement prices continue to affect Q2 FY27 profitability.
The pressure comes from higher raw-material costs and operating expenditure, particularly fuel costs for machinery. Management said freight has increased the landed cost of imported scrap, while domestic sourcing, although useful for reducing supply uncertainty, can sometimes cost more than imports. It therefore told investors that its FY27 guidance is to maintain similar EBITDA-per-tonne levels rather than forecast a near-term recovery.
Q2 FY27 EBITDA per tonne of about Rs 18,000 was below about Rs 19,000 in the preceding quarter, according to an analyst on the call. Management said last year's average EBITDA margin was around 12%, and that the 19.4% year-on-year margin comparison raised by the analyst was not the most relevant reference point because earlier material had been purchased before costs increased.
Management reported Q2 FY27 EBITDA of Rs 29 crore on revenue of Rs 325 crore, equating to an EBITDA margin of 8.9%. That compares with Q2 FY26 revenue of Rs 243 crore, while Q2 FY27 revenue rose 33.5% year on year as volume and sales realisation increased.
Can Ardee Industries meet its FY27 volume-growth target?
Ardee Industries is maintaining its 10% to 15% FY27 sales-volume growth target after reporting about 33,300 metric tonnes in the first half, or H1, of FY27. Management said it expects to achieve that target in the second half and answered yes when asked whether the outlook reflected a supportive demand environment.
Q2 FY27 sales volume was 15,656 metric tonnes, and the company said quarterly revenue growth was supported by higher volumes and better sales realisation. However, the higher realisation was insufficient to offset the impact of increased scrap, freight and fuel costs on profitability per tonne.
Installed capacity has increased by about 50% to 1,56,950 metric tonnes per annum from 1,04,025 metric tonnes per annum through debottlenecking. Management said its objective is to reach an optimal utilisation range of 70% to 75%, rather than requiring nearly 100% utilisation of the earlier capacity to support growth.
The expanded capacity did not contribute to Q2 FY27 volume, management said. It expects the debottlenecking to play a larger role next year, although it said FY27's 10% to 15% growth can be delivered through the existing facility and partly through the additional capacity created at the brownfield site.
Got a follow-up? Ask IRIS
How is Ardee Industries changing raw-material sourcing?
Ardee Industries is widening both import and domestic procurement channels to improve raw-material availability, even though this does not immediately reduce costs. The company has expanded its import-source base to more than 80 countries from more than 50 countries last year, as it seeks to reduce dependence on a narrower supplier pool.
Domestic procurement has risen to about 27% to 28% of raw-material purchases from around 15% last year. Ardee Industries has started participating in battery-scrap auctions conducted by tower companies and domestic corporates, but management said domestic material can sometimes be more expensive than imported material.
Management expects extended producer responsibility (EPR) rules and taxation changes to formalise the domestic battery-scrap market over the next three to four years. It said the regulatory shift will be gradual because of the informal sector, rather than producing an immediate increase in domestic scrap availability during FY27.
This sourcing approach explains management's preference for absolute growth over margin protection. A broader supply base may support production volumes when material availability improves, but management said raw-material prices have not yet fallen and costly earlier imports remain in the operating cycle.
Can exports and alloys improve Ardee Industries' realisation?
Ardee Industries is pursuing specialised lead alloys and broader export markets to improve product mix and realisation, subject to customer approval and original equipment manufacturer validation. Its products include high-purity lead and customised lead alloys for automotive, renewable-energy, telecommunications, inverter, uninterruptible power supply and industrial uses.
Exports contributed about 37% of H1 FY27 revenue, or Rs 244 crore out of total H1 revenue of Rs 664 crore. Ardee Industries exports to eight countries, and management said empanelment of its Ardee Lead 9997 brand with the London Metal Exchange, alongside its Multi Commodity Exchange listing, has improved market credibility and customer reach.
The company is looking beyond its earlier concentration on Korea by exploring Thailand, Malaysia and China. Management said it is still executing trial orders in these markets and may secure either higher volumes or better realisation at comparable volumes, but it did not provide a financial forecast for these opportunities.
Ardee Industries is also prioritising larger requirements from existing customers rather than simply adding customers. Management said its top seven to 10 customers have been associated with the company since the current management acquired it in 2021, while a new customer's sample, trial and approval process can take about one to one-and-a-half years.
Conclusion
Ardee Industries delivered 34% year-on-year H1 FY27 revenue growth to Rs 664 crore and EBITDA of Rs 63 crore, but management is prioritising volume expansion over an immediate margin recovery. Its stated outlook for EBITDA per tonne near Rs 18,000 reflects the continuing effect of higher-cost imported inputs, freight and fuel rather than a reduction in demand or sales ambition.
The next indicators are whether second-half volume is sufficient to deliver the 10% to 15% FY27 growth target and whether domestic procurement advances from the current 27% to 28% share. Management also said it is working on plans for the 6-acre Naidupeta land parcel and expects to have more to share in a few months.