










ARIS posts record Rs 22.8 crore PAT, 11.6% EBITDA margin
Key highlights
- ARIS reported Q2 FY27 PAT of Rs 22.8 crore, up 50% year on year.
- Q2 FY27 EBITDA margin reached 11.6%, up 220 basis points from 9.3%.
- H1 FY27 revenue rose 32% to Rs 598.5 crore and PAT increased 110% to Rs 42.9 crore.
- ARIS management guided to approximately Rs 100 crore of consolidated FY27 PAT.
powered by IRIS
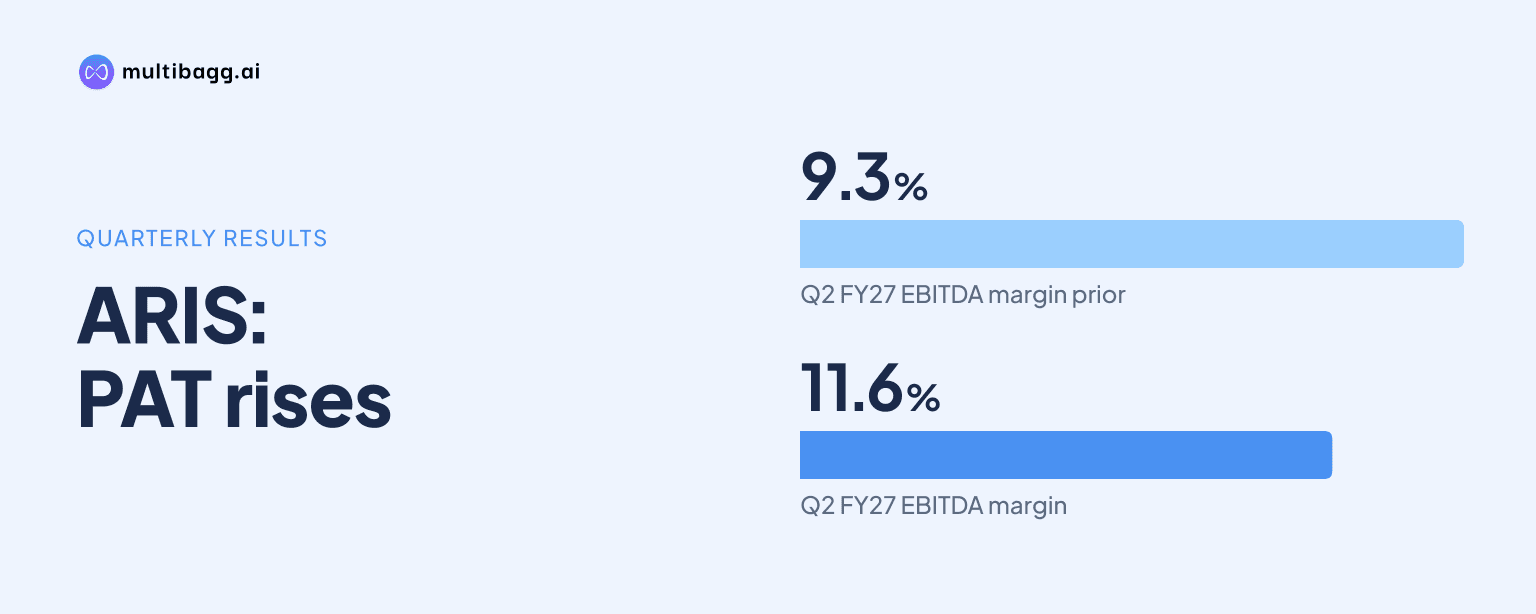
Arisinfra Solutions Limited reported record quarterly profit after tax of Rs 22.8 crore in Q2 FY27, up 50% year on year, while EBITDA margin rose 220 basis points to 11.6%. ARIS generated Rs 307.7 crore of revenue, up 28%, and said both quarterly PAT and EBITDA margin were its highest levels.
Know Arisinfra Solutions inside out
Results, valuation, peers and who's buying, in one view.
How did ARIS perform in Q2 FY27?
ARIS reported consolidated, unaudited revenue of Rs 307.7 crore in Q2 FY27, compared with Rs 241.2 crore in Q2 FY26, an increase of 28%. Earnings before interest, tax, depreciation and amortisation, or EBITDA, was Rs 35.6 crore, up 58% year on year, while EBITDA margin increased to 11.6% from 9.3%.
Profit after tax, or PAT, rose faster than revenue in the quarter. ARIS reported PAT of Rs 22.8 crore in Q2 FY27 versus Rs 15.3 crore in Q2 FY26, a 50% increase. PAT attributable to shareholders was Rs 20.8 crore and earnings per share were Rs 2.51.
Contract manufacturing and Developer as a Service, or DaaS, represented 66% of Q2 FY27 revenue, up 13 percentage points from 53% in Q2 FY26, according to management's segmental measure. ARIS states that EBITDA excludes other income, while PAT includes non-controlling interests.
What changed in ARIS's first-half earnings?
ARIS generated Rs 598.5 crore of revenue in H1 FY27, compared with Rs 453.3 crore in H1 FY26, a 32% increase. EBITDA margin rose to 11.1% from 9.0%, a 210-basis-point year-on-year improvement. The H1 margin was below Q2 FY27's 11.6%, while H1 revenue was almost double the Rs 307.7 crore reported for Q2 alone.
H1 FY27 PAT was Rs 42.9 crore, compared with Rs 20.4 crore in H1 FY26, a 110% increase. The increase in first-half PAT exceeded the 32% revenue growth, while contract manufacturing plus DaaS accounted for 64% of H1 FY27 revenue versus 51% a year earlier. The 13-percentage-point shift matched the change reported for Q2.
ARIS also reported operating cash flow of Rs 60.1 crore in H1 FY27, equivalent to 1.4 times PAT for the period. Net working capital stood at 54 days on September 30, 2026, down 36% from September 30, 2025. These figures measure a six-month cash-flow period and a balance-sheet date rather than Q2 income alone.
Got a follow-up? Ask IRIS
How has ARIS progressed against its Q1 FY27 update?
ARIS had stated a Q1 FY27 revenue-growth outlook of 35% to 40%, while actual H1 FY27 revenue growth was 32%. The presentation does not disclose a revised full-year revenue-growth forecast. Its comparison places the reported first-half outcome below the lower end of the earlier 35% to 40% range.
Reserved capacity increased from more than 9 million tonnes at June 30 to 11.7 million tonnes at September 30. DaaS gross development value, or GDV, increased from Rs 1,839 crore at June 30 to more than Rs 2,750 crore in the October 27 release cited in the presentation. ARIS identifies the latter figure as a live DaaS order book, rather than recognised revenue.
Asphalt and bitumen revenue was Rs 73 crore in H1 FY27, against the Q1 outlook of Rs 80 crore to Rs 100 crore over 12 to 18 months. ARIS annualised the half-year revenue at Rs 146 crore by multiplying it by two. Net debt was Rs 74 crore at September 30, within the Q1 outlook of Rs 75 crore to Rs 80 crore, and represented 0.10 times equity.
What is ARIS management's FY27 profit outlook?
ARIS management has guided to approximately Rs 100 crore of consolidated PAT in FY27, compared with Rs 60 crore in FY26, which it describes as a 66% increase. This is management guidance rather than a reported result. The company had delivered Rs 43 crore in H1 FY27 and indicated approximately Rs 57 crore of PAT for H2 FY27.
The reported H1 FY27 PAT of Rs 42.9 crore represented 43% of the approximately Rs 100 crore guidance, using the presentation's rounded figures. ARIS describes the first half as the lighter half of the year, while H1 represented 34% of FY26 PAT. The presentation shows H2 FY26 PAT of Rs 39.9 crore, derived as FY26 PAT less H1 FY26 PAT.
Delivering management's H2 FY27 guidance would require approximately Rs 57 crore of PAT in the second half, compared with Rs 42.9 crore in H1 FY27 and Rs 39.9 crore in H2 FY26. ARIS does not provide quarterly H2 targets, second-half revenue guidance or a separate EBITDA-margin target.
Conclusion
ARIS's Q2 FY27 results show PAT growing faster than revenue, with quarterly PAT increasing 50% to Rs 22.8 crore against a 28% rise in revenue to Rs 307.7 crore. The 11.6% EBITDA margin and the increased contribution of contract manufacturing and DaaS coincided with H1 FY27 PAT growth of 110% to Rs 42.9 crore.
The next disclosed benchmark is management's approximately Rs 57 crore H2 FY27 PAT guidance, which underpins its approximately Rs 100 crore FY27 PAT target. Investors can also monitor whether the more than Rs 2,750 crore DaaS GDV order book, 11.7 million tonnes of reserved capacity and Rs 74 crore of net debt at September 30 support the planned second-half outcome.