










Atlanta Electricals Pursues Branded US Sales Through Partners
Key highlights
- Atlanta has shortlisted two US support partners for its branded sales strategy.
- Atlanta will initially offer US customers transformers rated at 220 kV and below.
- Atlanta produced 8,664 MVA in H1 FY27.
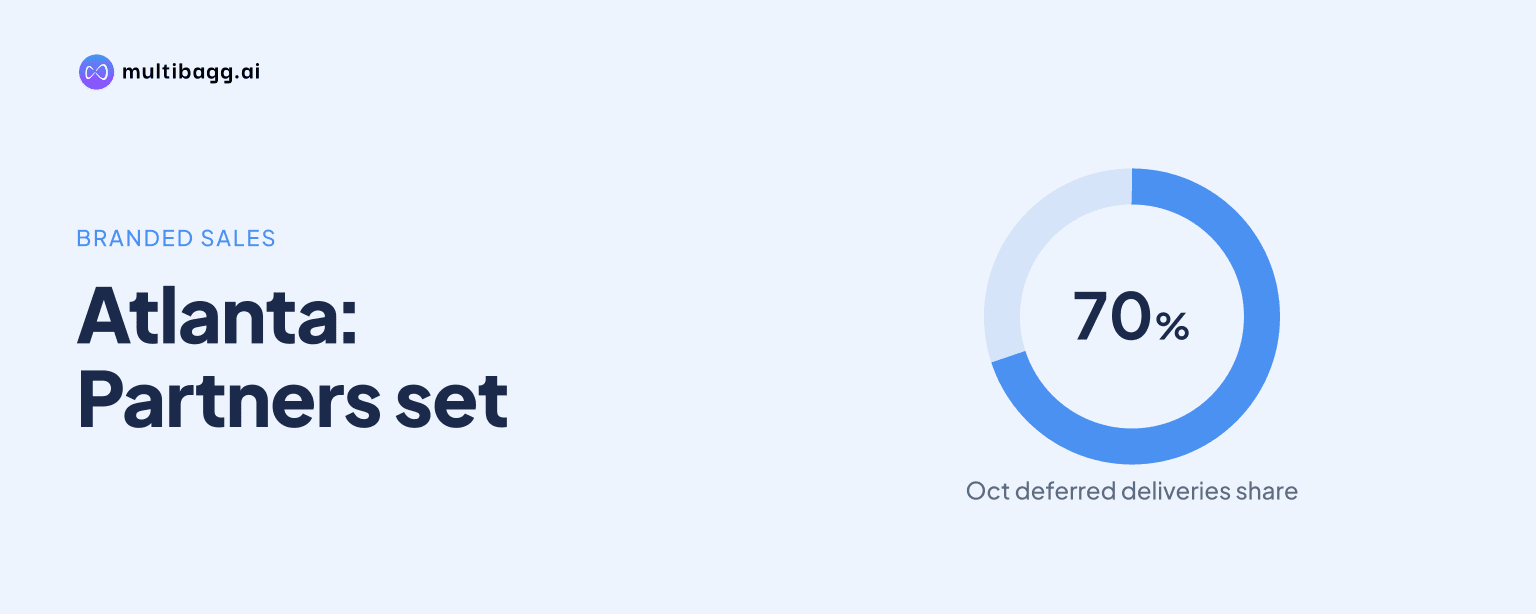
- About 70% of the Rs 180 crore of deferred finished-goods deliveries at September 30, 2026 were dispatched in October.
powered by IRIS
Atlanta Electricals is pursuing branded US transformer sales through two shortlisted support partners, with initial offerings focused on products rated at 220 kilovolts (kV) and below. Management said Atlanta will manufacture in India, has received a first specialty-transformer order, and sees no tariff impact on the US inquiries currently under evaluation.
Know Atlanta Electricals inside out
Results, valuation, peers and who's buying, in one view.
How will Atlanta enter the US transformer market?
Atlanta plans to enter the United States through its own market relationships and two shortlisted support partners, rather than as a white-label or contract manufacturer. Management said one of the partners would be responsible for taking the Atlanta brand forward in the US, making the strategy dependent on third-party commercial support rather than an owned US sales or manufacturing operation.
The first US order is for a specialty transformer that management described as unique and highly technical. Atlanta did not disclose the order value, customer identity, delivery timing or expected revenue contribution, so the first order establishes a product entry point but does not quantify the scale of US business under development.
Which products will Atlanta sell and manufacture for US customers?
Atlanta will initially focus on transformer products rated at 220 kV and below for the US market. This is a defined entry range, while management separately said that 400 kV and higher products would become a larger domestic order-book focus after the company develops a 400 kV prototype unit.
Atlanta has no manufacturing facility in the US and will manufacture at its Indian units before supplying American customers. That approach avoids a disclosed plan for overseas production investment, but ties US deliveries to the output, dispatch capacity and supply-chain performance of its Indian plants.
Are tariffs and US pricing affecting Atlanta's initial inquiries?
Atlanta said it did not see any tariff impact at the time of the call on the US inquiries it was working on. Management's comment covered current inquiries, not future tariff changes, completed shipments or a quantified tariff cost, and it did not provide a projected price effect for US customers.
Management said US margins are better, but declined to endorse an analyst's suggestion of a 5% to 6% gross-margin benefit. Atlanta gave no numerical US margin target and did not say that US sales underpin its earnings before interest, tax, depreciation and amortisation (EBITDA) margin guidance of 16% to 18% for FY27 and FY28.
Can Atlanta's Indian plants support US deliveries?
Atlanta produced 8,664 megavolt-amperes (MVA) during H1 FY27, while utilisation differed substantially across plants. The Bangalore plant was operating at about 90%, compared with 60% at Unit 1 in Anand, 40% at Unit 2 in Anand, 30% at the Vadod facility and 7% to 8% at the Jambusar 765 kV plant.
Management attributed lower utilisation at certain facilities to heavy rainfall and delayed dispatches rather than a stated shortage of production orders. It said transformers ready for delivery remained in finished-goods inventory of about Rs 180 crore at September 30, 2026, and around 70% of those deferred deliveries were dispatched during October.
Atlanta expects utilisation to increase during H2 of the current financial year as execution improves after the monsoon disruption. Management said optimum utilisation is 80%, while also cautioning through its operating comments that revenue recognition depends on dispatching completed transformers, not only on production activity measured in MVA.
Got a follow-up? Ask IRIS
How does the US plan fit Atlanta's domestic order book?
Atlanta reported an order book of Rs 3,197 crore and said this provided roughly 1.5 years of visibility for 220 kV and below products. Management described slower order intake in the quarter as a deliberate decision to limit additional lower-voltage bookings after substantial Q1 order inflow, rather than a change in market conditions.
The existing backlog remains weighted towards lower-voltage equipment. Management said 400 kV orders represented 8.60% of the order book, while 220 kV orders accounted for another 47%, showing that the US entry range broadly overlaps with a significant domestic order category rather than with Atlanta's smaller current 400 kV backlog.
Atlanta said it would open its doors to 400 kV-class orders after developing a prototype, while continuing to pursue quoted 220 kV and lower-voltage work. Management expects a greater focus on 400 kV and above orders to extend order visibility, but did not state a timetable for prototype completion or quantify the capacity that could be allocated to US exports.
What supply and execution issues could affect Atlanta's US rollout?
Atlanta described recent component disruption as temporary, citing back-to-back typhoons in China and Japan and reduced container availability linked to the Middle East war. Management said part of its inventory was directed to stockpiling critical components and that the inventory on hand could tentatively support about one quarter of raw-material requirements.
Management said it did not see current supply pressure for transformer tanks, radiators, copper conductors, bushings or other components. Atlanta is pursuing backward integration for tanks and radiators to improve quality and shorten supply timelines, with that facility expected in October 2027 rather than as an immediate response to the temporary supply disruption.
Atlanta said it intends to deepen supplier relationships and help suppliers establish business in India, with the aim of securing priority access to critical components. This supply-chain plan matters for the US strategy because all initial American deliveries are intended to be manufactured in Indian units, alongside execution of the Rs 3,197 crore domestic order book.
Conclusion
Atlanta's US strategy is a branded, partner-supported export approach rather than white-label manufacturing or local US production. Two shortlisted support partners, a first specialty-transformer order and an initial focus on 220 kV and below products define the disclosed plan, while management's comments on tariffs and margins remain limited to current inquiries and broad qualitative expectations.
The next items to watch are whether the two shortlisted partners become active commercial channels, whether further US inquiries convert into disclosed orders, and whether H2 execution lifts utilisation after the September 30, 2026 dispatch delays. Management also plans to develop a 400 kV prototype and expects its tank-and-radiator backward-integration facility in October 2027.