










Choice Q2 revenue rises 33% while PAT margin slips to 18.3%
Key highlights
- Choice reported Q2 FY27 revenue of Rs 379 crore, up 33% year on year.
- Choice reported Q2 FY27 PAT of Rs 69.5 crore, up 23% year on year.
- Choice’s calculated Q2 FY27 PAT margin was 18.3%, versus 19.9% in Q2 FY26.
- NH Investment & Securities completed a Rs 900 crore investment in Choice Equity Broking on 27 October 2026.
powered by IRIS
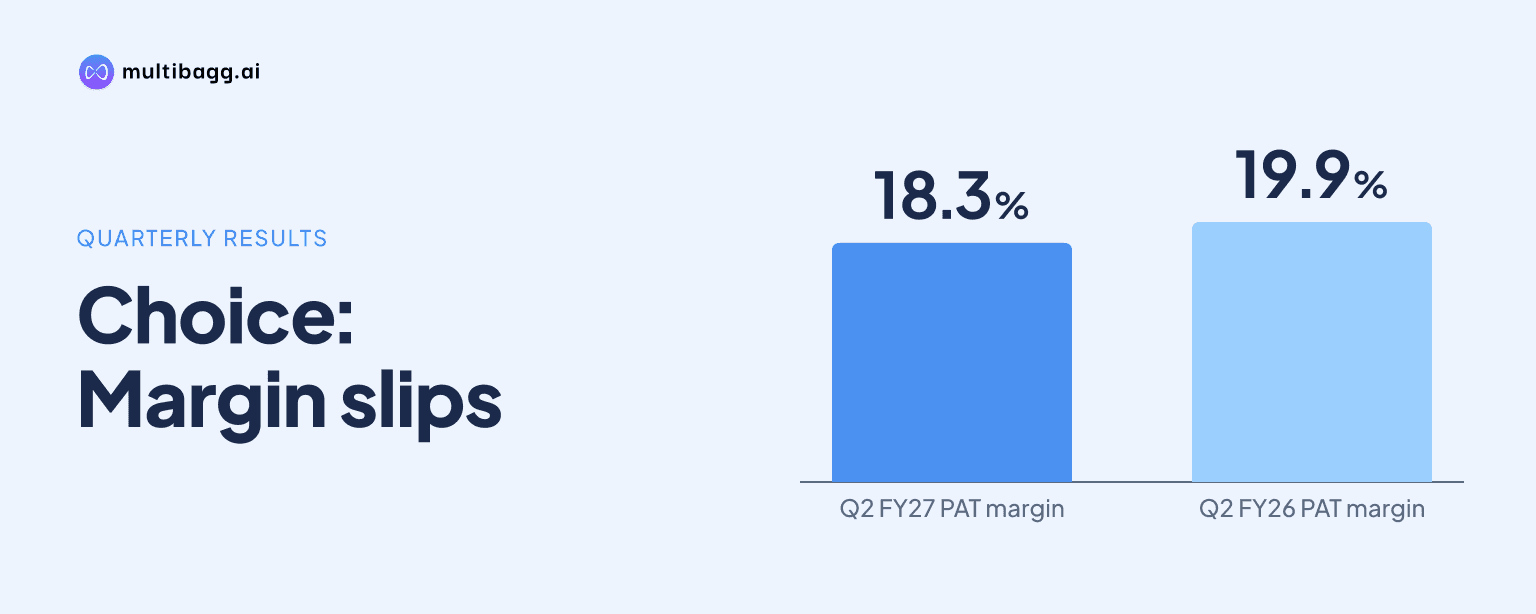
Choice International reported Q2 FY27 revenue of Rs 379 crore, up 33% year on year, while profit after tax, or PAT, rose 23% to Rs 69.5 crore and calculated PAT margin declined to 18.3% from 19.9% in Q2 FY26. The presentation reports the outcome but not an expense-by-expense explanation.
Know Choice International inside out
Results, valuation, peers and who's buying, in one view.
How did Choice perform in Q2 FY27?
Choice delivered higher revenue, earnings before interest, tax, depreciation and amortisation, or EBITDA, and PAT in Q2 FY27. Revenue rose to Rs 379 crore from Rs 284.1 crore in Q2 FY26, while EBITDA increased to Rs 130.6 crore from Rs 99 crore. PAT rose to Rs 69.5 crore from Rs 56.5 crore, but its 23% growth rate trailed the 33% revenue increase.
Choice’s Q2 FY27 revenue was also above Rs 319 crore in Q1 FY27 and Rs 313.8 crore in Q4 FY26. PAT reached Rs 69.5 crore, compared with Rs 60.6 crore in Q1 FY27 and Rs 67.8 crore in Q4 FY26. Q2 FY27 was therefore the highest point for both revenue and PAT in the five-quarter series supplied.
Why did Choice’s PAT margin decline in Q2 FY27?
Choice’s calculated PAT margin fell because PAT represented a smaller share of revenue in Q2 FY27 than a year earlier. PAT of Rs 69.5 crore divided by revenue of Rs 379 crore produces an 18.3% margin, compared with 19.9% from Rs 56.5 crore PAT and Rs 284.1 crore revenue in Q2 FY26. This margin is calculated from the reported figures and is not separately stated by Choice.
The calculated EBITDA margin also narrowed, though by less than the PAT margin. EBITDA of Rs 130.6 crore was 34.5% of Q2 FY27 revenue, versus 34.8% from Rs 99 crore EBITDA in Q2 FY26. Revenue rose 33%, EBITDA increased 32%, and PAT increased 23%, leaving the post-tax measure furthest behind top-line growth.
The supplied Q2 FY27 pages do not identify a particular expense responsible for the lower calculated PAT margin. They provide revenue, EBITDA and PAT, but no employee-cost, finance-cost, depreciation, tax or other operating-expense line item. The figures establish that profit growth lagged revenue growth, but not the detailed cost mechanism behind that result.
How did Choice compare with the preceding quarter?
Choice improved all three reported measures from Q1 FY27 to Q2 FY27. Revenue increased by Rs 60 crore from Rs 319 crore, EBITDA increased by Rs 16.6 crore from Rs 114 crore, and PAT increased by Rs 8.9 crore from Rs 60.6 crore. The quarter therefore showed sequential growth in absolute revenue and earnings.
Calculated margins moved lower sequentially despite those absolute gains. PAT margin was 19.0% in Q1 FY27, based on Rs 60.6 crore PAT and Rs 319 crore revenue, before declining to 18.3% in Q2 FY27. EBITDA margin moved from 35.7% in Q1 FY27 to 34.5% in Q2 FY27.
Over the longer series, Choice’s revenue increased from Rs 78.5 crore in Q2 FY23 to Rs 379 crore in Q2 FY27. The presentation states a 48% compound annual growth rate, or CAGR, for revenue over that history. PAT rose from Rs 8.2 crore in Q2 FY23 to Rs 69.5 crore in Q2 FY27, for a presentation-stated 71% CAGR, although it fell from Rs 46.5 crore in Q2 FY25 to Rs 30.7 crore in Q3 FY25.
Got a follow-up? Ask IRIS
Which businesses contributed to Choice’s reported scale?
Choice’s H1 FY27 revenue mix was led by Broking & Distribution at 55%, followed by Advisory at 32% and the non-banking financial company, or NBFC, at 12%. This disclosed mix shows that the Rs 379 crore consolidated Q2 FY27 revenue figure spans several activities. The presentation does not provide separate Q2 FY27 revenue or profit figures for Advisory and NBFC.
Broking & Distribution revenue, including wealth products and insurance, was Rs 178.2 crore in Q2 FY27, up 11% from Rs 160.7 crore in Q2 FY26. The segment’s growth rate was below the 33% rise in consolidated revenue. Demat accounts increased 14% year on year to 13.79 lakh at 30 September 2026, while retail average daily turnover market share rose to 1.54% from 1.31% in Q2 FY26.
Choice also reported a Rs 710 crore Advisory order book, operations in more than 24 states and union territories, and 24 ongoing initial public offering mandates. Its NBFC had a Rs 936 crore total loan book, including a Rs 609 crore retail loan book, as well as a 37.36% capital-to-risk-weighted-assets ratio and 2.44% net non-performing assets.
What does the NHIS investment add to Choice’s plans?
Choice disclosed a Rs 900 crore primary capital infusion by NH Investment & Securities Co., Ltd. into Choice Equity Broking Private Limited through compulsory convertible preference shares. The transaction was completed on 27 October 2026, after the Q2 FY27 period in which Choice reported Rs 379 crore revenue and Rs 69.5 crore PAT.
Management identified expansion of the margin trading facility, or MTF, book and settlement-funding portfolio, working capital and capital expenditure, strategic acquisitions, and broking and wealth-management initiatives as intended uses. Choice’s Q2 FY27 MTF book was Rs 463.4 crore, up 42% year on year, while wealth-products assets under management were Rs 6,047.1 crore, up 26%.
The capital infusion is a disclosed deployment plan rather than a Q2 FY27 operating contribution. Choice’s entity structure at 30 September 2026 showed 90% ownership of Choice Equity Brokerage, while the supplied material does not state the resulting post-transaction ownership position. It therefore does not quantify any future impact on revenue, expenses or margins.
Conclusion
Choice’s Q2 FY27 figures show continued expansion in revenue and earnings, but different rates of growth changed the profit conversion outcome. Revenue rose 33% to Rs 379 crore, compared with a 23% increase in PAT to Rs 69.5 crore, while Broking & Distribution contributed Rs 178.2 crore of Q2 revenue and represented part of a 55% H1 FY27 revenue share.
The next development to watch is management’s deployment of the Rs 900 crore received on 27 October 2026. Its stated priorities include the Rs 463.4 crore MTF book, settlement funding, strategic acquisitions, and broking and wealth initiatives, but the presentation leaves the timing and profitability effects of that deployment unresolved.