










Chola MS Q2 loss follows floods as combined ratio hits 128%
Key highlights
- Chola MS reported a Rs 8 crore Q2 FY27 profit-after-tax loss, compared with a Rs 91 crore profit in Q2 FY26.
- Chola MS's Q2 FY27 CoR increased to 128.0% from 115.8% a year earlier.
- Flood-related natural-catastrophe events reduced Chola MS H1 FY27 profit before tax by Rs 71.2 crore, including Rs 58.3 crore in Q2.
- Chola MS H1 FY27 GWP rose 7.1% to Rs 4,517 crore while profit after tax fell 60.4% to Rs 78 crore.
powered by IRIS
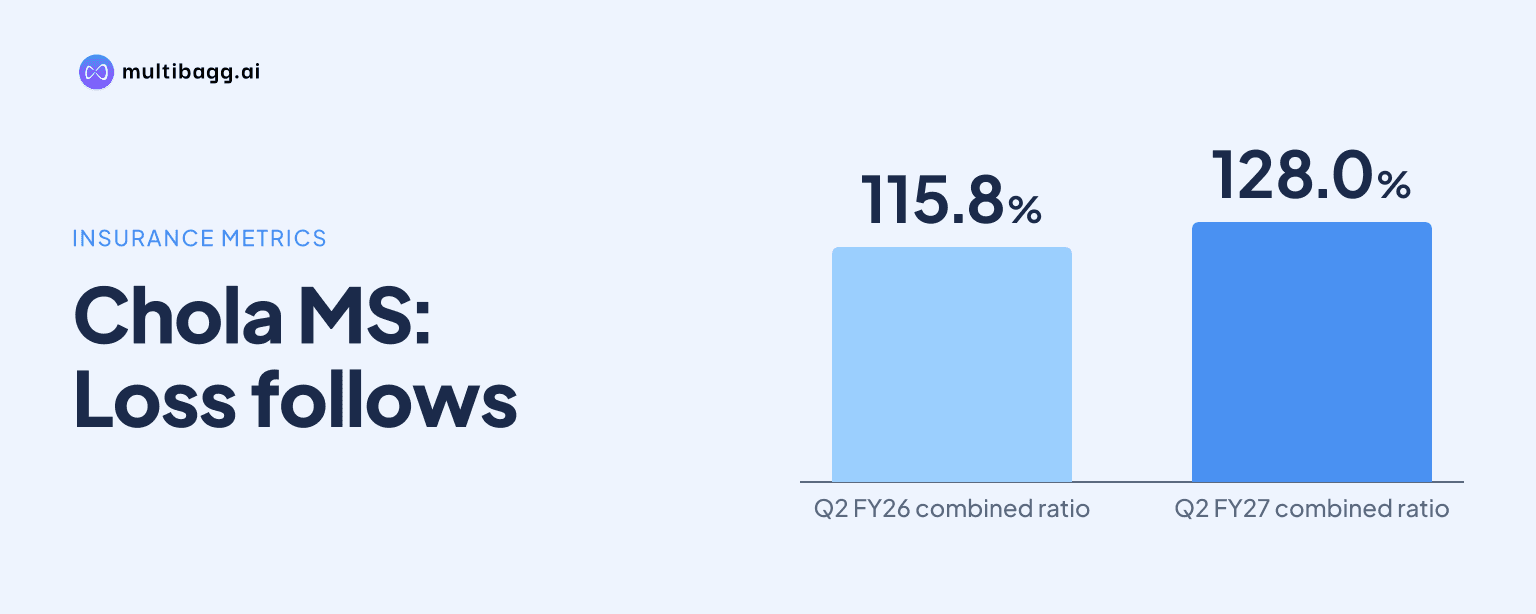
Chola MS General Insurance reported a Rs 8 crore loss in Q2 FY27, compared with a Rs 91 crore profit in Q2 FY26, as floods and higher motor claims lifted its combined ratio (CoR) to 128.0% from 115.8%. Gross written premium (GWP), including reinsurance inward business, nevertheless increased 7.4% to Rs 2,386 crore.
Know Cholamandalam Financial Holdings inside out
Results, valuation, peers and who's buying, in one view.
What caused Chola MS's Q2 FY27 loss?
Chola MS's Q2 FY27 loss was caused by natural-catastrophe claims and higher motor claims, which widened its underwriting loss to Rs 406 crore from Rs 247 crore a year earlier. Net investment income rose to Rs 383 crore from Rs 368 crore, but did not offset the underwriting result. Profit before tax moved to a Rs 19 crore loss from a Rs 121 crore profit.
Floods in Maharashtra, Gujarat, Daman and Diu reduced H1 FY27 profit before tax by Rs 71.2 crore, including Rs 58.3 crore in Q2, according to Chola MS. The Q2 CoR excluding natural-catastrophe events was 125.1%, against the reported 128.0%, indicating that claims and expenses exceeded net written premium even without the full flood impact.
The 12.2-percentage-point increase in the CoR reflected a rise in the net incurred claims-to-net earned premium ratio to 91.7% from 81.9%. Net acquisition costs plus operating expenses as a share of net written premium also increased to 36.3% from 33.9%, adding to the underwriting pressure in Q2 FY27.
Did premium growth offset Chola MS's underwriting deterioration?
Chola MS's premium growth did not offset weaker underwriting because Q2 FY27 GWP increased 7.4% while net written premium fell 7.8% to Rs 1,492 crore. Net earned premium declined 1.6% to Rs 1,643 crore, whereas the underwriting loss increased 64.4% to Rs 406 crore. The result was a quarterly loss despite higher investment income.
For H1 FY27, GWP rose 7.1% to Rs 4,517 crore from Rs 4,217 crore, while gross direct premium income increased 1.6% to Rs 3,705 crore. Net written premium fell to Rs 2,908 crore from Rs 3,030 crore, but net earned premium rose to Rs 3,314 crore from Rs 3,190 crore. The H1 underwriting loss still widened to Rs 658 crore from Rs 435 crore.
Chola MS reported Rs 472 crore of premium received in advance in H1 FY27. On the presentation's one-over-n premium basis, H1 FY27 GWP was Rs 4,517 crore and profit after tax was Rs 78 crore; excluding that impact, GWP was Rs 4,641 crore and profit after tax was Rs 116 crore.
Which Chola MS insurance lines recorded higher claims?
Commercial insurance recorded the largest reported Q2 FY27 loss-ratio increase, reaching 132.8% from 79.3% in Q2 FY26. Excluding natural-catastrophe events, the commercial loss ratio was 84.3%, which indicates that flood claims accounted for much of the difference between the reported and adjusted Q2 figures.
Motor remained a broader claims pressure. The motor total loss ratio rose to 88.5% in Q2 FY27 from 80.7% a year earlier and was 87.1% excluding natural-catastrophe claims. Motor own-damage loss ratio reached 98.0%, or 93.9% excluding such claims, while the motor third-party loss ratio increased to 83.9% from 78.1%.
Health, travel and accident recorded a 96.8% loss ratio in Q2 FY27, compared with 88.4% in Q2 FY26. Chola MS said it had implemented motor portfolio-correction measures, with benefits expected in the coming quarter. It also attributed slower motor growth to pricing corrections and a focus on selected geographies and counters to improve claims experience.
Got a follow-up? Ask IRIS
How did Chola MS growth compare with the insurance industry?
Chola MS grew more slowly than the industry in H1 FY27, with gross direct premium income rising 1.6%, compared with industry growth of 9.1%. Its H1 performance differed by line: other commercial lines grew 31.6%, accident grew 50.4%, and motor grew 4.1%, while health declined 27.1% and crop declined 93.7%.
Chola MS said its group-health portfolio was being realigned towards profitable counters and that it was focusing on growth in its commercial book. The company also said motor growth reflected pricing-corrective initiatives and its focus on the right geographies and counters. These measures coincided with GWP reaching Rs 4,517 crore in H1 FY27.
Over the longer period from FY22 to FY26, Chola MS's GWP increased from Rs 4,854 crore to Rs 8,904 crore, representing a 16.4% compound annual growth rate. Its gross direct premium income compound annual growth rate was 12.6%, compared with 12.5% for private insurers and 10.8% for the industry. Motor gross direct premium income grew at a 13.5% rate, compared with 12.7% for private insurers.
What do Chola MS capital and investments show after the loss?
Chola MS reported net worth of Rs 3,408 crore in H1 FY27, compared with Rs 3,197 crore in H1 FY26, while H1 profit after tax fell 60.4% to Rs 78 crore from Rs 198 crore. Its solvency ratio declined to 1.880 times from 2.112 times, and return on average net worth, not annualised, fell to 2.3% from 6.4%.
The investment portfolio was Rs 19,052 crore at September 2026, compared with Rs 18,382 crore at September 2025, and generated Rs 764 crore of net investment income in H1 FY27, up from Rs 712 crore. Government securities totalled Rs 8,240 crore and equity investments Rs 1,498 crore at September 2026. Chola MS stated that it had no stressed assets and no exposure to securities rated below AA.
Investment portfolio yield without profit on sale was 7.0% at September 2026, up from 6.8% a year earlier. The investment book-to-net-worth ratio was 5.6 times at September 2026, versus 5.7 times a year earlier, while the quarterly underwriting loss remained the principal driver of the Q2 FY27 net loss.
Conclusion
Chola MS's Q2 FY27 result shows that 7.4% GWP growth did not compensate for worsening claims experience. The CoR reached 128.0%, the underwriting loss widened to Rs 406 crore and profit after tax moved from a Rs 91 crore profit to a Rs 8 crore loss. Flood claims contributed to the deterioration, while motor and health claims remained elevated.
The next reported quarter will show whether Chola MS's stated motor portfolio-correction measures begin to lower claims experience. Key disclosed measures to watch include motor pricing actions, a focus on selected motor geographies and counters, group-health portfolio realignment and commercial-book growth, alongside the Q2 FY27 CoR of 125.1% excluding natural-catastrophe claims.