










CMSGICL H1 profit falls to Rs 8 crore; Ind AS loss Rs 64.32 crore
Key highlights
- CMSGICL reported Rs 8 crore H1 profit after tax for the six months ended September 30, 2026, against Rs 165 crore a year earlier.
- CMSGICL's converted Ind AS result was a Rs 64.32 crore H1 loss after tax.
- CMSGICL had Rs 24,469.77 crore of converted total assets and a Rs 18,937 crore investment book at September 30, 2026.
- The insurance segment's H1 revenue rose to Rs 4,400.77 crore from Rs 4,150.46 crore, while pre-tax profit fell to Rs 222.60 crore from Rs 341.56 crore.
powered by IRIS
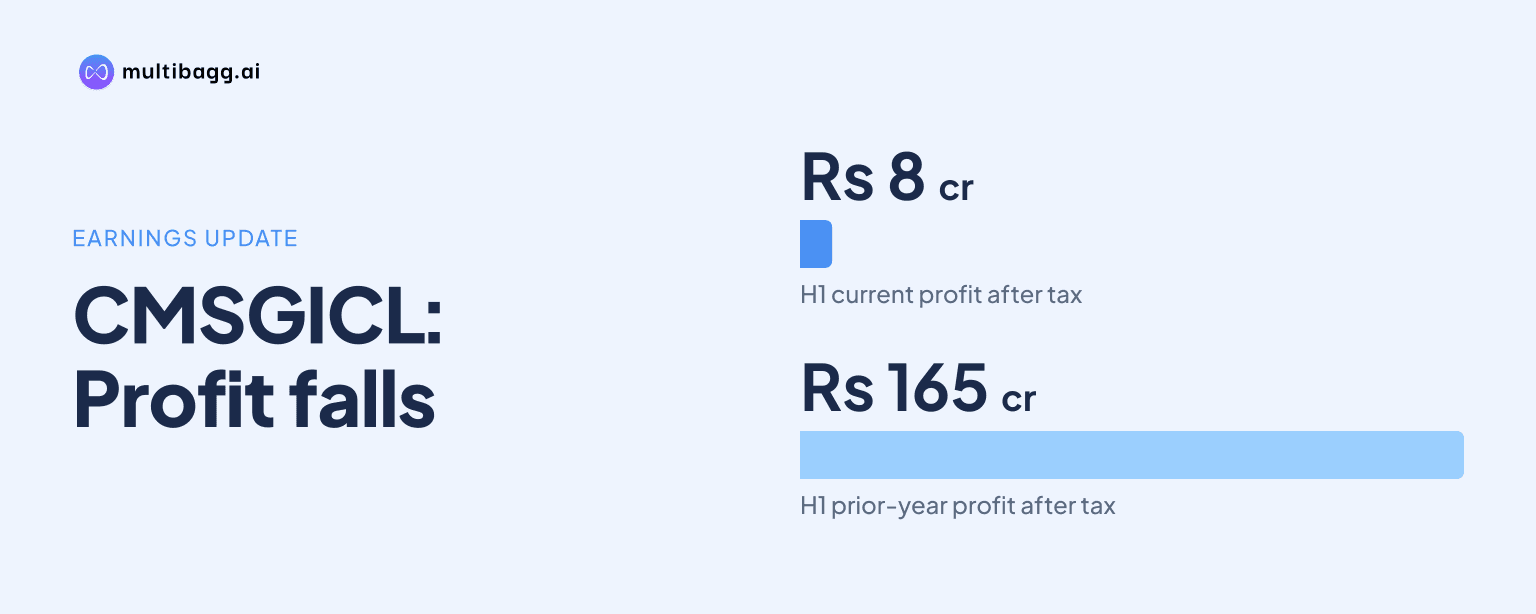
Cholamandalam MS General Insurance Company Limited reported profit after tax of Rs 8 crore for the six months ended September 30, 2026, down from Rs 165 crore a year earlier, while its Indian Accounting Standards conversion for consolidation showed a Rs 64.32 crore loss. Management attributed the reported-profit decline to catastrophe events and elevated motor own-damage claims.
Know Cholamandalam Financial Holdings inside out
Results, valuation, peers and who's buying, in one view.
Why did CMSGICL's H1 profit fall to Rs 8 crore?
CMSGICL's reported profit after tax for the six months ended September 30, 2026 was Rs 8 crore, compared with Rs 165 crore for the corresponding period ended September 30, 2025. Cholamandalam Financial Holdings Limited said the decline reflected natural-catastrophe, or NATCAT, events during the first half of financial year 2026-27 and elevated claim experience in the motor own-damage segment.
NATCAT events can increase claims across affected policies, while motor own damage refers to claims for physical damage to insured vehicles. The November 6, 2026 announcement did not quantify the separate effect of either factor, but directly linked both mechanisms to the change in H1 profit from Rs 165 crore to Rs 8 crore.
The filing identifies the earnings pressure at the insurer level while also showing that the wider insurance segment increased revenue during the same six-month period. That difference means the disclosed issue was not a lack of segment revenue growth, but the claims experience cited by management for CMSGICL in H1 FY27.
What was CMSGICL's Ind AS conversion result?
CMSGICL recorded a Rs 64.32 crore loss after tax for the six months ended September 30, 2026 after conversion to Indian Accounting Standards, or Ind AS, for consolidation. This contrasts with the Rs 8 crore profit after tax in the parent's press release under the insurer's direct reporting basis, changing the H1 result from a profit to a loss for consolidation purposes.
The consolidated auditor said CMSGICL management converted unaudited results prepared under Indian Generally Accepted Accounting Principles, or IGAAP, to comply with the recognition and measurement principles of Ind AS 34, the interim financial-reporting standard. For consolidation, insurance contracts are recognised under Ind AS 104 after considering clarifications issued by the Insurance Regulatory and Development Authority of India, or IRDAI.
The converted financial information reported total revenue of Rs 2,078.56 crore for the quarter ended September 30, 2026 and Rs 4,400.77 crore for the six months ended that date. The filing does not disclose individual conversion entries, so it does not identify a quantified cause for the Rs 72.32 crore difference between the reported Rs 8 crore H1 profit and the converted Rs 64.32 crore loss.
Why is CMSGICL not preparing Ind AS financial statements directly?
CMSGICL has entity-level regulatory forbearance from IRDAI for implementation of Ind AS during financial year 2026-27. The parent company's notes say insurance contracts are recognised for consolidation under Ind AS 104, consistent with previous years, while CMSGICL continues to prepare its own financial results under the applicable insurance accounting framework.
The auditor stated that IRDAI's approval for forbearance from preparing Ind AS financial statements extends until March 31, 2027. Until then, CMSGICL's unaudited results are prepared under IGAAP, including Accounting Standards specified under Section 133 of the Companies Act and the Companies (Accounting Standards) Rules, 2021, as well as applicable insurance-sector requirements.
For the group accounts, management converts CMSGICL's results to Ind AS 34 after applying IRDAI clarifications relating to Ind AS 104. One of CMSGICL's joint statutory auditors reviewed the converted results, while the consolidated auditor relied on the IGAAP review, actuary-related work and the reviewed conversion adjustments when reaching its conclusion for the September 2026 results.
Got a follow-up? Ask IRIS
How large was CMSGICL's business at September 2026?
CMSGICL had converted total assets of Rs 24,469.77 crore as at September 30, 2026, while its investment book was Rs 18,937 crore on that date. The investment-book figure was below total assets because the filing reports investments separately from other asset categories, although it does not provide an asset-class split for the investment book.
CMSGICL reported gross written premium growth of 7% for the quarter ended September 30, 2026 compared with the corresponding quarter of FY26. The supplied announcement does not preserve a readable rupee figure for quarterly gross written premium, so the 7% rate is the directly disclosed measure of premium movement.
At the consolidated level, the insurance segment generated Rs 4,400.77 crore of revenue for the six months ended September 30, 2026, compared with Rs 4,150.46 crore a year earlier. However, segment profit before tax fell to Rs 222.60 crore from Rs 341.56 crore, a decline alongside higher revenue during the period in which management cited catastrophe and motor own-damage claims.
What did the auditors say about CMSGICL's claims estimates?
The auditors did not modify their limited-review conclusion on the consolidated results for the quarter and half year ended September 30, 2026. Their report noted that CMSGICL's joint statutory auditors relied on the appointed actuary's certificate for estimates of incurred but not reported, or IBNR, claims; incurred but not enough reported, or IBNER, claims; and premium deficiency reserve, or PDR.
The auditor said IBNR, IBNER and PDR estimates are determined using statistical methods. These estimates form part of the insurer's financial information at a time when CMSGICL reported Rs 8 crore H1 profit on its direct basis and Rs 64.32 crore H1 loss after the Ind AS conversion used in consolidation.
The parent company's September 2026 consolidated financial results were subject to a limited review rather than a full audit. The auditor said such a review provides moderate assurance and has a narrower scope than an audit, but reported that nothing had come to its attention indicating that the consolidated statement lacked required disclosures or contained a material misstatement.
Conclusion
CMSGICL's H1 FY27 disclosure presents two different earnings outcomes: Rs 8 crore reported profit after tax, down from Rs 165 crore a year earlier, and a Rs 64.32 crore loss after Ind AS conversion for group consolidation. Insurance-segment revenue rose to Rs 4,400.77 crore, but segment profit before tax fell to Rs 222.60 crore as management cited NATCAT events and motor own-damage claims.
The next disclosed accounting milestone is March 31, 2027, the date until which IRDAI has approved CMSGICL's forbearance from preparing Ind AS financial statements. The treatment of insurance contracts under Ind AS 104 for consolidation and the reconciliation between direct reporting and converted results remain the key matters to watch in subsequent disclosures.