










Chola expects over 4% pre-tax ROA from newer businesses
Key highlights
- Chola expects unsecured, consumer-durable and digital-lending businesses to exceed 4% pre-tax ROA over the medium term, from about 3.6% currently.
- Chola’s consumer-loan disbursements rose 103% year on year to Rs 8,726 crore in Q2 FY27.
- Chola reported CSEL AUM of Rs 17,216 crore within total consumer-loan AUM of Rs 45,902 crore in Q2 FY27.
- Chola expects its operating-expense ratio to stay near 3.0% to 3.1% before moving toward 2.8% over two to three years.
powered by IRIS
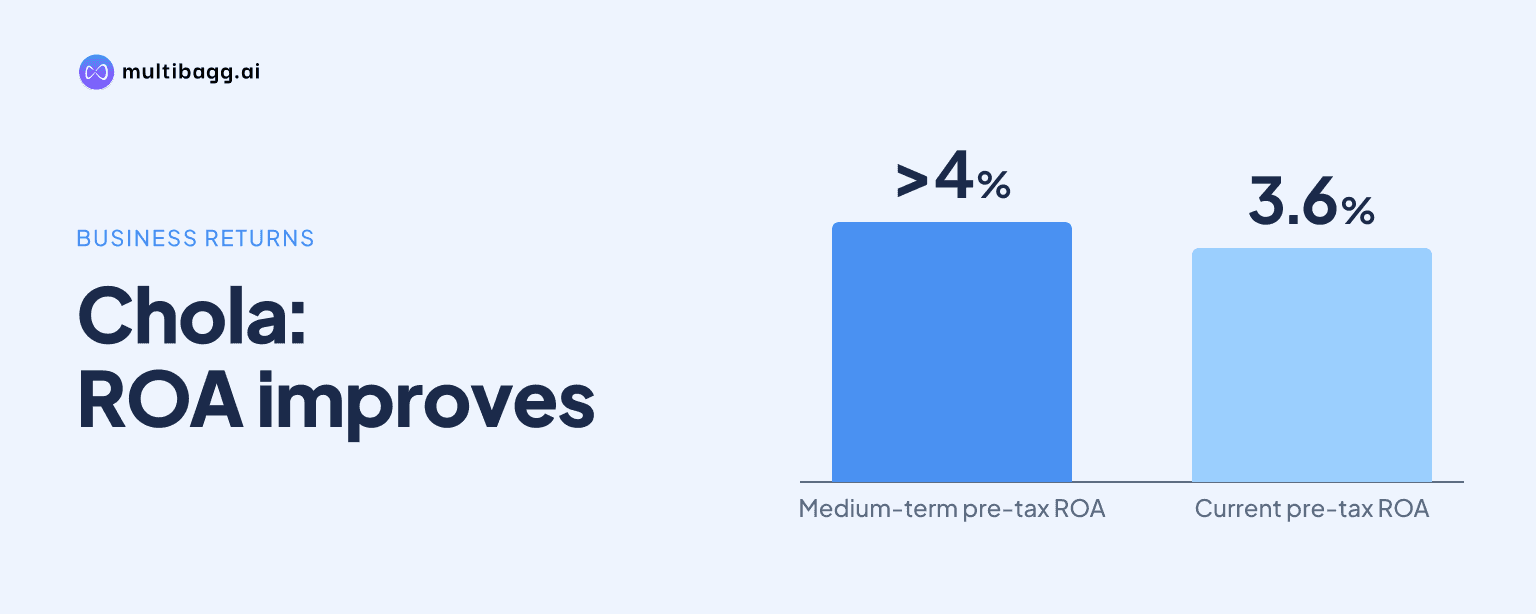
Cholamandalam Investment and Finance Company Limited said on October 28, 2026 that its unsecured, consumer-durable and digital-lending businesses could sustainably deliver more than 4% pre-tax return on assets, or ROA, over the medium term, compared with about 3.6% currently, as credit costs decline and operating leverage improves.
Know Cholamandalam Investment & Finance Company inside out
Results, valuation, peers and who's buying, in one view.
What return is Chola targeting from its newer lending businesses?
Chola is targeting a combined pre-tax ROA above 4% from unsecured business, personal and professional loans, consumer durables and digital lending, from the current level of around 3.6%. Managing Director and Chief Executive Officer Ravindra Kundu said the target is a medium-term expectation rather than a currently reported segment result, because Chola does not yet disclose financials separately for these businesses.
The 4% measure is pre-tax ROA, meaning profit before tax relative to assets, and applies to the combined set of businesses rather than each product individually. Chola described the intended result as sustainable but did not provide a date by which the target must be reached, a separate asset base for the group, or product-level profitability figures.
Which Chola products are included in the 4% ROA goal?
Chola said the target covers two broad groups within CSEL: unsecured business loans, personal loans and professional loans; and consumer durables, including mobile and non-mobile financing, alongside digital lending. Management said these businesses are led by Sucheth Bharathan and Vijay Kini, respectively, and will be reported separately when they reach meaningful size.
Consumer-durable growth has been driven mainly by mobile financing after Chola moved beyond its Samsung partnership over the previous 12 months and added ties with other original equipment manufacturers. Chola said it is operational in a majority of Tier 3 and Tier 4 markets across the country, while the unsecured portfolio expanded after underwriting models and credit scorecards were developed over several quarters.
Chola’s consumer-loan business, which also includes housing and gold loans outside the targeted group, reported disbursements of Rs 8,726 crore in Q2 FY27, up 103% year on year. Consumer-loan assets under management, or AUM, stood at Rs 45,902 crore, 32% higher than a year earlier, while CSEL AUM was Rs 17,216 crore; management did not specify how much belongs to unsecured loans, consumer durables or digital lending.
What does management say will lift Chola’s pre-tax ROA?
Chola said lower net credit costs and some moderation in operating expenses are the main mechanisms expected to lift the combined businesses from about 3.6% to more than 4% pre-tax ROA. Kundu attributed the expected credit-cost improvement to portfolio maturation and said operating leverage should emerge as the businesses reach meaningful scale.
The company’s wider Q2 FY27 performance provides the context for that expectation. Aggregate credit cost declined by 37 basis points year on year, while company-wide pre-tax ROA expanded by 40 basis points year on year. One basis point is one-hundredth of a percentage point. Chola also reported gross Stage 3 assets of 3.25% in September 2026, down from 3.29% in June 2026, and gross non-performing assets under Reserve Bank of India norms of 4.44%, down from 4.50%.
Management also linked future cost efficiency to its established lending businesses. Chola said its operating-expense ratio is expected to remain broadly at 3.0% to 3.1% in the near term, before gradually falling to around 2.8% over the next two to three years. Vehicle finance and loan-against-property portfolios were identified as mature businesses where scale has reduced operating costs, helping offset investment in gold loans, consumer durables and digital lending.
Got a follow-up? Ask IRIS
How does Chola’s target compare with its company-wide goals?
Chola’s more-than-4% target for the combined newer businesses is above the company-wide pre-tax ROA framework of 3.5% discussed on the call. When asked whether the company-wide figure could move closer to 4% as newer products mature over two to three years, Chief Financial Officer Arul Selvan said management would first track the new businesses’ traction and allow them to settle before changing that view.
Chola retained its FY27 operating targets despite reaching some metrics in the first half. At the beginning of the year, Chola aimed for around 25% growth and net credit costs of about 1.4% for the full year; management said both had been achieved in the first half, but did not revise guidance. It instead pointed to historically stronger Q3 and Q4 periods while emphasizing continued credit discipline.
The target sits within a portfolio still weighted to established products. Vehicle finance AUM was Rs 1,29,787 crore in Q2 FY27, 21% higher year on year, while secured small and medium enterprise finance AUM was Rs 72,356 crore, up 27%. By comparison, CSEL AUM of Rs 17,216 crore represented a smaller disclosed pool, reinforcing management’s point that the relevant portfolios must scale before separate performance disclosure.
When will Chola report these businesses separately?
Chola intends to disclose the two business groups separately once they become meaningful in size, but management gave no timetable, AUM threshold or reporting quarter. Kundu said Chola expects both groups to demonstrate strong profitability when independent reporting begins, while maintaining that segment-level financials are not currently disclosed.
The current growth rate reflects both expansion and a low comparison base, according to management. Chola said it had previously moderated disbursements after operating at monthly levels of about Rs 1,000 crore to Rs 1,200 crore, and that current quarterly volumes are broadly back at those earlier levels. Management said consumer-durable financing accounts for a majority of the year-on-year growth, while unsecured business and personal lending contributes about 40% of the increase discussed on the call.
Separate reporting could show whether lower credit costs and operating leverage are occurring across both groups or are concentrated in one product. Until then, the disclosed indicators are the combined 3.6% pre-tax ROA, the more-than-4% medium-term goal, and CSEL AUM of Rs 17,216 crore at the end of Q2 FY27.
Conclusion
Chola’s profitability target is a management expectation for a combined set of unsecured, consumer-durable and digital-lending portfolios that now generate about 3.6% pre-tax ROA. The expected move above 4% rests on maturing portfolios, lower net credit costs and declining cost intensity, while the company’s broader operating-expense ratio remains guided at 3.0% to 3.1% in the near term.
The next marker is whether Chola begins reporting the businesses separately as they reach meaningful scale. Management’s unchanged FY27 objectives of around 25% growth and approximately 1.4% net credit costs, along with its plan to reduce the operating-expense ratio toward 2.8% over the next two to three years, will indicate progress toward that outcome.