










CMS guides ₹2,650-2,750 crore services revenue, 27% EBITDA margin
Key highlights
- CMS guided FY27 services revenue of ₹2,650-2,750 crore and total revenue of ₹2,750-2,850 crore.
- CMS expects an EBITDA margin of about 27% and FY27 capital expenditure of ₹100-125 crore, versus ₹351 crore in FY26.
- H1 FY27 services revenue increased 12.7% year on year to ₹1,269 crore, while EBITDA margin rose to 27.0%.
- Tech and Payments reached 20% of services revenue in Q2 FY27, up from 16% in FY26.
powered by IRIS
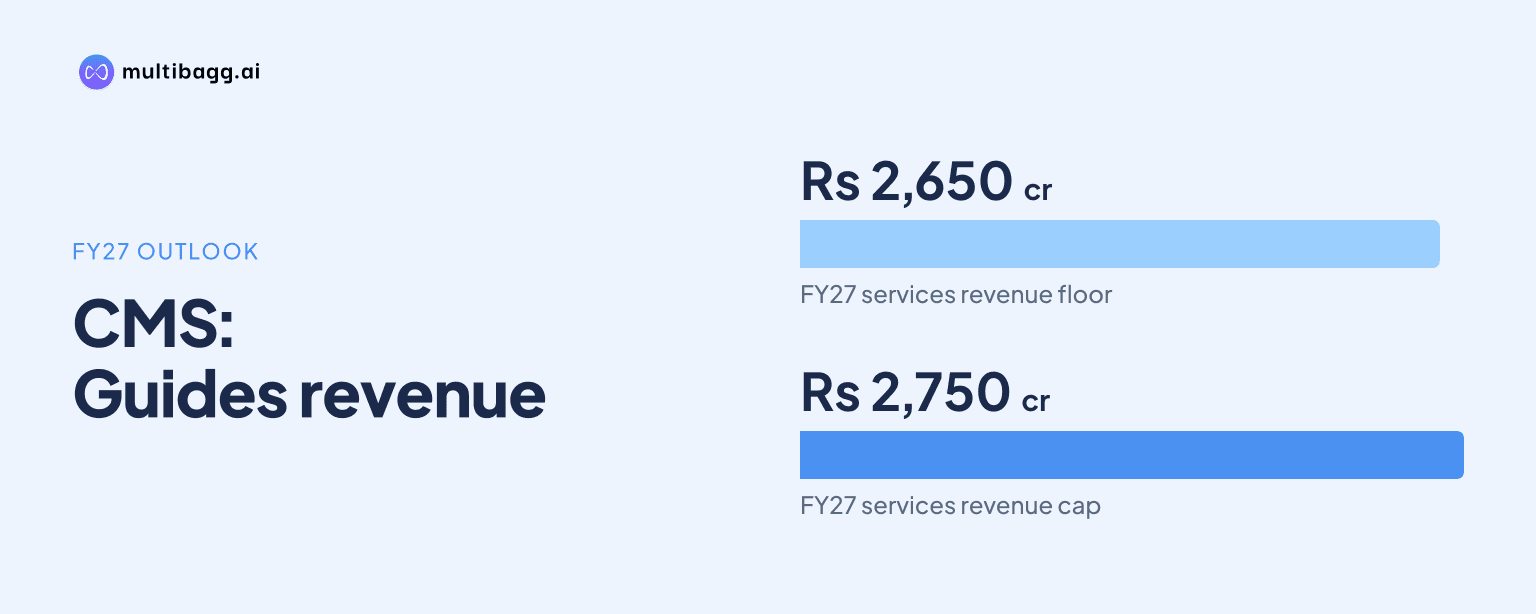
CMS has guided for fiscal year 2027 (FY27) services revenue of ₹2,650-2,750 crore and an earnings before interest, tax, depreciation and amortisation (EBITDA) margin of about 27%, with capital expenditure planned at ₹100-125 crore versus ₹351 crore in FY26. The outlook follows its FY26 reset, including fixed-fee mandates, acquisitions and a lower investment plan.
Know CMS Info Systems inside out
Results, valuation, peers and who's buying, in one view.
What is CMS's FY27 financial outlook?
CMS expects FY27 services revenue of ₹2,650-2,750 crore and total revenue of ₹2,750-2,850 crore. The company has also set an EBITDA-margin outlook of about 27%, alongside FY27 capital expenditure of ₹100-125 crore, down from ₹351 crore in FY26. The guidance puts services, rather than product deliveries, at the centre of the revenue plan.
The FY27 outlook follows first-half FY27 (H1 FY27) performance in which services revenue rose 12.7% year on year to ₹1,269 crore, while total revenue rose 3.9% to ₹1,284 crore. EBITDA increased 16.4% to ₹346 crore and the EBITDA margin expanded by 290 basis points to 27.0% from 24.1% in H1 FY26. One basis point equals one-hundredth of a percentage point.
CMS reported ₹650 crore of total revenue in the second quarter of FY27 (Q2 FY27), up 6.7% year on year and 2.4% quarter on quarter. Services revenue was ₹644 crore, up 16.2% from Q2 FY26, while Q2 EBITDA was unchanged sequentially at ₹173 crore. The quarterly EBITDA margin was 26.7%, 53 basis points below Q1 FY27 but 390 basis points above Q2 FY26.
Which actions underpin CMS's FY27 revenue target?
CMS says its FY27 revenue plan is supported by long-term fixed-fee mandates with SBI, ICICI Bank and HDFC Bank, price revisions with most private-sector banks and retail customers, and execution of Tech and Payments orders in H2 FY27. These actions followed the FY26 reset, when CMS also acquired and integrated Securens and FSS.
CMS reduced its route network by 10% and says its investment cycle has been completed. It now expects capital expenditure to be half of its long-term average, with the FY27 ₹100-125 crore plan providing the numerical measure of that lower investment phase. CMS states that Tech and Payments had reached 20% of services revenue after the completed FY26 actions.
Price discussions with public-sector banks remain under way in H2 FY27 and are being led through the Indian Banks' Association (IBA). This means CMS has disclosed negotiations as an operating assumption rather than a completed pricing outcome. CMS also reported that currency supply and cash dispensed per automated teller machine (ATM) were 8% above their May low, which it described as recovering.
How is CMS changing its business mix?
CMS is moving its services mix toward a larger Tech and Payments contribution, which was 20% of services revenue in Q2 FY27, up from 16% in FY26 and 7% in FY22. Its FY30 aspiration is for Tech and Payments to account for 20-22%, while ATM Management Solutions is expected to represent 50-52% and Retail and Currency Logistics 26-28%.
ATM Management Solutions remained the largest component at 56% of services revenue in Q2 FY27, but its share fell from 58% in FY26 and 63% in FY22. Retail and Currency Logistics was 24% in Q2 FY27, compared with 26% in FY26 and 30% in FY22. The disclosed mix shows the faster increase in Tech and Payments has occurred alongside a lower percentage contribution from the two established categories.
CMS says growth capital will go to integrated fixed-fee contracts and Tech and Payments, while it will deploy no new capital for transaction-linked ATMs. Management also expects FY26 and FY27 order books to operate at full scale in FY28, with Tech and Payments growing from a larger base and an active bank request-for-proposal pipeline. These are stated operational plans, not quantified FY28 revenue guidance.
Got a follow-up? Ask IRIS
What do CMS's current segments show about the plan?
CMS's Managed Services segment delivered the faster Q2 FY27 revenue growth, with revenue increasing 19% year on year to ₹321 crore, compared with Cash revenue rising 2% to ₹404 crore. Managed Services revenue also rose 5% sequentially from ₹305 crore, while Cash revenue was flat sequentially from ₹403 crore. Segment totals are affected by inter-segment revenue and corporate costs, according to CMS.
Cash generated ₹77 crore of earnings before interest and tax (EBIT) in Q2 FY27, versus ₹59 crore a year earlier, lifting its EBIT margin to 19.1% from 14.9%. Its margin declined from 20.3% in Q1 FY27, when Cash EBIT was ₹82 crore. Managed Services EBIT was ₹34 crore in Q2 FY27, below ₹38 crore a year earlier, and its margin was 10.6% versus 14.0%.
CMS attributed the Managed Services EBIT movement to lower transaction-linked ATM revenue and higher depreciation from FY26 capital expenditure and the FSS acquisition. This contrasts with the company-wide H1 EBITDA-margin expansion to 27.0%, showing that the broader margin result includes contributions beyond the segment measure and is not directly equivalent to segment EBIT margins.
What could affect execution in H2 FY27?
CMS's H2 FY27 priorities are execution of Tech and Payments wins, public-sector bank price revisions and delivery of its recycler order book. Product revenue was lower year on year in H1 FY27 because deliveries on public-sector bank recycler orders won during the year are scheduled for H2. The timing of those deliveries therefore matters to the difference between services growth and total-revenue growth.
CMS reported that Q2 FY27 profit after tax was ₹81 crore, up 10.3% year on year but down 3.3% sequentially. It said Q1 FY27 profit after tax included a one-time deferred-tax gain, while Q2 reflected roughly ₹2.5 crore of lower other income after the buyback. H1 FY27 profit after tax was ₹165 crore, down 1.4% year on year despite the rise in EBITDA.
CMS also states it will reprice contracts that do not cover service costs or step away from them. CMS evaluated 15 acquisition opportunities in depth and completed two acquisitions, Securens and FSS, in FY26. Its stated capital-allocation approach is to return cash beyond the needs of the next 12 to 18 months through dividends and, where appropriate, buybacks; it reports ₹606 crore returned to shareholders since listing.
Conclusion
CMS's FY27 outlook combines a ₹2,650-2,750 crore services-revenue target with an EBITDA margin of about 27% and a lower ₹100-125 crore capital-expenditure plan. H1 FY27 services growth of 12.7% and EBITDA-margin expansion to 27.0% provide the reported starting point, while Managed Services grew faster than Cash in Q2 FY27 and Tech and Payments reached 20% of services revenue.
The next disclosures to watch are H2 FY27 execution of recycler orders, the outcome of IBA-led public-sector bank price revisions and delivery of Tech and Payments wins. CMS has said FY28 should include a full year of FY27-agreed price revisions, full-scale operation of the FY26 and FY27 order book, and depreciation easing as a share of revenue as capital expenditure returns to long-term levels.