










CMS Tech & Payments reaches ₹508 crore annualised revenue
Key highlights
- CMS Tech & Payments reached ₹508 crore of annualised revenue in Q2 FY27, versus ₹120 crore in FY22.
- Tech & Payments represented 20% of CMS Services Revenue in Q2 FY27, up from 16% in FY26.
- CMS reported ₹700 crore of H1 FY27 order wins, including HAWKAI and ALGO MVS public-sector-bank deployments.
- CMS guided for FY27 capital expenditure of ₹100 crore to ₹125 crore, compared with ₹351 crore in FY26.
powered by IRIS
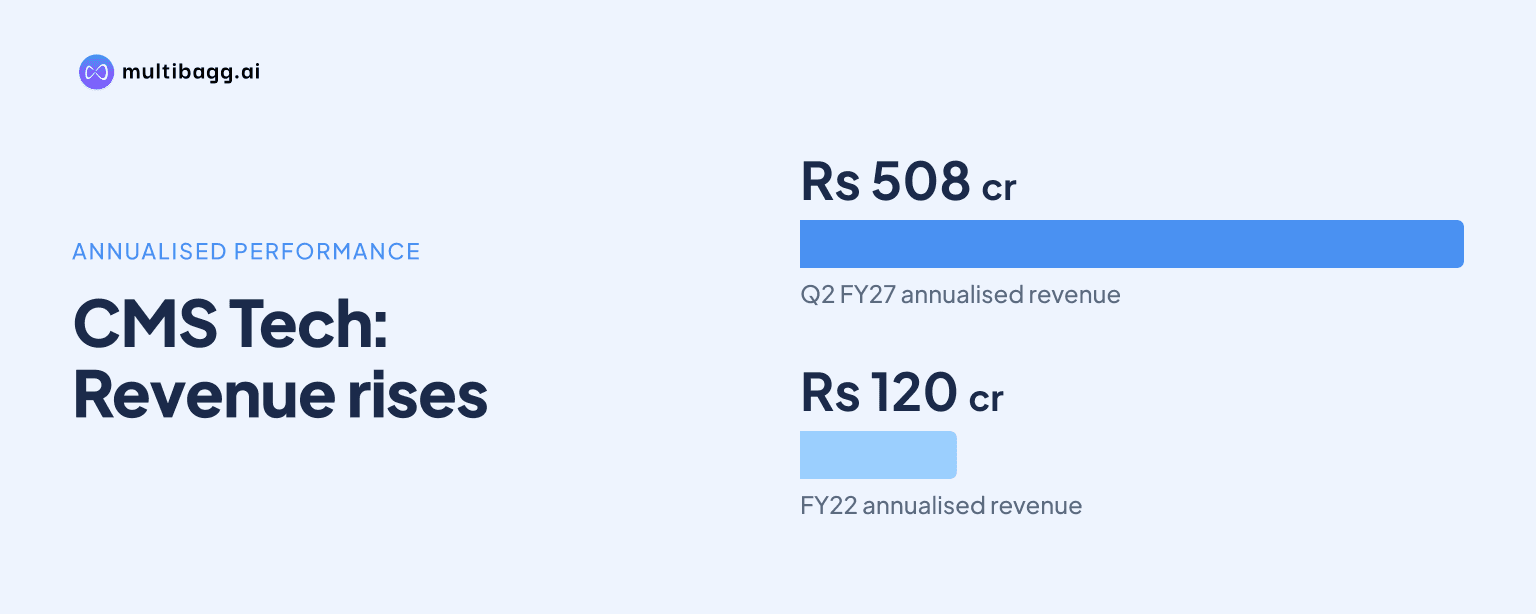
CMS Info Systems Limited’s Tech & Payments business reached ₹508 crore of annualised revenue in Q2 FY27, equal to 20% of Services Revenue and 4.2 times FY22’s ₹120 crore. The Q2 annualisation followed ₹644 crore of quarterly Services Revenue, while H1 FY27 included ₹700 crore of order wins in Tech & Payments solutions.
Know CMS Info Systems inside out
Results, valuation, peers and who's buying, in one view.
How large is CMS Tech & Payments business?
CMS Tech & Payments reached ₹508 crore of annualised revenue in Q2 FY27, compared with ₹442 crore on the same annualised basis in Q1 FY27. The ₹66 crore sequential increase took the business beyond the ₹500 crore annualised mark disclosed in the presentation.
The result was above earlier reported levels: Tech & Payments revenue was ₹120 crore in FY22, ₹245 crore in FY24, ₹263 crore in FY25 and ₹375 crore in FY26. CMS describes the Q2 FY27 annualised figure as 4.2 times the FY22 level. The presentation does not provide an FY23 figure, so the disclosed series does not show every financial year.
CMS labels FY22 through FY26 as actual figures, while Q1 and Q2 FY27 are annualised figures derived by multiplying quarterly revenue by four. Therefore, ₹508 crore is not disclosed as reported full-year FY27 revenue. It is an annualised run-rate based on Q2 FY27 performance.
What has changed in CMS revenue mix?
CMS Tech & Payments accounted for 20% of Services Revenue in Q2 FY27, up from 16% in FY26. The four-percentage-point change came as CMS reported ₹644 crore of Services Revenue in Q2 FY27, its highest quarterly Services Revenue for the fourth consecutive quarter.
Services Revenue rose 16.2% year on year in Q2 FY27 and 3.0% quarter on quarter from ₹625 crore in Q1 FY27. For H1 FY27, Services Revenue was ₹1,269 crore, up 12.7% year on year. CMS says the 20% Tech & Payments share is well ahead of its FY30 goal, although the supplied presentation pages do not state the numerical FY30 mix target.
The recent quarterly pattern also differs from FY26. Services Revenue moved from ₹571 crore in Q1 FY26 and ₹554 crore in Q2 FY26 to ₹625 crore and ₹644 crore, respectively, in the equivalent FY27 quarters. The larger Tech & Payments share therefore coincided with growth in the overall Services Revenue base rather than a disclosed fall in other service lines.
Which contracts support CMS Tech & Payments growth?
CMS reported ₹700 crore of H1 FY27 order wins, including marquee Tech & Payments solutions. The presentation does not provide contract durations, individual values or revenue-recognition schedules, so the disclosed order-win figure should not be treated as immediate revenue.
One H1 FY27 win was HAWKAI Branch RMS for a leading public-sector bank. CMS described it as its second large bank branch win, covering a central command centre and more than 8,000 branches. The presentation also identifies HAWKAI as one of the areas funded by FY26 capital expenditure.
A second named win was ALGO MVS for a leading public-sector bank, which CMS described as its third large bank on ALGO. The rollout covers 12,000 machines. These deployments establish the operational scale of the wins, but CMS did not state whether their rollout revenue is included in the ₹508 crore Q2 FY27 annualised figure.
Got a follow-up? Ask IRIS
How did CMS margins hold up as costs increased?
CMS reported an earnings before interest, tax, depreciation and amortisation, or EBITDA, margin of 26.7% in Q2 FY27, compared with 22.8% in Q2 FY26. H1 FY27 EBITDA margin was 27.0%, up 290 basis points year on year, while Q2 FY27 EBITDA was ₹173 crore, up 24.8% year on year.
CMS said wage and fuel inflation affected costs during the quarter. Minimum wages increased by 6% to 60% across key states, while fuel prices rose 8% during the preceding six months. CMS said revised pricing was in place across most private-bank automated teller machine, or ATM, contracts and retail customers, while public-sector-bank repricing negotiations remained under way through an Indian Banks’ Association committee.
CMS attributed part of its cost response to network efficiency and automation. It said machine-learning-based optimisation lifted network efficiency by 10%, while artificial-intelligence agents processed incidents at 99% accuracy and closed more than 60% of monitoring alerts across more than 25,000 sites. The business mix change, with Tech & Payments at 20% of Services Revenue, was also listed among margin factors.
What execution milestones should CMS meet next?
CMS said the FSS CashTech integration was fully completed, with all customer contracts novated to CMS and the business integrated. Final closing steps were stated to be on track for January 2027. This is an operational milestone, rather than a quantified revenue or cost-synergy forecast.
For FY27, CMS guided for capital expenditure of ₹100 crore to ₹125 crore, or about 4% of revenue, mainly for Tech & Payments rollouts. This is below the ₹351 crore spent in FY26, when CMS funded fixed-price ATM contract rollouts and development of HAWKAI and ALGO MVS. Management said FY27 capital expenditure is about 50% of long-term levels and expects depreciation as a share of revenue to ease from FY28 as revenue from these investments builds.
CMS also reported ₹473 crore of net cash as of 30 September 2026 and H1 FY27 operating cash flow of ₹177 crore, compared with an outflow of ₹117 crore in H1 FY26. H1 FY27 operating cash flow equalled 51% of EBITDA, versus negative 39% in the prior-year period. These figures provide the reported cash-flow and balance-sheet context for planned FY27 rollout spending.
Conclusion
CMS’s Q2 FY27 disclosure shows Tech & Payments at ₹508 crore of annualised revenue, 4.2 times the FY22 level and representing 20% of Services Revenue. The mix shift occurred alongside 16.2% year-on-year Services Revenue growth, a 26.7% Q2 FY27 EBITDA margin and named public-sector-bank deployments across more than 8,000 branches and 12,000 machines.
The next disclosed points to watch are CMS’s January 2027 final closing for FSS CashTech, progress in public-sector-bank contract repricing and execution of the ₹100 crore to ₹125 crore FY27 capital-expenditure plan. Management’s expectation that depreciation as a share of revenue will ease from FY28 depends on revenue building from those investments.