










DCX Systems Limited Outlook Hinges on 2027 Profit Recovery
Key highlights
- DCX Systems reported Q2 FY2027 revenue of ₹148.09 crore, down 23% year on year.
- Q2 FY2027 net loss narrowed to ₹0.26 crore and loss per share improved to ₹0.02 from ₹0.81.
- One analyst forecasts ₹8.77 billion of 2027 revenue, a stated 56% improvement from the last 12 months.
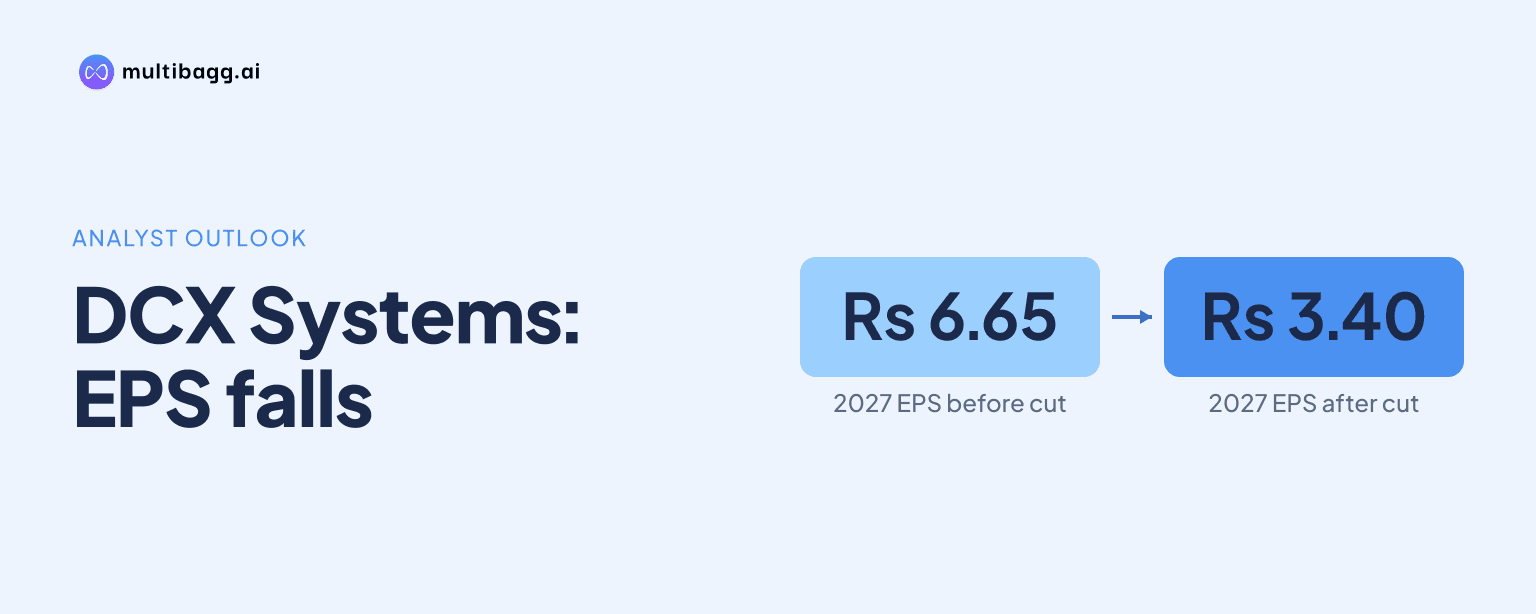
- The sole analyst's 2027 EPS forecast was cut from ₹6.65 to ₹3.40, while the price target was raised to ₹192.
powered by IRIS
DCX Systems Limited's outlook through November 2027 depends on whether a forecast return to ₹3.40 statutory earnings per share and ₹8.77 billion of 2027 revenue can offset six consecutive loss-making quarters. The latest Q2 FY2027 result narrowed the loss to ₹0.26 crore, but revenue fell 23% year on year to ₹148.09 crore.
What did DCX Systems report in Q2 FY2027?
DCX Systems reported revenue of ₹148.09 crore and a consolidated net loss of ₹0.26 crore in Q2 FY2027, showing a sharply narrower loss but lower revenue than a year earlier. The reported loss per share was ₹0.02, compared with a ₹0.81 loss per share in Q2 2026. Revenue of ₹1.48 billion was down 23% year on year.
The result therefore presents two contrasting signals. The loss narrowed by 97% from the prior-year quarter, based on the supplied figures, but the revenue decline means the company has not yet demonstrated a sustained recovery in demand or scale. Social-media discussion also noted that DCX Systems had posted negative results for six consecutive quarters and a loss after tax of ₹8.92 crore over the latest six-month period.
Why are 2027 earnings forecasts being watched closely?
The 2027 forecast is important because the sole analyst cited expects DCX Systems to move from a loss to statutory earnings of ₹3.40 per share. That forecast compares with a net loss per share of ₹0.69 in the preceding year, making profitability execution the central issue for the stock outlook.
However, the earnings estimate was reduced after the latest results. The analyst had previously expected ₹6.65 per share for 2027, before lowering the projection to ₹3.40 per share. Revenue expectations were also trimmed from ₹8.92 billion to ₹8.77 billion, although the latter would still represent a stated 56% improvement from the last 12 months. Forecast growth is stronger than the cited 17% growth outlook for India's aerospace and defence industry, but it remains a forecast based on one analyst.
What does the ₹192 price target mean for DCX Systems?
The ₹192 target reflects a positive valuation view from one analyst, not a broad market consensus. The target was raised 28% even as the analyst reduced the 2027 earnings forecast, indicating that the analyst did not view the earnings revisions as permanently damaging to the company's value.
The supplied data puts the potential upside from the target at 25.29% and labels the single-analyst recommendation as Strong Buy. This needs to be read alongside a different assessment from MarketsMojo, which assigned a Strong Sell grade and a Mojo Score of 9.0 as of 15 November 2026. The gap between these views highlights that the investment case rests on a turnaround that is not yet visible in the reported earnings record.
Got a follow-up? Ask IRIS
Which operating indicators could confirm a turnaround?
A turnaround would be more credible if DCX Systems records positive operating margins, excluding other income, for two consecutive quarters and delivers quarterly revenue above ₹200 crore with positive year-on-year growth. These were identified in the supplied discussion as practical thresholds for business stabilisation rather than as achieved results.
Investors will also be watching whether losses stop accumulating after the six-quarter streak cited in the discussion. MarketsMojo described the financial trend as negative, citing persistent operating losses, low profitability metrics and weak long-term fundamental strength. At the same time, the stock's short-term movements have been volatile: it was reported to have risen 16.86% over one week and 5.49% over one month, while its one-year return was negative 20.07%.
What should investors monitor before November 2027?
Investors should monitor the next reported results, the path to positive operating profitability, revenue consistency and any further revision to the sole analyst's forecasts. DCX Systems is scheduled to release its next earnings report on 11 February 2027, according to the supplied information, making that event an early test of whether the Q2 loss reduction can continue.
The available estimates point to substantial expansion, with revenue forecast to grow at average annual rates of 27% to 30% over the next three years in different summaries. Yet the reported Q2 revenue contraction and the reduction in EPS expectations show why these projections should be treated as milestones to be verified in results, rather than as a completed recovery.
Conclusion
DCX Systems enters the period through November 2027 with a divided outlook. The latest quarterly loss was much smaller, and the lone analyst expects a return to profit alongside strong revenue growth. Against that, the company has a reported sequence of six loss-making quarters, declining Q2 revenue and a sharply reduced 2027 EPS estimate.
The immediate event to watch is the scheduled 11 February 2027 earnings release. Beyond that, the key tests are whether DCX Systems can produce positive operating margins for two straight quarters and sustain quarterly revenue above ₹200 crore with year-on-year growth, while avoiding further cuts to the ₹3.40 EPS forecast.