










Envirotech Systems targets Rs 300 crore as capacity ramps
Key highlights
- Envirotech Systems targets approximately Rs 300 crore of revenue over the next three to four years.
- The fire-rated-door line has capacity for about 36,000 doors and about Rs 72 crore of annual revenue at full utilisation.
- D-3 is a planned 1,00,000-square-foot facility that management says could contribute up to Rs 300 crore of revenue.
- H1 FY2027 profit after tax was Rs 10.20 lakh, compared with Rs 5.9757 crore in H1 FY2026.
powered by IRIS
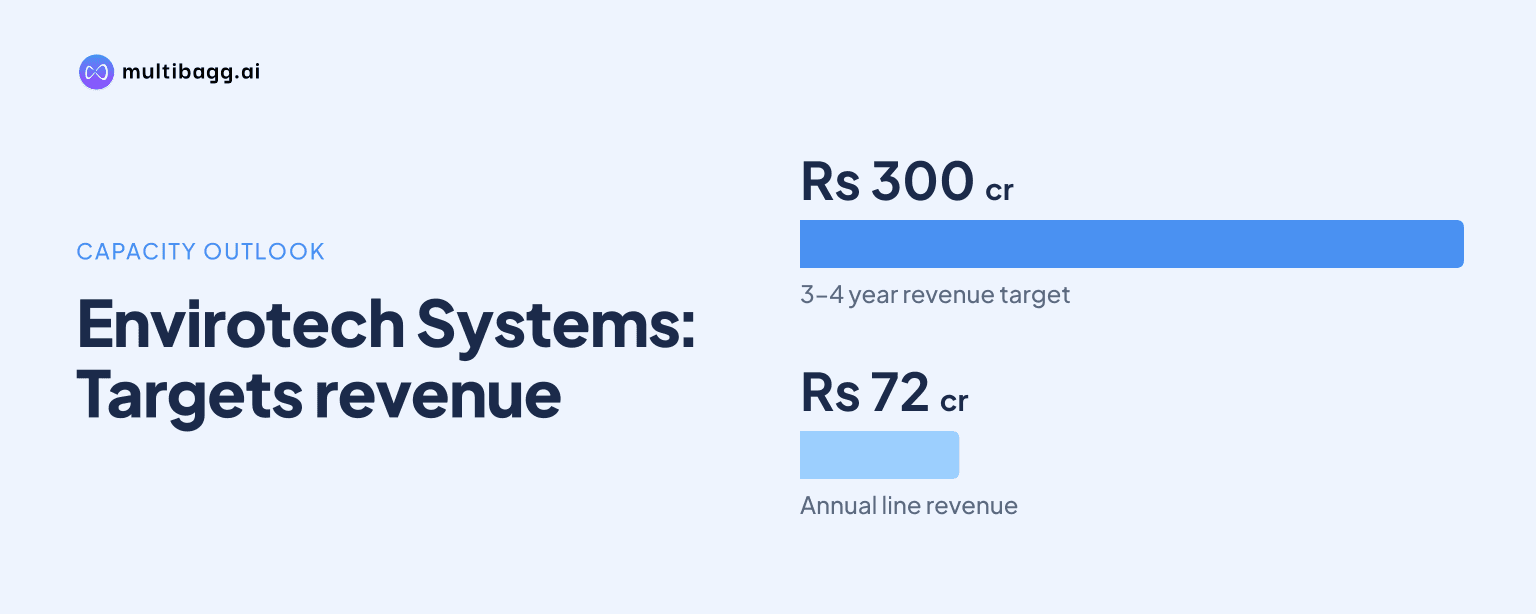
Envirotech Systems Limited is targeting approximately Rs 300 crore of revenue over the next three to four years, with management citing a 36,000-door annual fire-rated-door line worth about Rs 72 crore at full utilisation and the approved D-3 facility, despite H1 FY2027 profit after tax of Rs 10.20 lakh.
Know Envirotech Systems inside out
Results, valuation, peers and who's buying, in one view.
How will Envirotech Systems pursue Rs 300 crore revenue?
Envirotech Systems plans to pursue approximately Rs 300 crore of revenue over the next three to four years through expanded manufacturing capacity, the D-3 facility and its order pipeline. Managing Director Manoj Kumar Gupta described the programme as a substantial capacity expansion, while the company said its active order book stood at Rs 31 crore.
The Rs 300 crore figure is management's medium-term aspiration, not reported revenue or a forecast for a specified financial year. Management said the fire-rated-door line could generate about Rs 72 crore annually at full utilisation, while the D-3 facility could contribute up to Rs 300 crore once fully operational; the presentation does not say these two capacity figures should be added together.
Management is also striving for around 20% top-line growth in FY2026-27 after describing sales as being in a transitory period of consolidation. Its update sets out a three-to-five-year roadmap based on capacity additions, D-3 execution and a growing order pipeline, but warns that FY2027 and FY2028 expectations are based on current assumptions and actual outcomes may differ materially.
What will the fire-rated-door line contribute to Envirotech Systems?
Envirotech Systems' automated fire-rated-door plant has annual capacity of about 36,000 doors and could produce approximately Rs 72 crore of revenue at 100% utilisation. The company said initial utilisation will be 20% in FY2026-27, followed by a structured ramp-up across FY2027-28 and FY2028-29.
At 20% utilisation, the line will operate materially below its 36,000-door nameplate capacity during FY2026-27. Management said commissioning and upfront operating costs from new lines are passing through the current financial year, while lower initial utilisation limits the production base over which fixed costs can be absorbed.
The fire-door line represents one part of the stated revenue plan rather than the whole Rs 300 crore objective. Its Rs 72 crore full-utilisation potential is less than one-quarter of the target, leaving D-3 and other growth initiatives, including soundproof windows and doors, a business-to-consumer vertical and defence-industry activity, as additional elements in management's roadmap.
Got a follow-up? Ask IRIS
When is Envirotech Systems' D-3 facility expected to contribute?
Envirotech Systems expects its approved D-3 facility to be completed within 12 months and to begin contributing meaningfully in FY2028-29 and FY2029-30. The planned site covers 1,00,000 square feet and comprises a basement plus four floors, with construction and commissioning described as on schedule.
Management said D-3 could contribute up to Rs 300 crore of revenue when fully operational. That is a capacity-based indication rather than a disclosed revenue forecast for FY2028-29 or FY2029-30, because the presentation gives no expected utilisation rate, capital cost or annual production schedule for the facility.
The facility's completion timetable makes timely construction a key condition for the three-to-four-year revenue ambition. Management linked the target to D-3 execution, expanding capacities and the Rs 31 crore order book, while its forward-looking disclaimer specifically covers expectations for FY2027 and FY2028.
Why did Envirotech Systems' H1 FY2027 profitability decline?
Envirotech Systems' H1 FY2027 profit after tax fell to Rs 10.20 lakh from Rs 5.9757 crore in H1 FY2026 as total revenue declined and expenses increased. Management attributed near-term margin pressure to upfront fixed, operational and commissioning costs associated with ramping new manufacturing lines.
Total revenue decreased 5.46% year on year, while total expenses increased by Rs 6.2887 crore. Cost of materials consumed rose to Rs 14.0616 crore from Rs 13.5316 crore, employee benefit expense increased to Rs 4.745 crore from Rs 3.794 crore, and other expenses rose to Rs 3.8143 crore from Rs 2.4835 crore.
Depreciation and amortisation increased to Rs 2.0105 crore in H1 FY2027 from Rs 19.65 lakh in H1 FY2026. The presentation reported earnings before interest, tax, depreciation and amortisation, or EBITDA, margin of 11.40%, down from 33.24%, while profit-after-tax margin declined to 0.41% from 22.76%.
Receivables stood at Rs 22 crore in November 2026, largely because of long-duration projects and milestone-based billing cycles, according to management. The company also said elevated inventory was intended to support new-line commissioning and hedge raw-material price volatility, but did not disclose inventory value, receivable days or collection-period data.
Conclusion
Envirotech Systems' Rs 300 crore aspiration depends on converting newly installed and planned capacity into production and sales. The fire-rated-door line has stated potential of about Rs 72 crore at full utilisation, while D-3 could contribute up to Rs 300 crore once fully operational, against H1 FY2027 total revenue of Rs 24.8165 crore.
The disclosed milestones are the fire-door line's ramp from 20% utilisation in FY2026-27 through FY2028-29, D-3 completion within 12 months and its intended contribution in FY2028-29 and FY2029-30. Management's aim of around 20% FY2026-27 top-line growth, alongside the Rs 31 crore order book, Rs 22 crore November 2026 receivables and margin trend, will provide the next reported indicators of execution.