










CapitalTrust MSME AUM reaches Rs 279 crore in Q2 FY27
Key highlights
- CTL's MSME AUM reached Rs 279 crore in Q2 FY27, up 36% quarter on quarter from Rs 205 crore.
- Approximately Rs 212 crore, or 76%, of September 2026 MSME AUM carried no credit risk to CTL.
- New-model MSME loans reported collection efficiency above 99%, with loans more than 90 days past due below 0.5%.
- More than 100 unutilised branches could add approximately Rs 30 crore of monthly MSME originations.
powered by IRIS
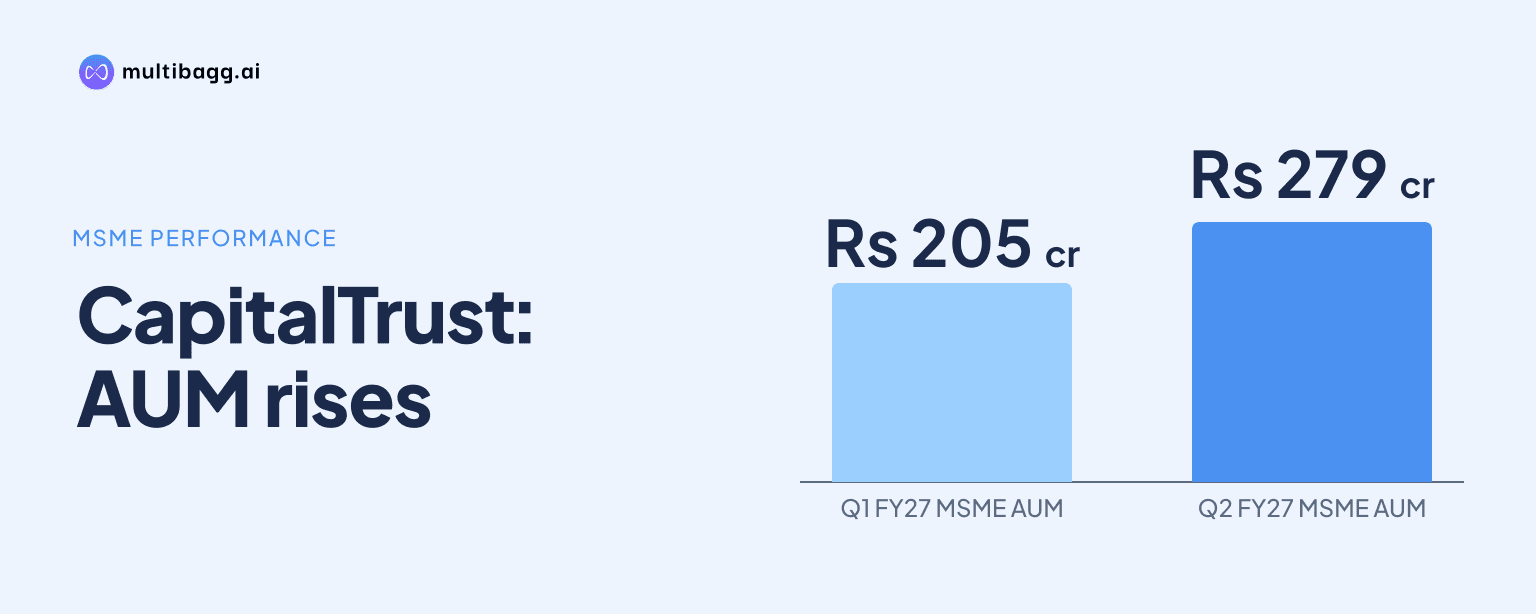
CapitalTrust (CTL) reported Rs 279 crore of micro, small and medium enterprise (MSME) assets under management (AUM) in Q2 FY27, up 36% quarter on quarter, while new-model loans had collection efficiency above 99%. CTL said more than 100 unutilised branches could support approximately Rs 30 crore of additional monthly originations as it seeks more lending partners.
Know Capital Trust inside out
Results, valuation, peers and who's buying, in one view.
What is CTL's partner-led MSME lending model?
CTL provides the distribution and servicing layer, while lending partners sanction, disburse and retain the loans on their balance sheets; the presentation also classifies 100% of the MSME business as Priority Sector Lending. CTL sources borrowers, completes know-your-customer (KYC) work, conducts field verification, collects repayments and provides continuing service through its branches, staff and training. Partners set credit policy, undertake final KYC and account opening, and handle regulatory reporting.
The operating network covered more than 250 branches across 10 states and 74 districts, supported by more than 1,000 field staff. CTL identified Suryoday and Kaleidofin as live business-correspondent partners. The structure separates customer acquisition and collections from lending exposure, which is why the presentation categorises much of the MSME portfolio as carrying no credit risk to CTL.
How fast has CTL's MSME AUM grown?
CTL's MSME AUM rose to Rs 279 crore in Q2 FY27 from Rs 205 crore in Q1 FY27 and Rs 124 crore in Q2 FY26. The presentation states a 36% quarter-on-quarter increase and 2.3 times year-on-year growth. The portfolio did not increase in every intervening quarter, falling from Rs 124 crore in Q2 FY26 to Rs 101 crore in Q3 FY26 before rising in the following three quarters.
The increase from Rs 137 crore in Q4 FY26 to Rs 279 crore in Q2 FY27 added Rs 142 crore over two quarters. CTL also reported approximately Rs 35 crore of monthly MSME disbursements. AUM is a stock measure while monthly disbursement is a flow measure, and the presentation does not state how much of each month's disbursal remains in the reported Rs 279 crore portfolio.
How much MSME credit risk does CTL retain?
CTL reported that approximately Rs 212 crore, or 76%, of its Rs 279 crore MSME AUM in September 2026 was zero-risk, meaning there was no credit risk to CTL. The remaining approximately Rs 67 crore, or 24%, was described as capped-risk and legacy. This split reflects the partner-led model, under which the partner holds the loan, rather than indicating that all MSME activity has the same risk characteristics.
Portfolio-quality data apply specifically to new-model loans, defined as partner-led MSME loans disbursed in the last 12 months. For that cohort, collection efficiency exceeded 99%, loans more than 30 days past due were below 1%, and loans more than 90 days past due were below 0.5%. These figures are cohort measures and are not presented as performance measures for the Rs 67 crore capped-risk and legacy portion.
Got a follow-up? Ask IRIS
How can CTL add Rs 30 crore of monthly originations?
CTL said more than 100 unutilised branches across 10 states could originate approximately Rs 30 crore of additional MSME loans a month. The indicated capacity is approximately Rs 25 lakh per unutilised branch each month. Applying that branch-level capacity across more than 100 locations explains the aggregate headroom, although the presentation does not identify the exact number of branches to be activated.
Management identified adding partners using spare branch capacity as its H2 priority. Under this plan, the existing branch and field-service platform would undertake sourcing, verification and collection, while a new partner would provide credit policy, sanction decisions, disbursement and balance-sheet funding. The approximately Rs 30 crore of incremental monthly capacity is potential origination capacity, not a disclosed target for AUM, income or profit.
How are CTL's MSME loans sourced and processed?
CTL uses a nine-step process with a named owner at every stage, from lead generation to a post-disbursal welcome call. A relationship officer canvasses and verifies the customer's mobile number through a one-time password, completes Aadhaar quick-response-code onboarding and pulls bureau data. A credit officer verifies the home, business, income and cash flow, followed by a Head Office credit check and branch-head sign-off before the case goes to the partner.
The product is an income-generating business loan of Rs 50,000 to Rs 2 lakh, with an 18-to-36-month tenure and a starting rate of interest of 26%. Repayments can use National Automated Clearing House mandates, Bharat Bill Payment System, Unified Payments Interface or static quick-response codes, followed by physical cash collection. Before disbursement, clients complete e-signing and e-NACH setup, and Head Office operations conducts final checks before crediting the client's bank account.
Every stage is captured in the Capital Sales App with a user ID and time stamp. The field-verification step includes assessment of cash flow and fixed-obligation-to-income ratio, while telephonic verification by Head Office credit reassesses cash flow. This process assigns lead generation, onboarding and bureau checks to relationship officers, disbursement to Head Office operations, and the final welcome call to customer care.
Conclusion
CTL's Rs 279 crore MSME AUM in Q2 FY27 combines a partner-held lending structure with an in-house sourcing, verification and collection network. The portfolio increased from Rs 205 crore in Q1 FY27, while approximately Rs 212 crore of September 2026 MSME AUM was classified as carrying no credit risk to CTL. The above-99% collection-efficiency figure applies to the specified new-model loan cohort disbursed over the preceding 12 months.
The next disclosed item to watch is management's H2 priority of adding partners through spare branch capacity. CTL estimates that more than 100 unutilised branches can support approximately Rs 30 crore of additional monthly originations, compared with approximately Rs 35 crore of current monthly disbursements. The presentation does not name additional partners, state branch-activation dates, or provide an AUM target from this capacity plan.