










Faze 3 Q2 income rose 29% as EBITDA margin reached 13.29%
Key highlights
- Faze 3 reported Q2 FY27 total income of Rs 267.82 crore, up 29.14% year on year.
- Faze 3's Q2 FY27 EBITDA margin rose to 13.29% from 11.52% in Q1 FY27.
- Faze 3 recorded Q2 FY27 profit after tax of Rs 15.46 crore versus a Rs 5.22 crore loss in Q2 FY26.
- Faze 3's trailing-12-month September 2026 income was Rs 1,012.6 crore and EBITDA margin was 11.93%.
powered by IRIS
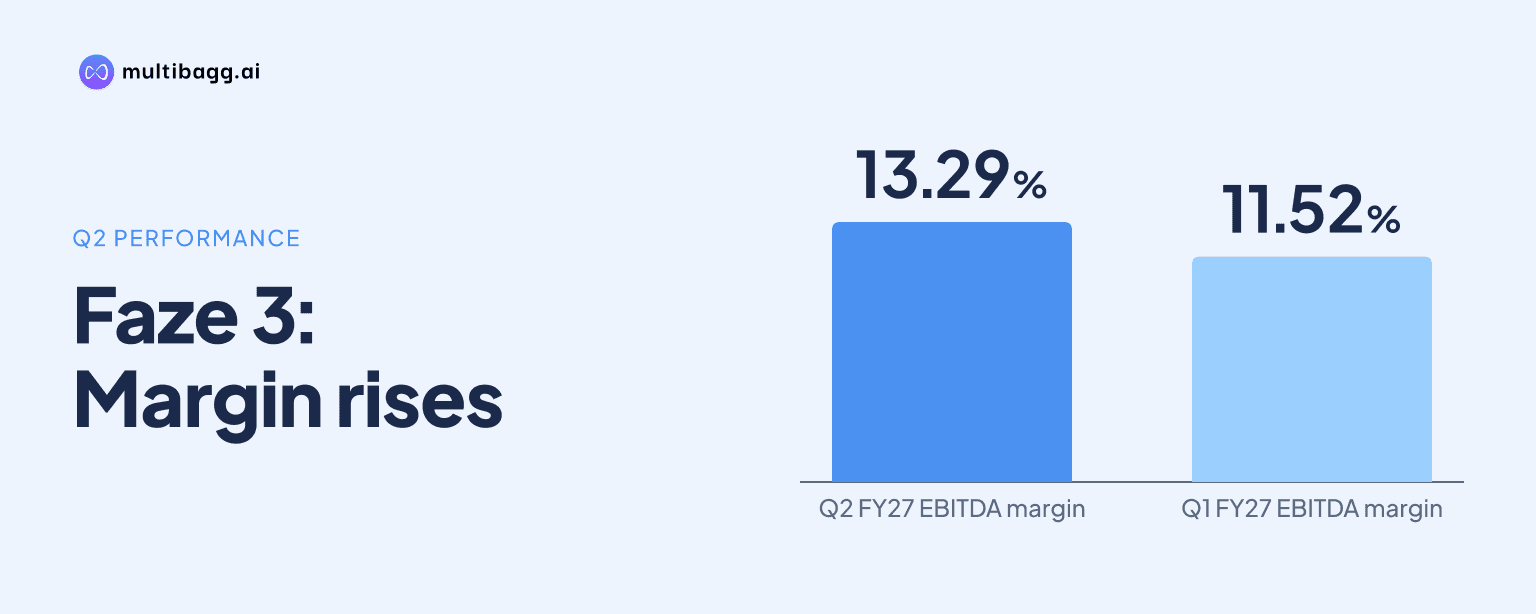
Faze 3 Limited reported record September-quarter total income of Rs 267.82 crore in Q2 FY27, up 29.14% year on year, while EBITDA margin rose to 13.29% from 11.52% in Q1 FY27. Management attributed the sequential recovery to higher revenue, operating leverage, customer repricing and better US dollar-Indian rupee realisation.
Know Faze Three inside out
Results, valuation, peers and who's buying, in one view.
How did Faze 3 perform in Q2 FY27?
Faze 3 delivered its highest-ever September-quarter total income in Q2 FY27, reporting Rs 267.82 crore versus Rs 207.39 crore in Q2 FY26 and Rs 235.10 crore in Q1 FY27. Total income increased 29.14% year on year and Rs 32.72 crore sequentially. H1 FY27 total income was Rs 502.9 crore, up 18.9% over H1 FY26.
Earnings before interest, tax, depreciation and amortisation, or EBITDA, reached Rs 35.59 crore, compared with Rs 27.09 crore in Q1 FY27 and Rs 5.52 crore in Q2 FY26. Profit before tax was Rs 20.97 crore and profit after tax was Rs 15.46 crore, compared with Rs 13.37 crore and Rs 9.64 crore, respectively, in the preceding quarter.
The move to profit in Q2 FY27 contrasted with a Rs 5.22 crore net loss in Q2 FY26. Management said EBITDA and profit growth percentages were not comparable because the year-earlier base was unusually low. Cash profit rose to Rs 24.31 crore from Rs 17.71 crore in Q1 FY27, while cash-profit margin increased to 9.08% from 7.53%.
What drove Faze 3's EBITDA margin recovery?
Faze 3's EBITDA margin rose by 1.77 percentage points sequentially to 13.29% in Q2 FY27 from 11.52% in Q1 FY27. Management cited four drivers: higher revenue and operating leverage, repricing and upcharges with customers, and better US dollar-Indian rupee realisation. It said repricing actions initiated after the Q1 cost pressure were flowing through during the second quarter.
Management said Q1 FY27 margin was affected by an input-cost surge following the West Asia crisis. For H2 FY27, it said cotton, polyester, chemicals, fuel, packaging and logistics costs remained elevated against pre-crisis levels, partly offset by US dollar-Indian rupee realisation. Repricing and upcharge requests with customers remained under way at the time of the presentation.
The year-on-year comparison also includes a separate effect in Q2 FY26. EBITDA margin was 2.66% in that quarter because of a one-time mark-to-market impact on US dollar-Indian rupee forwards and then-prevailing 50% US tariffs on India, according to Faze 3. The sequential move from Q1 FY27 therefore measures the recovery after the input-cost surge, while the annual comparison includes the affected prior-period base.
Got a follow-up? Ask IRIS
How does Faze 3's quarterly recovery compare with trailing results?
Faze 3 reported trailing-12-month total income of Rs 1,012.6 crore at September 2026, compared with Rs 932.8 crore in FY26. Trailing-12-month EBITDA was Rs 120.9 crore and the margin was 11.93%, up from 9.89% in FY26. The 13.29% margin in Q2 FY27 was therefore above the trailing-12-month result.
The annual figures show income growth alongside a margin decline before the latest recovery. Total income increased from Rs 701.7 crore in FY25 to Rs 932.8 crore in FY26, while EBITDA margin fell from 13.14% to 9.89%. Faze 3 presented six-year compound annual growth rates of 22% for revenue and 21% for EBITDA through FY26.
Profitability also improved in the trailing period. Trailing-12-month profit after tax was Rs 51.1 crore, equal to a 5.05% margin, against Rs 33.6 crore and a 3.60% margin in FY26. Earnings per share rose to Rs 20.8 from Rs 13.8, while cash earnings per share increased to Rs 34.1 from Rs 26.5.
What is Faze 3 management expecting for FY27 and FY28?
Faze 3 management expects FY27 revenue growth of around 20% or more, supported by H1 FY27 volume momentum and a strong order book for H2 FY27. Management also expects momentum through FY27 and FY28 alongside inflation-led pricing growth similar to the FY22-FY23 cycle. These are management expectations rather than reported outcomes.
Management expects FY28 revenue momentum to be stronger than FY27 if the overhang from the West Asia conflict subsides. It expects margin recovery to be aided by a substantial reduction in current raw-material prices, effective product upcharges, improved US dollar-Indian rupee realisation and further operating leverage. The extent to which customer repricing offsets elevated cotton, polyester, chemical, fuel, packaging and logistics costs remains unresolved.
Faze 3 received production-linked incentive approval on July 1, 2026, with benefits expected to accrue from FY28. Its FY27 capital expenditure plan is intended to add product capabilities by Q1 FY28, and management expects the major capital-expenditure cycle to conclude in FY27. It said this could make at least 40% to 50% of cash flow from operations available for alternative uses.
Conclusion
Faze 3's Q2 FY27 result combined a 29.14% increase in total income to Rs 267.82 crore with a 1.77-percentage-point sequential EBITDA-margin recovery and profit after tax of Rs 15.46 crore. Management attributed the change to operating leverage, customer repricing and currency realisation, rather than revenue growth alone.
The next disclosures should indicate whether FY27 revenue growth reaches management's 20%-plus expectation and whether customer upcharges offset elevated input costs. Other disclosed milestones are completion of the FY27 capital-expenditure cycle, new product capabilities by Q1 FY28 and the expected start of production-linked incentive benefits in FY28.