










Glottis discloses Rs 60 crore interest-free director loans
Key highlights
- Glottis disclosed up to Rs 60 crore of unsecured, interest-free loan capacity from two promoter-managing directors.
- Each promoter-director facility is capped at Rs 30 crore and can be drawn in one or more tranches.
- Each loan tranche is repayable within up to 5 years from its disbursement date.
- Glottis reported Rs 49.75 crore of cash and bank balances at September 30, 2026.
powered by IRIS
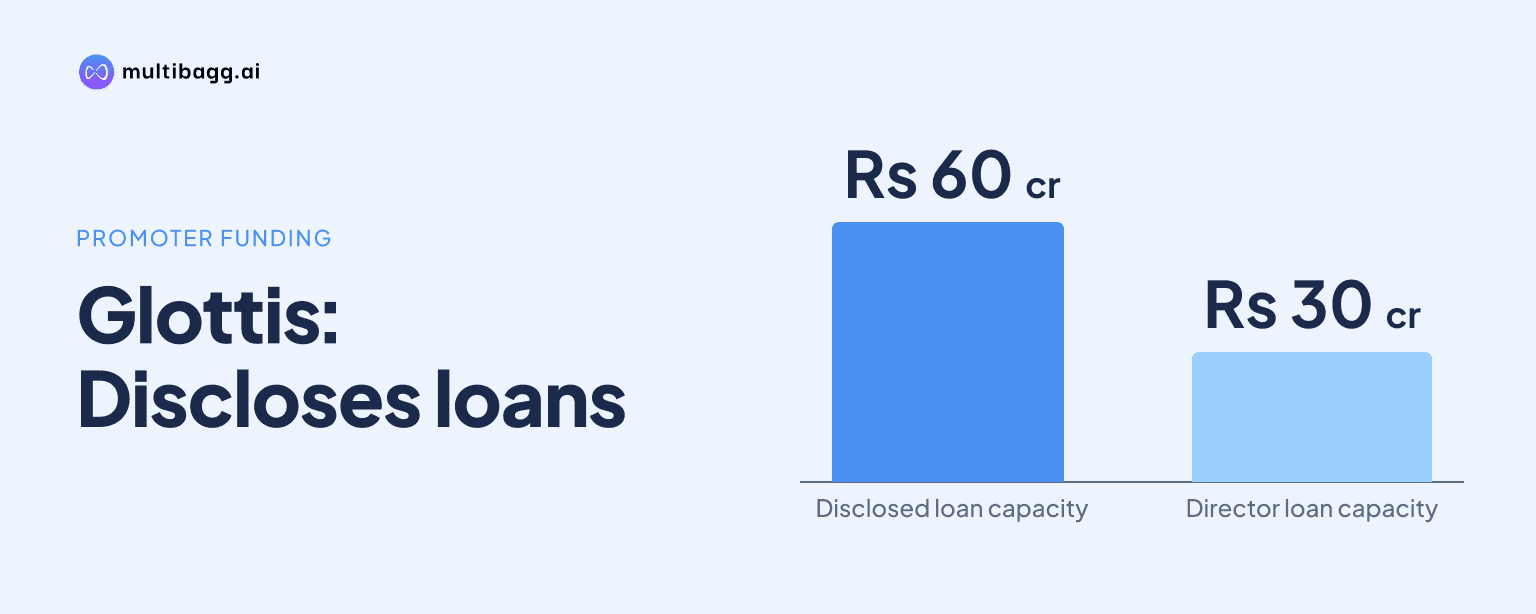
Glottis Limited has disclosed up to Rs 60 crore in unsecured, interest-free loan facilities from its two promoter-managing directors, split equally at Rs 30 crore each and repayable within up to five years of every tranche's disbursement. Glottis says both related-party transactions are not at arm's length because they carry no interest.
Know Glottis inside out
Results, valuation, peers and who's buying, in one view.
How much can Glottis borrow from its managing directors?
Glottis can borrow up to Rs 60 crore in aggregate under two separate facilities, with up to Rs 30 crore available from Kuttappan Manikandan and up to Rs 30 crore from Ramkumar Senthilvel. The agreements identify both lenders as promoters and managing directors. Each facility can be disbursed in one or more tranches, so the Rs 60 crore is a contractual maximum rather than a reported funded balance.
The stated purpose of both facilities is short-term and long-term working-capital requirements and general business purposes. Glottis did not disclose a first drawdown date, any amount outstanding under either facility, or a timetable allocating the potential Rs 60 crore to specific working-capital uses. The agreements therefore establish funding availability, while leaving the amount and timing of actual borrowing undisclosed.
The two facilities are identical in their disclosed Rs 30 crore limits, security and interest terms. Both lenders are reported to hold 3,38,94,180 equity shares of Rs 2 each, aggregating to Rs 67.78 crore, and each is stated to hold 36.68% of Glottis's equity share capital. The filing does not state that either lender is jointly liable for the other's facility.
What are the repayment and interest terms for Glottis?
Glottis must repay each tranche within up to five years from that tranche's disbursement date, and no interest is payable under either facility. The five-year tenure applies separately to each drawdown rather than being presented as one common deadline for the full Rs 60 crore. The loans are unsecured, meaning the agreements disclose no collateral for either promoter-director lender.
Glottis and each lender can extend a tranche's tenure or prepay it through mutual agreement, with no additional charges stated. The filing does not provide a fixed instalment schedule, compulsory amortisation amount, financial covenant or prepayment notice period. This means repayment timing may differ between tranches, subject to the maximum stated five-year period and any mutual extension.
The zero-interest feature is the mechanism that distinguishes the facilities in Glottis's related-party disclosure. Glottis does not quantify an interest saving, state a comparable bank borrowing rate, or estimate a profit-and-loss effect for the period ended September 30, 2026. The disclosure instead confines the financial terms to the Rs 30 crore limits, unsecured status, nil interest and repayment period.
Why does Glottis classify the loans as related-party transactions?
Glottis classifies both loans as related-party transactions because Kuttappan Manikandan and Ramkumar Senthilvel are each promoters and managing directors holding 36.68% of its equity share capital. The company cites the proviso to Regulation 2(1)(zc) of the Securities and Exchange Board of India (Listing Obligations and Disclosure Requirements) Regulations, 2015 for that classification.
Glottis explicitly says neither transaction is at arm's length because the facilities are interest-free. That conclusion is based on the nil-interest term, not on the loans' Rs 30 crore size, their unsecured structure or their five-year repayment provision. The company did not disclose a third-party benchmark rate, an independent valuation of the interest concession, or a comparison with commercial borrowing terms.
The agreements state that no shares are being issued to either lender, so issue price and share class details are not applicable. Glottis also reported no other disclosures regarding director nominees or potential conflicts of interest arising from the agreements. Those statements sit alongside the two equal loan limits and the lenders' equal disclosed 36.68% shareholdings.
Got a follow-up? Ask IRIS
How do the director facilities compare with Glottis's public-issue funds?
Glottis's Rs 60 crore director-loan capacity is separate from the Rs 160 crore gross proceeds reported from its public issue on October 3, 2025. As of September 30, 2026, the company reported Rs 90.10 crore of gross proceeds utilised, including Rs 62.64 crore for capital expenditure, Rs 12.79 crore for general corporate purposes and Rs 14.67 crore for issue expenses.
The public-issue statement separates its uses into capital expenditure and general corporate purposes, whereas the two director facilities are designated for working capital and general business purposes. Glottis reported no deviation or variation in the use of public-issue funds for the quarter ended September 30, 2026. The filing does not say the Rs 60 crore facilities were arranged because public-issue proceeds were insufficient or unavailable.
Net proceeds were revised to Rs 145.33 crore from Rs 145.20 crore during the quarter ended March 31, 2026, after actual issue expenses came in Rs 13.12 lakh below the offer-document estimate. Glottis said the difference was adjusted to general corporate purposes. The Rs 75.43 crore net-proceeds utilisation at September 30, 2026 was therefore below the revised Rs 145.33 crore allocation.
What does Glottis's September cash balance show?
Glottis reported total cash and bank balances of Rs 49.75 crore at September 30, 2026, compared with Rs 9.51 crore at March 31, 2026. The period-end balance increased by Rs 40.24 crore. Forex cards accounted for Rs 40.11 crore of the September 30 balance, while deposits with original maturity below three months were Rs 8.22 crore.
Cash and bank balances are reported assets at September 30, 2026, whereas the Rs 60 crore director facilities are maximum borrowing commitments that can be drawn in tranches. The filing does not state whether any part of the facilities had been drawn and included in the Rs 49.75 crore balance. It also does not link the higher cash balance to either promoter-director agreement.
Conclusion
Glottis has established up to Rs 60 crore of potential promoter-director funding through two equal, unsecured and interest-free facilities. The arrangements can support working capital and general business purposes, but the company classifies them as related-party transactions that are not at arm's length because no interest is charged. The facilities sit alongside Rs 145.33 crore of revised net public-issue proceeds, of which Rs 75.43 crore had been utilised by September 30, 2026.
The next disclosures to watch are any tranche drawdowns, outstanding loan balances, repayment arrangements or mutually agreed extensions, since each tranche has a tenure of up to five years from disbursement. Glottis's public-issue utilisation also remains relevant after Rs 69.90 crore of the Rs 132.54 crore capital-expenditure allocation had not been reported as utilised at September 30, 2026.