










GNFC Q2 operating revenue was ₹2,773 crore, PBT fell 42%
Key highlights
- GNFC’s Q2 FY 2026-27 operating revenue rose to Rs 2,773 crore from Rs 2,238 crore in Q1.
- GNFC’s Q2 profit before tax declined to Rs 241 crore from Rs 416 crore in Q1 FY 2026-27.
- GNFC’s chemicals segment result fell to Rs 177 crore in Q2 from Rs 425 crore in Q1.
- GNFC’s total assets were Rs 11,937 crore on 30 September 2026, compared with Rs 11,225 crore on 31 March 2026.
powered by IRIS
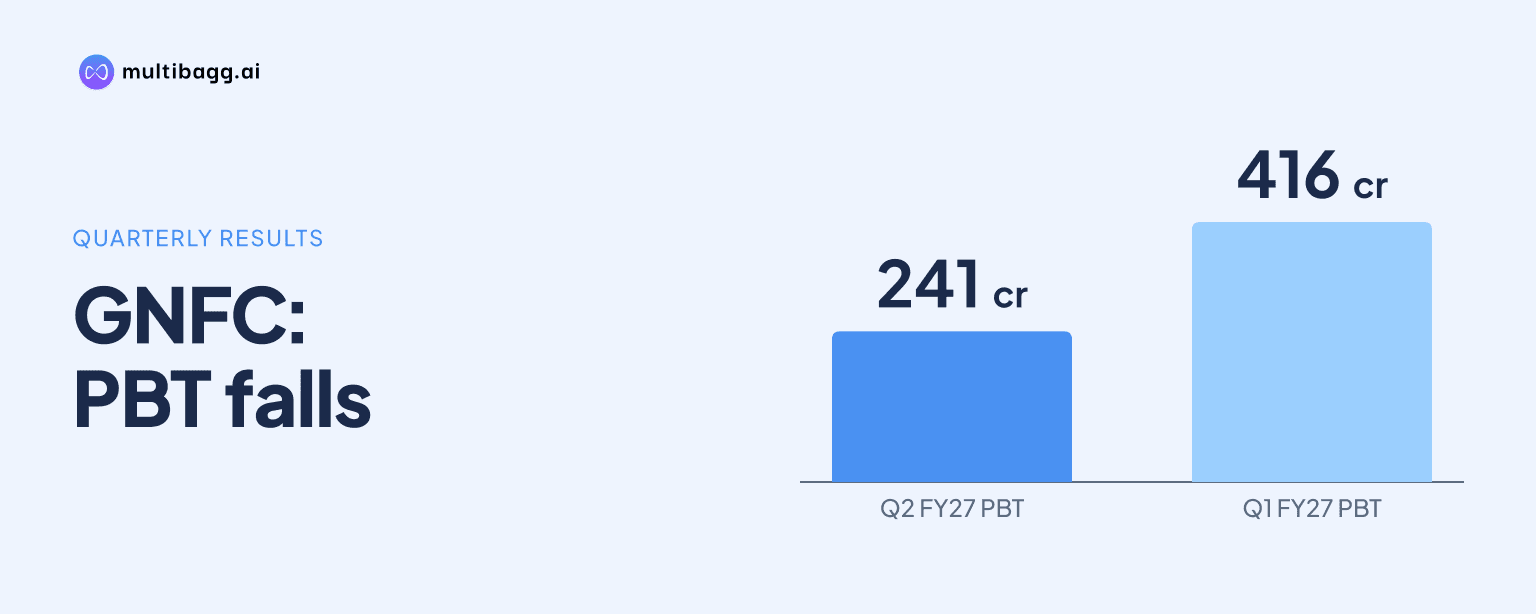
Gujarat Narmada Valley Fertilizers & Chemicals Limited reported operating revenue of Rs 2,773 crore in the second quarter (Q2) of fiscal year (FY) 2026-27, but profit before tax (PBT) fell 42% sequentially to Rs 241 crore from Rs 416 crore as lower realisations and higher fixed costs outweighed higher volumes.
Know Gujarat Narmada Valley Fertilizers & Chemicals inside out
Results, valuation, peers and who's buying, in one view.
Why did GNFC’s Q2 profit fall despite higher revenue?
GNFC’s PBT declined to Rs 241 crore in Q2 FY 2026-27 from Rs 416 crore in Q1, even as operating revenue increased by Rs 535 crore to Rs 2,773 crore from Rs 2,238 crore. Management said the sequential revenue increase mainly came from higher volumes across most products, partly offset by lower realisations, while lower realisations and higher fixed costs reduced the result.
Profit after tax (PAT) also decreased, to Rs 185 crore in Q2 from Rs 310 crore in Q1, although total revenue rose to Rs 2,901 crore from Rs 2,339 crore. GNFC said Q2 included liquidation of substantial inventory built up at the beginning of the quarter, consistent with management’s explanation that higher volumes supported sales.
How did GNFC’s fertilizer and chemicals segments perform in Q2?
GNFC’s chemicals segment remained the largest contributor to segment result, but its result declined to Rs 177 crore in Q2 FY 2026-27 from Rs 425 crore in Q1. Management attributed the sequential reduction mainly to lower realisations and higher fixed costs, partly offset by higher volume; chemicals revenue nevertheless rose to Rs 1,631 crore from Rs 1,569 crore.
GNFC’s fertilizer revenue increased to Rs 1,117 crore in Q2 from Rs 649 crore in Q1, while its segment loss narrowed to Rs 38 crore from Rs 85 crore. Management linked the smaller loss to the revised urea energy norms and lower input costs, partly offset by higher fixed costs. Other-segment revenue was Rs 25 crore against Rs 20 crore in Q1, and its segment result rose to Rs 12 crore from Rs 9 crore.
How did GNFC’s Q2 results compare with last year?
GNFC’s operating revenue increased to Rs 2,773 crore in Q2 FY 2026-27 from Rs 1,968 crore in Q2 FY 2025-26, while PBT rose to Rs 241 crore from Rs 230 crore. Management said the year-on-year revenue increase reflected higher realisations and volumes across most products, while higher input and fixed costs partly offset the resulting improvement in profit.
Chemicals revenue rose to Rs 1,631 crore from Rs 1,162 crore and the segment result increased to Rs 177 crore from Rs 158 crore. Fertilizer revenue climbed to Rs 1,117 crore from Rs 781 crore, but the segment loss widened slightly to Rs 38 crore from Rs 35 crore, with management citing higher input and fixed costs as partial offsets to improved realisations.
For H1 FY 2026-27, GNFC reported operating revenue of Rs 5,011 crore and PBT of Rs 657 crore, compared with Rs 3,569 crore and Rs 335 crore in H1 FY 2025-26. Management said the half-year comparison was not comparable because the Bharuch complex underwent an annual turnaround during H1 FY 2025-26; chemicals segment result was Rs 602 crore versus Rs 294 crore, while fertilizer segment loss narrowed to Rs 123 crore from Rs 135 crore.
Got a follow-up? Ask IRIS
What changed in GNFC’s balance sheet and cash flow?
GNFC’s total assets were Rs 11,937 crore on 30 September 2026, compared with Rs 11,225 crore on 31 March 2026. Net fixed assets increased to Rs 3,314 crore from Rs 2,881 crore, while capital work in progress (CWIP) decreased to Rs 781 crore from Rs 900 crore; CWIP mainly represented the Weak Nitric Acid III plant, Ammonium Nitrate II plant and urea-reactor replacement.
Bank deposits rose to Rs 1,805 crore at 30 September from Rs 1,111 crore at 31 March, while investments declined to Rs 1,260 crore from Rs 1,558 crore. GNFC reported borrowings of Rs 109 crore at the September date, versus no borrowings shown at 31 March, while net worth increased to Rs 9,183 crore from Rs 8,981 crore.
Operating activities generated Rs 141 crore of cash in H1 FY 2026-27, down from Rs 314 crore in H1 FY 2025-26. Financing cash outflow was Rs 310 crore against Rs 264 crore a year earlier, mainly representing dividend payment, and the closing cash-flow position was an outflow of Rs 98 crore compared with an outflow of Rs 2 crore.
What projects and external factors does GNFC identify next?
GNFC said its captive coal-based power plant at Dahej has started operations, reducing operating cost, while the remaining activities are nearing closure. At Bharuch, projects under execution include a 50 thousand tonnes per annum (KTPA) ammonia expansion, a 200 KTPA Weak Nitric Acid III plant, a 163 KTPA Ammonium Nitrate II plant and a circulating fluidised bed combustion (CFBC) steam boiler with capacity of 180 to 200 metric tonnes per hour.
Management said the Bharuch projects are broadly on schedule. It expects the ammonia expansion to improve reliability of the existing ammonia loop and provide some energy-cost savings, while the Weak Nitric Acid and Ammonium Nitrate projects are expected to strengthen market share and increase revenue, contribution and PBT. Management said the CFBC boiler is intended to improve operating reliability and reduce energy costs.
GNFC is also considering a 150 KTPA BisPhenol-A project and a 100 KTPA polyols project at Dahej, alongside a 350 KTPA acetic-acid project at Bharuch. Management expects market studies and detailed project reports for these projects to be completed during FY 2026-27. The announcement of nutrient-based subsidy rates for complex fertilizer, effective from the Rabi season, remained awaited at the time of the release.
Conclusion
GNFC’s Q2 FY 2026-27 performance combined Rs 2,773 crore of operating revenue with sequential PBT of Rs 241 crore, down from Rs 416 crore in Q1. Higher sales volumes and inventory liquidation lifted revenue, but lower realisations and higher fixed costs, particularly in chemicals, reduced quarterly profitability.
The next disclosed milestones are progress on the Bharuch ammonia, Weak Nitric Acid III, Ammonium Nitrate II and CFBC boiler projects, which management said were broadly on schedule, and completion of studies and detailed project reports for three proposed projects during FY 2026-27. The pending Rabi-season complex-fertilizer subsidy rates also remain a disclosed variable for GNFC.