










Gopal Snacks lifts Q2 EBITDA margin to 9% as H1 EBITDA rises 86%
Key highlights
- Gopal Snacks' Q2 FY27 EBITDA margin rose to 9.0% from 6.4% in Q2 FY26.
- Q2 FY27 EBITDA excluding other income increased 72.3% year on year to Rs 41.6 crore.
- H1 FY27 revenue from operations increased 26.7% to Rs 883.9 crore.
- Focus-state Q2 FY27 revenue rose 34.7% year on year to Rs 131.7 crore.
powered by IRIS
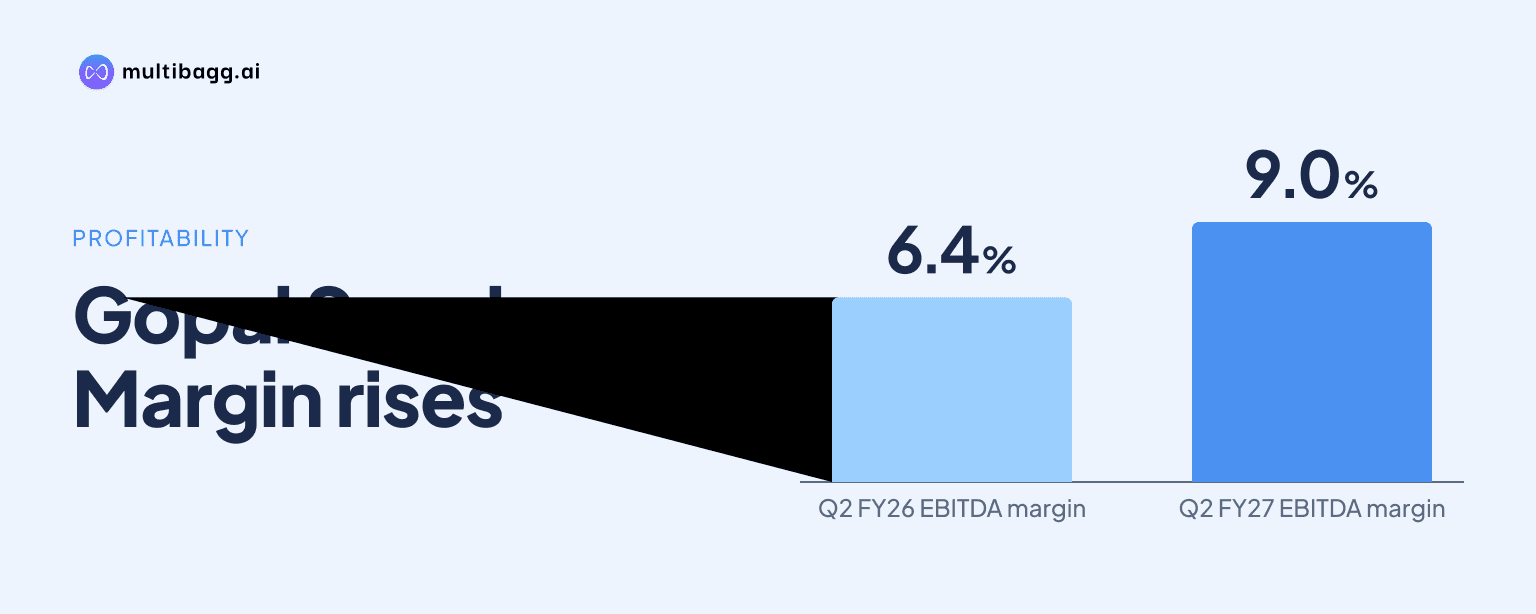
Gopal Snacks lifted its EBITDA, or earnings before interest, tax, depreciation and amortisation, margin to 9.0% in Q2 FY27 from 6.4% in Q2 FY26, as EBITDA excluding other income rose 72.3% to Rs 41.6 crore; H1 FY27 EBITDA increased 85.7% to Rs 73.1 crore.
Know Gopal Snacks inside out
Results, valuation, peers and who's buying, in one view.
How did Gopal Snacks' Q2 FY27 operating margin change?
Gopal Snacks' Q2 FY27 EBITDA margin increased by 2.6 percentage points year on year and 1.6 percentage points sequentially, reaching 9.0% from 6.4% in Q2 FY26 and 7.4% in Q1 FY27. EBITDA excluding other income was Rs 41.6 crore in Q2 FY27, compared with Rs 24.1 crore a year earlier and Rs 31.5 crore in the preceding quarter.
Revenue from operations rose to Rs 461.5 crore in Q2 FY27, up 22.9% from Rs 375.7 crore in Q2 FY26 and 9.3% from Rs 422.3 crore in Q1 FY27. EBITDA growth of 72.3% year on year exceeded revenue growth of 22.9%, while the Rs 10.1 crore sequential rise in EBITDA accompanied a Rs 39.2 crore rise in revenue.
Gross profit increased to Rs 125.0 crore in Q2 FY27 from Rs 99.2 crore in Q2 FY26, and gross margin rose by 0.7 percentage points to 27.1%. The increase in EBITDA margin from 6.4% to 9.0% was larger than the gross-margin movement over the same comparison.
Profit before tax, or PBT, before exceptional items rose 92.9% year on year to Rs 25.9 crore in Q2 FY27 from Rs 13.4 crore, and its margin increased to 5.6% from 3.6%. Profit after tax, or PAT, after exceptional items was Rs 45.9 crore, up 78.5% from Rs 25.7 crore, while PAT margin was 9.9% against 6.8% a year earlier.
What does the first-half FY27 comparison show?
Gopal Snacks' H1 FY27 results show EBITDA rising faster than revenue, with EBITDA increasing 85.7% to Rs 73.1 crore while revenue from operations grew 26.7% to Rs 883.9 crore. EBITDA margin reached 8.3% in H1 FY27, compared with 5.6% in H1 FY26, an increase of 2.7 percentage points.
Gross profit rose 30.5% to Rs 238.6 crore in H1 FY27 from Rs 182.9 crore in H1 FY26, and gross margin increased to 27.0% from 26.2%. This 0.8-percentage-point gross-margin movement was smaller than the 2.7-percentage-point EBITDA-margin change, alongside EBITDA excluding other income increasing from Rs 39.4 crore to Rs 73.1 crore.
PBT before exceptional items rose 138.1% to Rs 44.5 crore in H1 FY27 from Rs 18.7 crore in H1 FY26. Its margin was 5.0%, compared with 2.7% a year earlier, while PAT after exceptional items increased 108.0% to Rs 58.7 crore and its margin rose to 6.6% from 4.0%.
The first-half result includes Q1 FY27 EBITDA of Rs 31.5 crore at a 7.4% margin and Q2 FY27 EBITDA of Rs 41.6 crore at a 9.0% margin. That quarter-on-quarter progression meant the second quarter accounted for Rs 41.6 crore of the Rs 73.1 crore H1 EBITDA reported by Gopal Snacks.
Got a follow-up? Ask IRIS
What operating measures does management link to the result?
Gopal Snacks says its continued focus on operational efficiency, improved pricing power, disciplined execution and manufacturing capabilities helped maintain performance despite a challenging raw-material-cost environment. The company also says manufacturing integration, production consolidation and greater backward integration are intended to lower operating, logistics and power costs, simplify material movement and deliver recurring transportation savings.
The presentation identifies demand growth in several categories during Q2 FY27: Wafers revenue rose 40.0% year on year to Rs 58.0 crore, Gathiya increased 25.6% to Rs 123.1 crore, and Pellets and Extruded Snacks grew 23.0% to Rs 80.9 crore. Wafers volume increased 39.7% to 2,681 metric tonnes, while Gathiya volume rose 11.1% to 7,159 metric tonnes.
Category growth was not uniform across the quarter. Namkeen revenue increased 14.5% year on year to Rs 105.0 crore, whereas Papad, Spice and Besan rose 7.9% to Rs 41.1 crore; Other Snacks Products increased 71.4% to Rs 24.9 crore. Other Snacks Products mainly include noodles, rusk, wafer biscuit, wafer roll and washing bar, according to the presentation.
Gathiya remained the largest reported Q2 FY27 product category by revenue at Rs 123.1 crore, ahead of Namkeen at Rs 105.0 crore and Pellets and Extruded Snacks at Rs 80.9 crore. Wafers generated Rs 58.0 crore, but its 40.0% year-on-year revenue increase exceeded the growth rates reported for those three larger categories.
Where did Gopal Snacks' Q2 FY27 revenue growth come from?
Gopal Snacks generated Rs 276.5 crore of Q2 FY27 revenue in core states, Rs 131.7 crore in focus states and Rs 23.6 crore in other states. Core-state revenue grew 15.5% year on year from Rs 239.4 crore, while focus-state revenue grew 34.7% from Rs 97.8 crore and other-state revenue grew 94.0% from Rs 12.2 crore.
Focus-state revenue also rose 15% sequentially from Rs 114.2 crore in Q1 FY27, exceeding the 3% sequential rise in core-state revenue from Rs 269.5 crore. In the Q2 FY27 revenue mix, core states represented 60.0%, focus states 28.5%, other states 5.1%, exports 0.2%, and others 6.2%.
The dealer network in focus states expanded to 616 in Q2 FY27 from 448 in Q2 FY26 and 567 in Q1 FY27. The core-state dealer network remained at 311 across all three reported quarters, while other-state dealers reached 130 from 99 a year earlier; Gopal Snacks also reported 1,057 distributors overall.
The 168-dealer year-on-year increase in focus states coincided with Rs 33.9 crore of revenue growth in those markets, from Rs 97.8 crore to Rs 131.7 crore. By comparison, the core-state dealer count was unchanged at 311 while core-state revenue increased by Rs 37.1 crore to Rs 276.5 crore.
Conclusion
Gopal Snacks reported both higher sales and wider operating margins in Q2 FY27 and H1 FY27. Q2 revenue increased 22.9% year on year to Rs 461.5 crore, while EBITDA excluding other income increased 72.3% to Rs 41.6 crore and lifted the margin to 9.0%; in H1 FY27, revenue rose 26.7% and EBITDA increased 85.7%.
The disclosed item to watch is whether Gopal Snacks' manufacturing-integration plan, including production consolidation and greater backward integration, delivers the intended reductions in operating, logistics and power costs. The company has also disclosed Rajkot main-plant operations with installed capacity of 1,05,233 metric tonnes per annum and a Nagpur besan unit with capacity of 19,642 metric tonnes per annum, alongside focus-state dealers rising from 448 to 616.