










Gufic Biosciences Q2 FY27 Revenue Rises 25% to ₹288.4 Crore
Key highlights
- Gufic Biosciences reported Q2 FY27 revenue from operations of ₹288.4 crore, up 25.2% from ₹230.4 crore.
- Q2 FY27 EBITDA increased to ₹49.7 crore from ₹37.9 crore, while EBITDA margin rose to 17.23%.
- Profit after tax rose to ₹23.5 crore from ₹14.9 crore, taking PAT margin to 10.95%.
- The Indore facility reached EBITDA break-even, and the US FDA pre-approval inspection resulted in three observations.
powered by IRIS
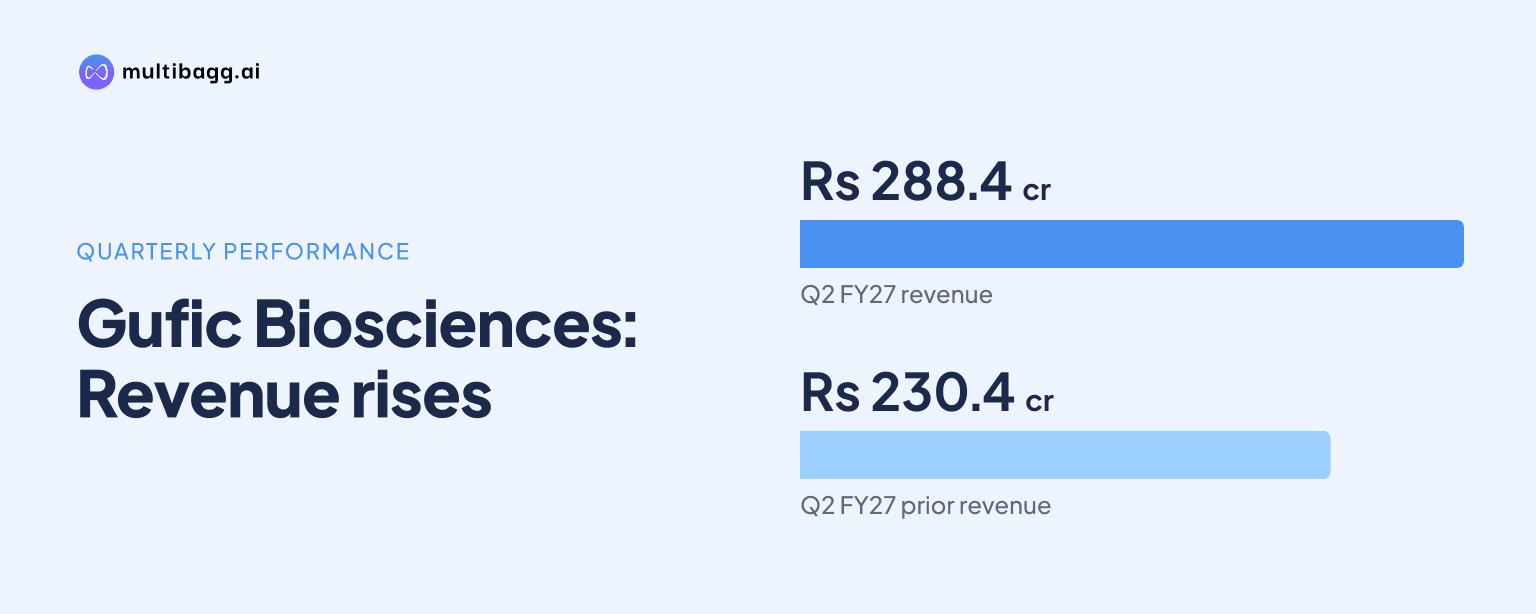
Gufic Biosciences Limited reported Q2 FY27 revenue from operations of ₹288.4 crore, up 25% from ₹230.4 crore a year earlier, while profit after tax rose to ₹23.5 crore from ₹14.9 crore. The quarterly performance also lifted EBITDA margin to 17.23% from 16.45%.
Know Gufic BioSciences inside out
Results, valuation, peers and who's buying, in one view.
What did Gufic Biosciences report for Q2 FY27?
Gufic Biosciences reported consolidated revenue of ₹288.27 crore and net profit of ₹23.47 crore for the July-September 2026 quarter, with results announced on November 14, 2026. During its subsequent earnings call, the company stated revenue from operations at ₹288.4 crore and profit after tax at ₹23.5 crore, using rounded figures.
The company’s revenue from operations increased from ₹230.4 crore in Q2 FY26. EBITDA rose to ₹49.7 crore from ₹37.9 crore in the comparable quarter. Profit before tax increased to ₹31.5 crore from ₹20.5 crore, while profit after tax rose from ₹14.9 crore.
The reported improvement in profitability was accompanied by a rise in margins. EBITDA margin was 17.23% in Q2 FY27, compared with 16.45% in Q2 FY26. PAT margin increased to 10.95% from 8.89% over the same period.
What drove Gufic Biosciences' quarterly revenue growth?
Gufic Biosciences said the revenue increase was driven mainly by its India business and rest-of-world markets. Management indicated that higher-margin contributions from the United States and European Union markets were yet to begin materially, as regulatory approvals for the Indore facility remain pending.
The company’s India-led growth is significant because its near-term operating performance is still largely linked to domestic demand and existing overseas markets. On the call, management said it had received a couple of approvals in Central Europe, but broader entry into regulated international markets will depend on further approvals.
The call also pointed to progress in the company’s international commercial model. Management said registrations and initial orders had come together in markets where Gufic Biosciences holds marketing authorisations. This model differs from a purely distributor-led approach, although the company did not provide revenue figures for these markets during the call.
How did the Indore facility perform during the quarter?
Gufic Biosciences said its Indore manufacturing facility reached EBITDA break-even and made a positive contribution during Q2 FY27. Management stated that output increased across all four lines at the plant during the quarter.
The facility is important to the company’s manufacturing expansion and regulated-market strategy. Management had earlier outlined plans to raise Indore capacity utilisation from about 30% towards 40% to 45% by the end of FY27. The November call did not provide a fresh utilisation figure, but confirmed improved production across the site’s four lines.
The company also said a US Food and Drug Administration pre-approval inspection at Indore had been completed. It is addressing three observations from that inspection. Separately, a compliance report was submitted for European Union good manufacturing practice certification, which was still awaited in November.
These regulatory milestones matter because the company has identified the United States and Europe as potential higher-margin markets. However, Gufic Biosciences did not specify a date for commercial supplies from Indore to either market.
Got a follow-up? Ask IRIS
What should investors assess after the Q2 FY27 results?
Investors can assess the quarter through revenue growth, margin expansion and the execution of the Indore ramp-up. Revenue from operations grew 25.2% year-on-year, while EBITDA grew faster at 31.1%, resulting in a 78-basis-point expansion in EBITDA margin.
Net profit increased 57.7% year-on-year to ₹23.5 crore, outpacing revenue growth. The improvement in PAT margin to 10.95% from 8.89% shows that the quarter delivered stronger profitability alongside sales growth. The reported numbers, however, do not establish the pace of future earnings growth.
Management had earlier maintained a 15% to 20% year-on-year revenue growth floor, while the November discussion referred to domestic efforts in the 12% to 15% range and did not repeat a consolidated growth floor. This distinction is relevant when comparing prior management commentary with the latest quarterly discussion.
The company also referred to a proposed launch of Canadian-partner fillers in India. Management targeted December and expressed hope for a January launch, after earlier indicating a Q3 or Q4 FY27 window for Revanesse Prollenium fillers. The schedule remains a management target rather than a reported commercial outcome.
Why do regulatory approvals remain important for Gufic Biosciences?
Gufic Biosciences’ Q2 performance was primarily supported by India and rest-of-world markets, while access to regulated markets remains a pending part of its expansion plan. The completion of the US FDA pre-approval inspection and the submission of an EU GMP compliance report are operational developments, but neither confirms commercial approval or sales from those markets.
For the pharmaceutical industry, regulatory clearances determine whether a facility can supply products into specific jurisdictions. In Gufic Biosciences’ case, progress at Indore could affect the facility’s product mix and market reach once the required approvals are obtained. Until then, the financial contribution from the site will remain more closely tied to currently accessible markets.
The quarterly data also shows why the Indore plant’s operating position is being watched. Its move to EBITDA break-even and higher production across four lines indicate an improved operating contribution. Yet the company has not disclosed Indore-specific revenue, capacity utilisation for the quarter, or the expected timing of revenue from the US and EU.
Conclusion
Gufic Biosciences delivered higher Q2 FY27 revenue, EBITDA and profit, with revenue from operations reaching ₹288.4 crore and PAT reaching ₹23.5 crore. Margin expansion, a positive contribution from the Indore plant and growth led by India and rest-of-world markets were the central features of the quarter.
The next factors to watch are the company’s response to three US FDA inspection observations, the pending EU GMP certification, progress towards Indore’s planned 40% to 45% utilisation by FY27-end, and the targeted India launch of Canadian-partner fillers around December or January.