










Gulf Oil Q2 FY27 Profit Rises 35% to ₹118 Crore
Key highlights
- Gulf Oil Lubricants reported Q2 FY27 standalone net profit of ₹118 crore, up more than 35% year-on-year from ₹87.1 crore.
- Q2 FY27 profit was ₹2 crore below the ₹120 crore analyst consensus estimate.
- Q1 FY27 revenue rose 30.57% year-on-year to ₹1,327.21 crore, while net profit increased 28.45% to ₹123.16 crore.
- Gulf Oil’s Q2 and H1 FY27 earnings call is scheduled for October 30, 2026, at 3:30 p.m. IST.
powered by IRIS
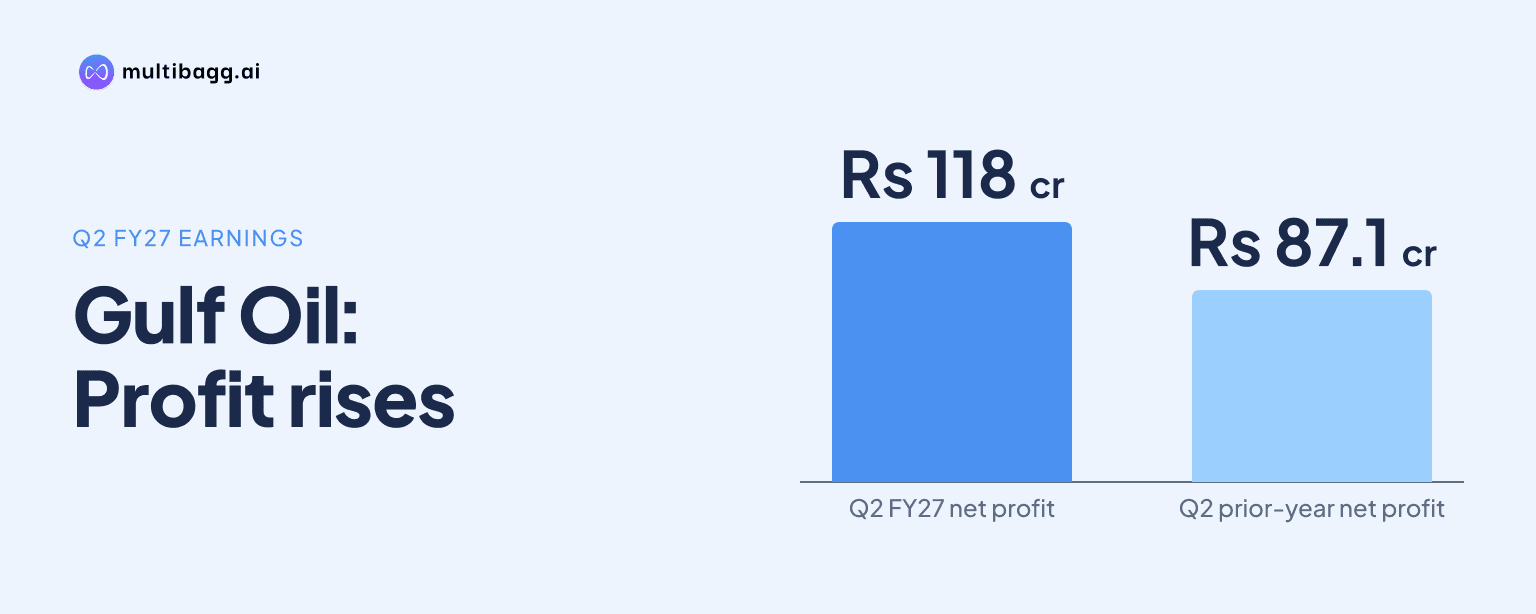
Q2 profit records strong year-on-year growth
Know Gulf Oil Lubricants India inside out
Results, valuation, peers and who's buying, in one view.
Gulf Oil Lubricants India Limited reported standalone net profit of ₹118 crore for the second quarter of FY27. The figure was higher than ₹87.1 crore reported in the corresponding quarter of the previous year. This represents year-on-year growth of more than 35%. The result indicates continued earnings growth for the lubricants company after a strong first quarter. However, the reported profit was marginally below the analyst consensus estimate of ₹120 crore. The difference between the reported number and consensus was ₹2 crore. The company’s board was scheduled to consider and approve unaudited standalone and consolidated results for the quarter and half year ended September 30, 2026, on October 28.
Result falls slightly short of analyst estimate
The Q2 standalone profit was close to, but below, the ₹120 crore consensus estimate cited in the available data. A small miss against expectations does not change the fact that profit rose materially from the prior-year level. Investors typically compare quarterly results with both the previous-year period and market estimates. In this case, the year-on-year comparison shows a significant improvement, while the consensus comparison points to a modest shortfall. The supplied information does not provide a detailed Q2 revenue, expense, EBITDA, or margin breakup. Therefore, the factors behind the difference from the consensus estimate cannot be determined from the available disclosures. The scheduled earnings call may provide further management commentary on quarterly performance.
Q1 FY27 set a strong base
The company had reported a strong June 2026 quarter, which was the first quarter of FY27. Revenue for Q1 FY27 rose 30.57% year-on-year to ₹1,327.21 crore. The company described this as its highest quarterly revenue on record. Net profit for that quarter increased 28.45% year-on-year to ₹123.16 crore. The June-quarter result also included 17% volume growth year-on-year, according to the provided information. Growth was reported across B2C, OEM and B2B segments. This first-quarter performance provides useful context for the Q2 profit update.
Margin performance remains a key point
Despite the strong Q1 revenue and profit growth, operating margin was reported at 12.49% in Q1 FY27. The available information said the margin had declined slightly amid rising costs. For a lubricants manufacturer, revenue expansion and volume growth do not automatically translate into proportionate margin gains. Input costs, product mix, pricing and operating expenses can influence profitability. No Q2 operating-margin figure has been provided in the source material. As a result, it is not possible to confirm whether the Q2 profit increase was accompanied by margin expansion or compression. The October 30 analyst call is the next identified forum for additional details.
Key reported financial figures
Got a follow-up? Ask IRIS
Revenue trend shows steady expansion
The company’s quarterly revenue trend has strengthened over the past several quarters. Revenue was ₹894 crore in June 2024 and increased to ₹1,016 crore in June 2025. By June 2026, revenue had reached ₹1,327 crore in the quarterly revenue series provided. The June 2026 year-on-year growth rate of 30.6% was higher than the growth rates listed for the earlier comparable quarters. Annual revenue growth was also reported at 16.3% for the financial year ended March 2026. These figures show that the company entered FY27 with a higher revenue base than in the previous year.
Growth target across lubricant segments
Gulf Oil has stated an aim to deliver volume growth at two to three times the industry growth rate. The industry growth rate referenced in the supplied material is about 3% to 4%. For FY27, the company plans to sustain double-digit volume growth in line with this target. The stated approach covers growth in consumer-facing, original equipment manufacturer and business-to-business channels. Actual performance against this goal will depend on reported sales volumes and segment updates in subsequent disclosures. The Q1 volume growth of 17% year-on-year was above the cited industry growth range. No Q2 volume figure has been provided.
EV charging subsidiary remains part of expansion plans
Alongside its lubricant business, Gulf Oil has expanded its interest in EV charger subsidiary Tirex. In an earlier update, the company said it increased its stake in Tirex by 14% to 65%. Tirex recorded 75% revenue growth in the first half of FY26, according to the supplied information. This investment places Gulf Oil in an adjacent mobility-related business, separate from its core lubricants operations. The current Q2 FY27 data does not provide a fresh financial update on Tirex. It also does not quantify any contribution from the subsidiary to the latest reported Q2 standalone profit.
Investor call scheduled for October 30
Gulf Oil Lubricants India has scheduled its Q2 and H1 FY27 earnings conference call with analysts and institutional investors for October 30, 2026, at 3:30 p.m. IST. The company disclosed the call schedule under Regulation 30 of the Listing Obligations and Disclosure Requirements regulations on October 26. Management commentary during the call may address the first-half performance, cost conditions, demand trends and business priorities. Investors will also look for clarity on margins after the Q1 decline to 12.49%. The company’s reported Q2 profit growth establishes a positive year-on-year comparison, even as the number came just below consensus. Further assessment will depend on the full financial results and management disclosures during the scheduled call.
What the Q2 result means
The Q2 FY27 result shows Gulf Oil Lubricants maintaining profit growth from a higher prior-year base. Standalone net profit increased from ₹87.1 crore to ₹118 crore, while the miss against consensus was limited to ₹2 crore. The company’s Q1 FY27 performance had already shown revenue growth of 30.57% and profit growth of 28.45%, although margins were under some pressure. The next major update is the October 30 earnings call, when the company is expected to discuss Q2 and H1 FY27 performance with analysts and institutional investors.