










Harsha Engineers sees China growth stay single digit until FY28 H2
Key highlights
- Harsha Engineers expects China volume growth to remain single digit through early FY28.
- China capacity is expected to begin contributing in FY28 H2 after approvals and commercialisation.
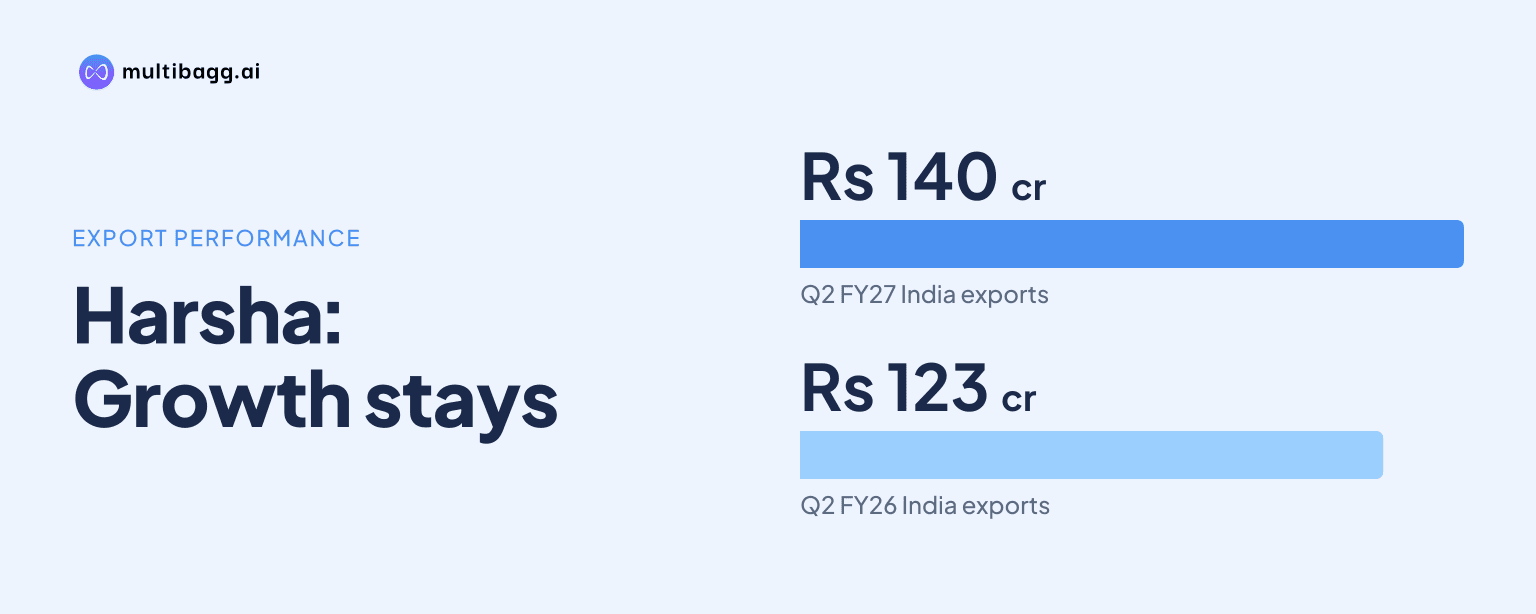
- India-based exports rose almost 15% to Rs 140 crore in Q2 FY27 from Rs 123 crore in Q2 FY26.
- Foreign subsidiaries reported a combined loss of Rs 1.7 crore in Q2 FY27.
powered by IRIS
Harsha Engineers International Limited expects China volume growth to remain single digit through FY27 and the early part of FY28, with the larger increase expected only after new capacity contributes in FY28 H2. Management said customer approvals will delay commercialisation until around the end of FY28 H1, even after capital expenditure is completed.
Know Harsha Engineers International inside out
Results, valuation, peers and who's buying, in one view.
Why will Harsha Engineers’ China growth remain single digit until FY28 H2?
Harsha Engineers expects China volume growth to remain in the single-digit range during FY27 and the early part of FY28 because a larger increase depends on new capacity coming online. Vishal Rangwala said China growth had softened versus the previous quarter and the prior year, although management still expects the business to grow rather than contract.
Management did not provide a specific China revenue-growth target in rupee terms. In response to a question that referred to China revenue of about Rs 120 crore in FY26, Maulik Jasani said reported rupee growth can also be affected by exchange-rate movements, while the company’s stated China outlook refers to single-digit volume growth.
The timing separates ongoing demand from the capacity-led step-up. Rangwala said China should continue to grow before the expansion is ready, but the “bigger jump” in growth would come when the new capacity is online. Management therefore linked the improvement to the brownfield expansion rather than to an immediate recovery in sales or pricing.
When will Harsha Engineers’ China expansion begin contributing?
Harsha Engineers expects China capacity to begin contributing in FY28 H2, after commercialisation around the end of FY28 H1. Management made that distinction when asked whether capital-expenditure completion by June 2027 would allow the project to benefit FY28 from the beginning; it said customer-approval timelines would extend the commercialisation process.
Customer approval is the disclosed mechanism behind the delay. Maulik Jasani said the project could not be treated as commercial immediately upon capex completion because customer approvals would be required, and management would provide better guidance closer to year-end and completion. The stated operational sequence is capex completion, approvals, commercialisation around FY28 H1-end and contribution in FY28 H2.
Harsha Engineers did not disclose a standalone remaining-capex figure for China on this call. In response to an analyst asking how an earlier Rs 150 crore estimate was split between China and Advantek, Jasani said he did not have the breakup available and referred to Rs 220 crore for the two projects together.
Management did discuss the intended capital productivity of the projects. Excluding immovable expenditure, it said asset turns could be better than 2 times; Sanjay Majmudar explained that common infrastructure serves several years, while incremental productive capex includes project-related civil work and plant and machinery. That framework does not establish a quarterly China revenue ramp.
Got a follow-up? Ask IRIS
What do China’s sales and export figures show?
Harsha Engineers said a slow China quarter contributed to a 1% growth rate in the foreign business in Q2 FY27, as raised by an analyst. Management said India grew faster as a share of the group, while exports also increased in absolute terms, meaning the combined foreign picture should not be treated as a measure of India-based export demand alone.
India-based exports increased by almost 15% year on year in Q2 FY27, according to management. Sanjay Majmudar said exports rose from Rs 123 crore in Q2 FY26 to Rs 140 crore in Q2 FY27, and that first-half export growth from India was about 17% to 18%.
The contrast is that India-based exports rose from Rs 123 crore to Rs 140 crore, while the combined foreign-business growth was only 1% in Q2 FY27. Management attributed the broader picture to China’s slower quarter and the effect of Romania, rather than saying India’s export operations had declined.
China’s margin outlook remains limited in the transcript. The analyst said China margins were in single digits, compared with historical double-digit margins and roughly 8% to 10% top-line growth, but management did not provide a separate China margin target or commit to a recovery before the FY28 H2 capacity contribution.
How do China and Romania affect Harsha Engineers’ overseas outlook?
Harsha Engineers reported a combined foreign-subsidiary loss of Rs 1.7 crore in Q2 FY27. Management did not disclose China and Romania results separately for the quarter, saying subsidiary-level figures would be available after the year is completed, but said the combined foreign-subsidiary loss could end the year at a low single-digit crore amount.
Romania is a separate uncertainty in the overseas outlook. Management said it was considering downsizing Romania and expected to be clearer on the details by Q3; Majmudar said Romania’s contribution could decline considerably depending on how and when the downsizing is executed. That planned action limits the usefulness of treating China’s volume outlook as a direct consolidated-revenue forecast.
Management also identified metal-price inflation as a factor in reported revenue. It said quantitative growth was expected at 12% to 15%, while higher metal prices could result in a higher reported value-growth rate. China’s single-digit volume guidance can therefore differ from reported consolidated revenue growth because of exchange rates, metal prices and Romania’s changing scale.
For the Engineering business, management expects EBITDA, or earnings before interest, tax, depreciation and amortisation, margin of around 22% at the India level and around 17% to 18% at the consolidated Engineering level. Those expectations were subject to metal-price movements and other discussed factors, and management did not disclose a China-specific EBITDA margin forecast.
Conclusion
Harsha Engineers’ disclosure indicates that China is expected to remain a gradual-growth business through FY27 and the early part of FY28, rather than delivering an immediate capacity-driven increase. India-based exports rose almost 15% to Rs 140 crore in Q2 FY27, but China’s slower quarter and Romania’s position constrained the combined foreign-business outcome.
The next disclosed milestones are management’s expected Q3 clarity on Romania downsizing, progress in completing the China expansion and customer approvals needed for commercialisation around the end of FY28 H1. Management expects China capacity to contribute in FY28 H2 and has said it will provide better guidance nearer completion, leaving the pace of the ramp unresolved.