










Harsha Engineers Q2 stampings sales rise 109%, bushings 42.5%
Key highlights
- Harsha Engineers reported Q2 FY 2027 stampings sales of Rs 23 crore, up 109% year on year.
- Harsha Engineers reported Q2 FY 2027 bushing sales of Rs 42 crore, up 42.5% year on year.
- Harsha Engineers' India engineering revenue rose 24.1% year on year to Rs 329.97 crore in Q2 FY 2027.
- Harsha Engineers incurred consolidated capital expenditure of Rs 72 crore in H1 FY 2027.
powered by IRIS
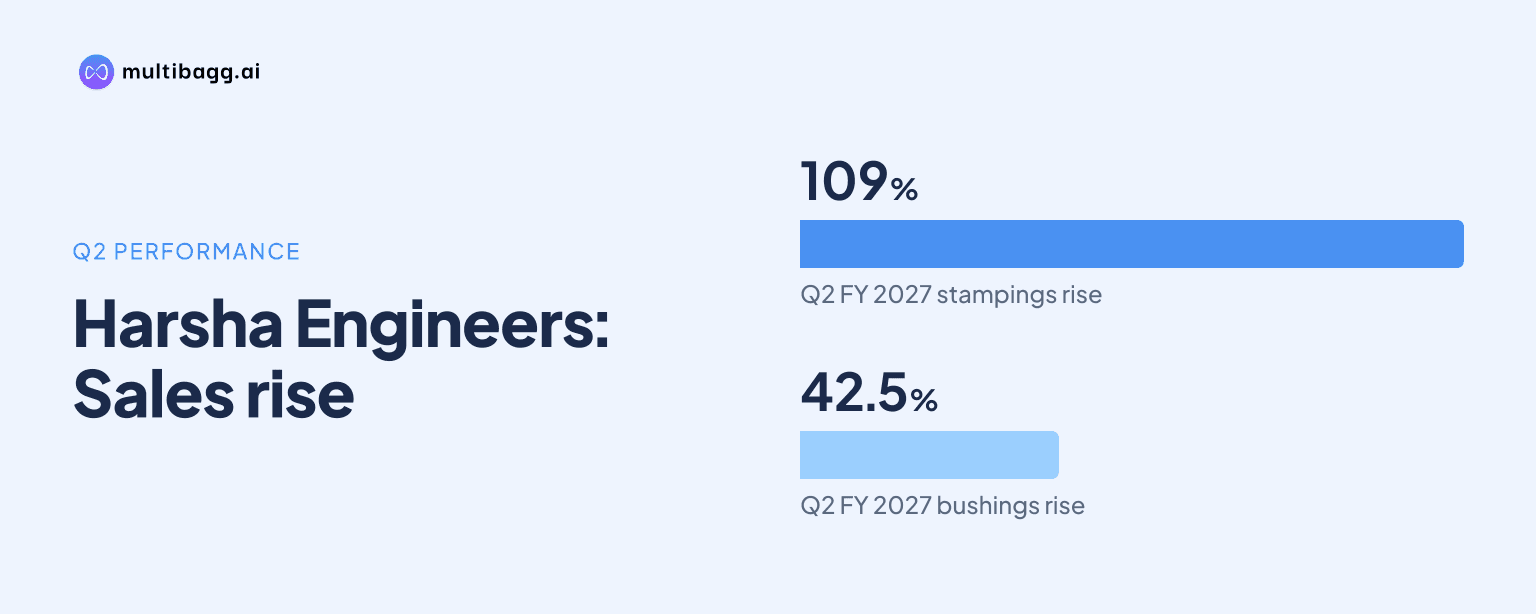
Harsha Engineers reported Rs 23 crore of stampings sales in Q2 FY 2027, up 109% year on year, while bushing sales rose 42.5% to Rs 42 crore. Harsha Engineers attributed stampings growth to continued demand and contributions from new stamping varieties commercialised during the financial year.
Know Harsha Engineers International inside out
Results, valuation, peers and who's buying, in one view.
What drove Harsha Engineers' stampings and bushing sales growth?
Harsha Engineers said continued demand and new varieties commercialised during FY 2027 supported the 109% year-on-year rise in Q2 stampings sales. Stampings sales reached Rs 23 crore in the second quarter (Q2) and Rs 42 crore in the first half (H1) of FY 2027, with H1 sales up 65% year on year.
Harsha Engineers reported bushing sales of Rs 42 crore in Q2 FY 2027, making bushings the larger of the two disclosed product lines by Rs 19 crore. Bushing sales were Rs 76 crore in H1 FY 2027, with growth of 42.5% in Q2 and 39% in H1 on a year-on-year basis.
Management said Harsha Engineers was on track to achieve approximately 30% bushing sales growth for the full year. The presentation did not disclose product-level volumes, margins, customer concentration or order-book values for bushings and stampings, so it does not quantify their individual profitability contribution.
The comparison shows that stampings expanded faster than bushings in percentage terms, while bushings delivered the higher reported sales value in both Q2 and H1 FY 2027. Harsha Engineers linked stampings growth specifically to newly commercialised varieties, whereas its bushing disclosure stated the sales figures and the full-year growth objective.
How did Harsha Engineers' India engineering business perform in Q2 FY 2027?
Harsha Engineers' India engineering business recorded revenue growth of 24.1% year on year in Q2 FY 2027, which management attributed to continued demand across key Indian segments. India engineering revenue was Rs 329.97 crore, compared with Rs 265.94 crore in Q2 FY 2026 and Rs 309.96 crore in Q1 FY 2027.
India engineering earnings before interest, tax, depreciation and amortisation, or EBITDA, increased to Rs 78.32 crore in Q2 FY 2027 from Rs 58.81 crore a year earlier. Its EBITDA margin was 23.7%, compared with 22.1% in Q2 FY 2026 and 22.4% in Q1 FY 2027.
Harsha Engineers said higher revenue, raw-material pass-through and reduced losses at wholly owned subsidiary Harsha Advantek contributed to the year-on-year and sequential margin improvement. India engineering profit after tax, or PAT, was Rs 45.79 crore in Q2 FY 2027, compared with Rs 34.99 crore in Q2 FY 2026 and Rs 39.32 crore in Q1 FY 2027.
Engineering and other consolidated revenue rose to Rs 428.17 crore in Q2 FY 2027 from Rs 363.12 crore a year earlier and Rs 421.08 crore in Q1 FY 2027. Its EBITDA reached Rs 81.12 crore, compared with Rs 62.96 crore in Q2 FY 2026 and Rs 69.79 crore in Q1 FY 2027, showing that engineering increased even as overall consolidated revenue declined sequentially.
Got a follow-up? Ask IRIS
What changed in Harsha Engineers' consolidated results?
Harsha Engineers' revenue from operations increased 16.3% year on year to Rs 440.09 crore in Q2 FY 2027 but declined from Rs 457.43 crore in Q1 FY 2027. Management said the approximately 3.8% sequential decline was largely due to lower sales in the solar business and international subsidiaries.
Consolidated EBITDA was Rs 81.85 crore in Q2 FY 2027, compared with Rs 63.96 crore in Q2 FY 2026 and Rs 72.61 crore in Q1 FY 2027. The EBITDA margin increased to 18.6% from 16.9% a year earlier and 15.9% in the preceding quarter.
Consolidated PAT rose to Rs 45.03 crore in Q2 FY 2027 from Rs 36.44 crore in Q2 FY 2026 and Rs 37.38 crore in Q1 FY 2027. The PAT margin was 10.2%, compared with 9.6% in Q2 FY 2026 and 8.2% in Q1 FY 2027.
The segment disclosure reported engineering and other consolidated PAT of Rs 44.48 crore in Q2 FY 2027, while solar engineering, procurement and construction and operations and maintenance PAT was Rs 55 lakh. Engineering therefore supplied most of the disclosed segment PAT during the quarter.
What could affect Harsha Engineers in the second half of FY 2027?
Harsha Engineers said large-size cage sales were Rs 14 crore in Q2 FY 2027 and Rs 24 crore in H1 FY 2027, with Q2 growth appearing flat. Management expects stronger growth in H2 FY 2027, citing good demand visibility, but did not provide a sales target or growth percentage for large-size cages.
Sales to Japan-based customers were Rs 24 crore in Q2 FY 2027 and Rs 44 crore in H1 FY 2027. Harsha Engineers reported growth of around 30% in Q2 and 28% in H1 for this customer group, but did not disclose the product mix of these sales.
Harsha Advantek reported a Rs 3 crore loss in Q2 FY 2027. Management expects Harsha Advantek to become PAT-positive in H2 FY 2027, based on expected sales growth, while its brownfield expansion project and the Harsha China brownfield expansion were described as on track.
Harsha Romania recorded negative EBITDA and PAT in Q2 and H1 FY 2027, while Harsha China partly offset its performance. The combined foreign-subsidiary net loss was around Rs 1.70 crore in Q2 and around Rs 5 crore in H1; management said it was implementing downsizing and related cost reduction at Harsha Romania and targeted a low-single-digit combined full-year loss.
Harsha Engineers incurred consolidated capital expenditure of Rs 72 crore in H1 FY 2027. That spending is linked to the on-track Harsha Advantek and Harsha China brownfield projects, while the presentation does not state their planned capacity additions or completion dates.
Conclusion
Harsha Engineers' Q2 FY 2027 update shows faster reported growth in stampings and bushings than in consolidated revenue. Stampings sales increased 109% to Rs 23 crore and bushing sales rose 42.5% to Rs 42 crore, while India engineering revenue grew 24.1% and consolidated EBITDA margin reached 18.6%.
The next disclosed milestones are management's approximately 30% full-year bushing growth objective, its expectation of stronger H2 FY 2027 large-size cage sales and its expectation that Harsha Advantek will become PAT-positive in H2. Harsha Engineers also targets a low-single-digit combined full-year loss for foreign subsidiaries as the Harsha Romania cost-reduction plan and Rs 72 crore of H1 capital expenditure progress.