










Harsha Guides 10%-12% Consolidated Growth as Romania Shrinks
Key highlights
- Harsha expects FY2027 India Engineering growth in the mid-to-high teens, versus 10%-12% consolidated growth.
- India Engineering grew more than 24% year on year in Q2 FY2027 and 23% in H1 FY2027.
- Harsha aims to arrest Romania operating losses by the end of FY2027 through downsizing and cost reduction.
- H1 India exports reached about Rs 280 crore, compared with Rs 480 crore for all of FY2026.
powered by IRIS
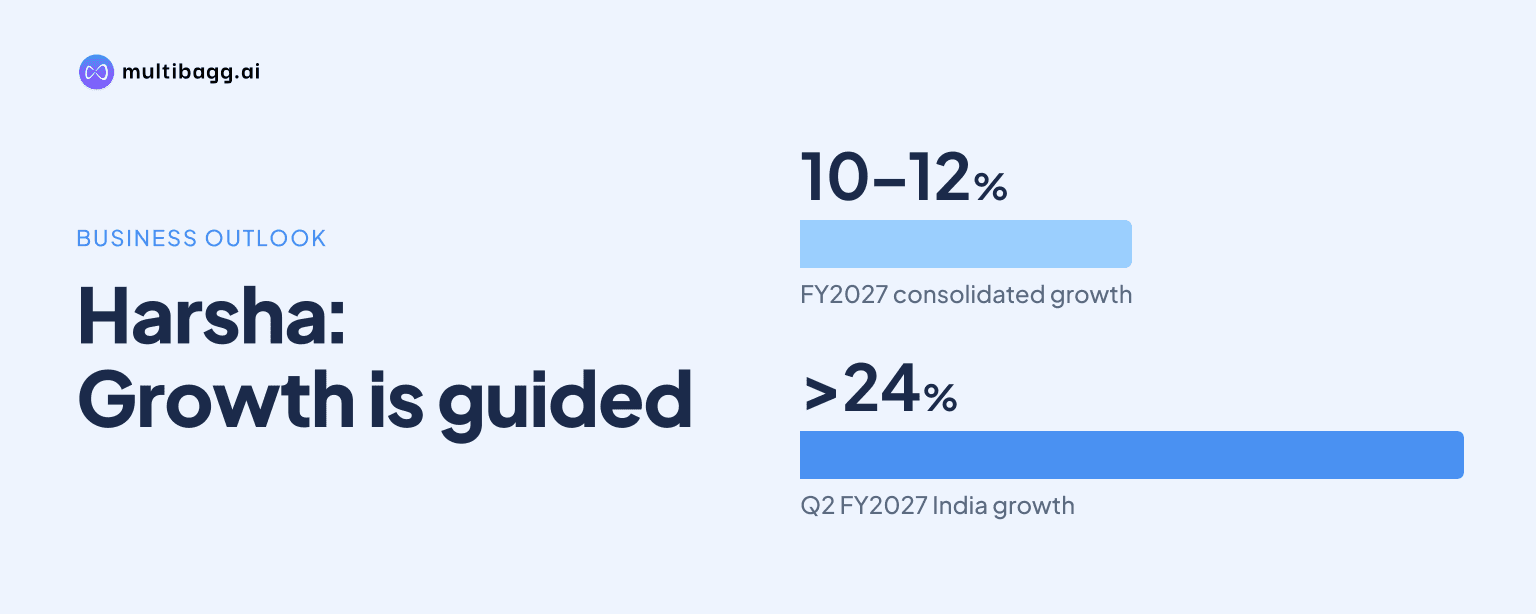
Harsha Engineers International Limited expects FY2027 sales growth in the mid-to-high teens for India Engineering, while the planned downsizing of its Romania facility is expected to limit consolidated growth to 10%-12%. India Engineering grew more than 24% year on year in Q2 FY2027 and 23% in H1 FY2027, supporting the difference in guidance.
Know Harsha Engineers International inside out
Results, valuation, peers and who's buying, in one view.
Why is Harsha's consolidated growth lower than India growth?
Harsha's consolidated guidance is lower because management expects Romania sales to decline as it reduces operations there, even as India Engineering expands at a mid-to-high-teens rate in FY2027. Strategic Advisor Sanjay Majmudar said India would grow at a higher rate, while Romania would be on the negative side, resulting in the 10%-12% consolidated range.
The contrast follows a stronger first half for India Engineering. Management reported Q2 FY2027 top-line growth of more than 24% year on year and H1 growth of 23%, with contributions from Cages, Bushings and Stampings. An analyst noted that H1 consolidated revenue was up about 21% year on year, suggesting the full-year range assumes slower growth in the second half than in the first.
Management cautioned that Q3 is historically softer because many large international buyers have December calendar year-ends and tend to reduce purchases during that period. Chief Executive Officer Vishal Rangwala said the FY2027 guidance should be assessed on a full-year basis rather than extrapolated from the Q2 India Engineering growth rate.
What is Harsha doing at its Romania facility?
Harsha is downsizing the Romania facility and reducing operating costs while continuing to focus on sales of finished Cages from the site. Management's medium-term objective is to arrest operating losses by the end of FY2027, after which it expects lower sales in the following year but a relatively positive contribution to profitability.
The company has not disclosed the reduction in capacity, headcount or any possible one-off costs. When asked on the November 4, 2026 earnings call, management said it was still working on the programme and would announce details at an appropriate time. It said actions would be based on what is required to stop losses, including measures involving customers or the organisation.
Management did not commit that operating improvement would immediately translate into net profitability. Rangwala said it was premature to make that conclusion because net profitability depends on multiple factors, although the company is working on the cost structure and other improvements. The disclosed target is to arrest operating losses by FY2027-end, rather than achieve a stated net-profit target.
Which India Engineering segments support Harsha's outlook?
Harsha's India Engineering outlook is supported by demand across Cages, Bushings and Stampings, with management expecting at least 20% annual growth in large-sized Cages in FY2027. The company expects a significant sales ramp-up in the second half, supported by industrial and automotive demand in India and industrial export demand from Europe, the US, Japan and other markets.
Exports are an important component of that support. H1 India exports were about Rs 280 crore, compared with Rs 480 crore for all of FY2026. Harsha also said Cage sales to a Japan-based customer had started to grow and could deliver annual growth of more than 10%-15%, although management said the initial pace was slow and should build in coming quarters.
In Bushings, Harsha reaffirmed an FY2027 growth expectation of about 30%, aided by demand visibility from windmill gearbox manufacturers and newly developed designs. Management's longer-term target is annual Bushing sales of about Rs 300 crore within three to four years. Q2 Bushing revenue was about Rs 42 crore, up 26% from the previous quarter.
Stampings are also expected to grow more than 30% in FY2027 from FY2026 sales of about Rs 72 crore. Management cited specialised railway seal inserts, air-conditioner compressor components and a newly introduced compressor accumulator product. Q2 Stamping revenue was about Rs 23 crore, up 19% sequentially, while Harsha's four-year annual-sales target for the segment is about Rs 300 crore.
Got a follow-up? Ask IRIS
What projects and markets could affect Harsha's FY2027 delivery?
Harsha expects commercial sales from its previously announced resourcing and outsourcing project to begin gradually in Q3 and Q4 FY2027, with clearer visibility from Q4. At peak, management said the project could reach an annual sales run rate of around Rs 75 crore, making it a potential later-period contributor rather than a fully realised H1 driver.
The company is also developing two further resourcing and outsourcing projects for Europe and North America. The smaller project is at an advanced development stage and could begin commercial sales in FY2027 or FY2028, while the second has only begun initial development and could start in FY2028 or FY2029. These are projects under development, rather than reported revenue commitments.
China remains another variable in the consolidated outcome. Harsha said Q2 FY2027 performance in China was softer sequentially than Q1, although it still grew year on year, and management estimates 5%-7% growth for the current portfolio. Additional growth is expected after new steel Cage capacity for industrial and automotive sectors starts production in Q2 or Q3 FY2028.
How are Harsha's margins, investment and working capital changing?
Harsha reported consolidated Engineering earnings before interest, tax, depreciation and amortisation, or EBITDA, of Rs 81.1 crore in Q2 FY2027, compared with Rs 63 crore a year earlier and Rs 69.8 crore in Q1 FY2027. Management attributed the improved consolidated margin partly to price pass-through for higher brass input costs, including copper and zinc, and partly to a lower Solar contribution to overall revenue.
Management said it expects blended margin to remain above 20% over the longer term, while Majmudar described around 22% as a steadier-state level. This was management commentary rather than formal quarterly guidance. An analyst cited India Engineering EBITDA margin of 23.7% in the quarter, while management said a better product mix had supported recent performance.
Consolidated working capital was around 135 days in Q2 FY2027, down from 139 days in the same quarter a year earlier but up from 116 days in Q1 FY2027. Harsha incurred capital expenditure of Rs 35.6 crore in the quarter. Its Advantek expansion, covering Bushings, Stampings and large-sized Cages, is on track to start production in the next few quarters.
Conclusion
Harsha's FY2027 message is that India Engineering is expected to grow faster than the consolidated result will indicate. Q2 growth of more than 24% and H1 growth of 23% in India Engineering support management's mid-to-high-teens outlook, but the planned contraction in Romania is expected to hold group sales growth to 10%-12%.
The next developments to watch are the Romania actions and whether operating losses are arrested by FY2027-end, as management targets. Other disclosed milestones include potentially softer Q3 demand, the gradual Q3-Q4 FY2027 start of the Rs 75 crore peak-run-rate outsourcing project, and Advantek expansion production beginning in the next few quarters.