










Hy-Tech guarantees 24% H2 EBITDA margin on revised pricing
Key highlights
- Hy-Tech guaranteed a 24% EBITDA margin for H2 FY27, compared with 22.1% in H1 FY27.
- Hy-Tech said all H2 FY27 billing will occur at revised customer prices.
- Q2 FY27 revenue was Rs 60.9 crore, up 41% sequentially, while EBITDA margin rose to 23.8% from 19.6% in Q1.
- Hy-Tech plans to invest Rs 30 crore over 1.5 years and said it could support about Rs 100 crore of turnover.
powered by IRIS
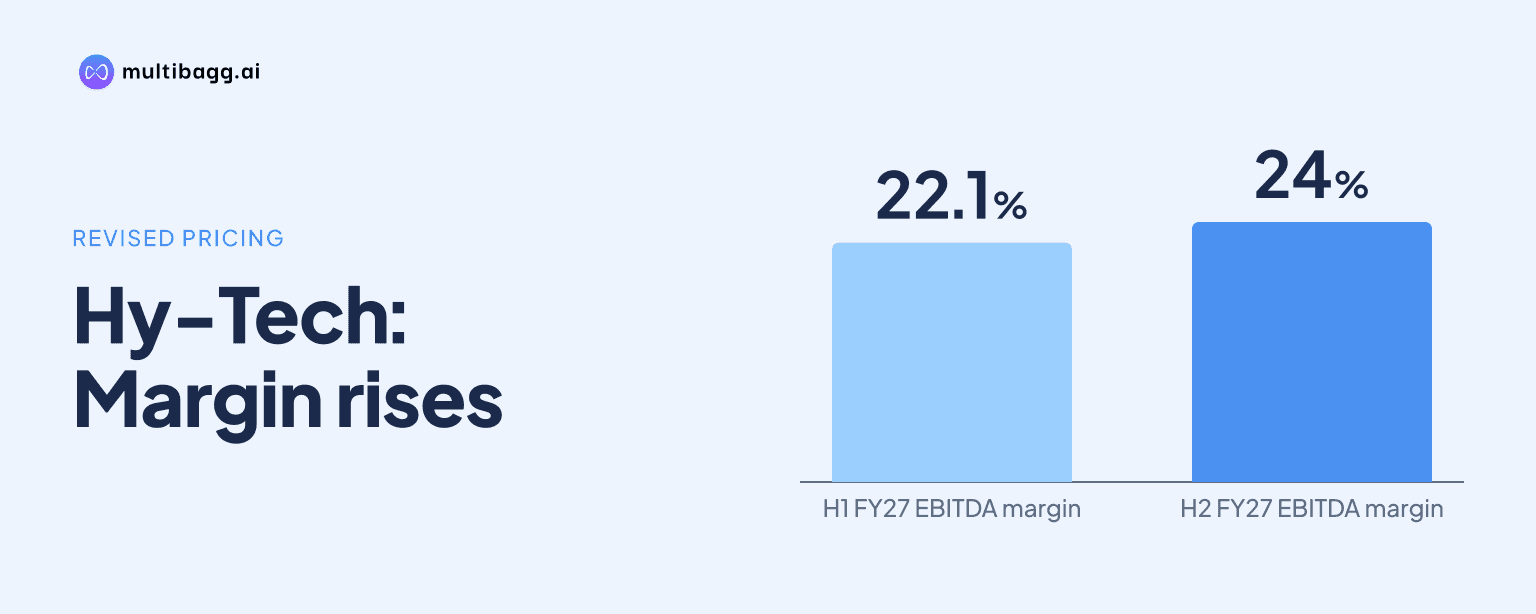
Hy-Tech Engineers Limited said on November 5, 2026 that it guarantees a 24% earnings before interest, tax, depreciation and amortisation (EBITDA) margin in H2 FY27, compared with 22.1% in H1 FY27, because all second-half billing will use revised customer prices and H2 normally contributes 53%-54% of annual turnover.
Know Hy-Tech Engineers inside out
Results, valuation, peers and who's buying, in one view.
Why does Hy-Tech expect a 24% H2 EBITDA margin?
Hy-Tech expects a 24% EBITDA margin in H2 FY27 because revised customer pricing has been finalised and all second-half billing will occur at those prices. Management made the guarantee during its November 5, 2026 earnings call after reporting a 22.1% EBITDA margin for H1 FY27. It said the revisions cover conversion costs as well as raw-material costs.
Management said about 25% of the earlier amount remained to be recovered at the time of the call, but that customer acceptance of all price revisions had been completed. It said the remaining amount would be recovered completely in the next half. The distinction is important: the pricing agreement was complete, while receipt of part of the related money was still pending.
Hy-Tech said raw-material compensation by itself can reduce operating margin, whereas the latest revisions also include conversion-cost increases from original equipment manufacturers, or OEMs. Management said its objective is to maintain EBITDA in a 24%-25% range through operational-efficiency improvements, rather than seek higher prices from customers beyond what it considers reasonable.
How does seasonality support Hy-Tech's H2 outlook?
Hy-Tech said H2 normally represents 53%-54% of annual turnover, compared with 45%-46% in H1, making the second half structurally larger. Management attributed the pattern to lower OEM production schedules in the first half, particularly after customers complete their year-end production activity, followed by peak schedules in the second half.
The FY27 first-half pattern was visible in Q2. Revenue from operations reached Rs 60.9 crore in Q2 FY27, up 41% from Q1, while EBITDA increased 72% sequentially. EBITDA margin rose to 23.8% in Q2 from 19.6% in Q1, a 4.2-percentage-point increase that management attributed to better operating performance, cost absorption and manufacturing efficiency.
The H2 margin commitment therefore combines full revised-price billing with the period that usually produces the larger share of yearly sales. Management did not give separate revenue targets for Q3 FY27 or Q4 FY27, but said H2 turnover should be higher than H1 under its normal seasonal pattern. The 24% margin outcome will consequently be measured on a larger expected sales base than the first six months.
Got a follow-up? Ask IRIS
How did Hy-Tech perform in H1 FY27?
Hy-Tech reported H1 FY27 revenue from operations of Rs 103.9 crore, EBITDA of Rs 22.9 crore and profit after tax, or PAT, of Rs 13.1 crore. Revenue rose 18% from Rs 87.8 crore in H1 FY26, EBITDA increased 14%, and PAT grew 19% from Rs 11 crore. EBITDA margin was 22.1%, while PAT margin remained 12.6%.
Q2 accounted for Rs 60.9 crore of H1 revenue and Rs 14.5 crore of H1 EBITDA. Quarterly revenue increased 22% from Rs 49.8 crore in Q2 FY26, while EBITDA increased 21% from Rs 12 crore. Q2 EBITDA margin of 23.8% was 0.2 percentage points below the 24% recorded in Q2 FY26, despite the sharp improvement from Q1 FY27.
At the bottom line, Q2 FY27 PAT was Rs 8.5 crore, up 23% from Rs 6.9 crore a year earlier. PAT margin rose to 14% from 13.8% in Q2 FY26. The comparison shows that the reported H1 EBITDA margin of 22.1% was below management's 24% H2 commitment, while Q2 had already approached that level at 23.8%.
What capacity and product plans accompany Hy-Tech's margin target?
Hy-Tech said it intends to operate at about 70% capacity utilisation while retaining 20%-30% capacity for new customers. Management said prospective OEM customers ask about free production capacity before placing business, which is why it does not intend to maximise utilisation. It added that spare installed capacity does not necessarily increase operating expenses proportionately.
Management plans to invest Rs 30 crore of initial public offering proceeds over the next 1.5 years and said this spending could support about Rs 100 crore of turnover. It also reiterated a target of Rs 500 crore of turnover within four to five years, with additional machinery installed as needed. This is a management target rather than a FY27 revenue forecast.
The operating plan includes automated machinery, including rotary transfer machines, which management said improve productivity, manufacturing speed and efficiency. Hy-Tech also started exploring stainless-steel double-ferrule fittings about six months before the November 2026 call and expects this expansion to start producing results in FY27-28. Management described hydraulic fittings as its primary growth engine.
Conclusion
Hy-Tech's 24% H2 FY27 EBITDA-margin guarantee depends on two disclosed mechanisms: every second-half invoice being billed at revised prices and H2 typically representing 53%-54% of annual turnover. The commitment is 1.9 percentage points above the 22.1% margin reported for H1 FY27, while Q2's 23.8% margin is the closest reported quarterly reference point.
The next disclosures to watch are the H2 FY27 margin outcome and recovery of the 25% pricing-related amount that remained outstanding on November 5, 2026. Management also plans to deploy Rs 30 crore over 1.5 years, expects double-ferrule fitting results in FY27-28, and targets Rs 500 crore of turnover within four to five years through machinery additions.