










Indian Stock Market Patience Test Eases on 12% Profit Growth
Key highlights
- Nifty 500 companies reported adjusted profit growth of close to 12% in the latest quarter.
- Morgan Stanley projects the Sensex could reach 95,000 by December 2027, with a 1,05,000 bull-case target.
- Foreign portfolio investors withdrew Rs 2.95 lakh crore, or over $33 billion, during the cited calendar year.
- Market consensus expects earnings growth of 11-12% for large caps over the next two years.
powered by IRIS
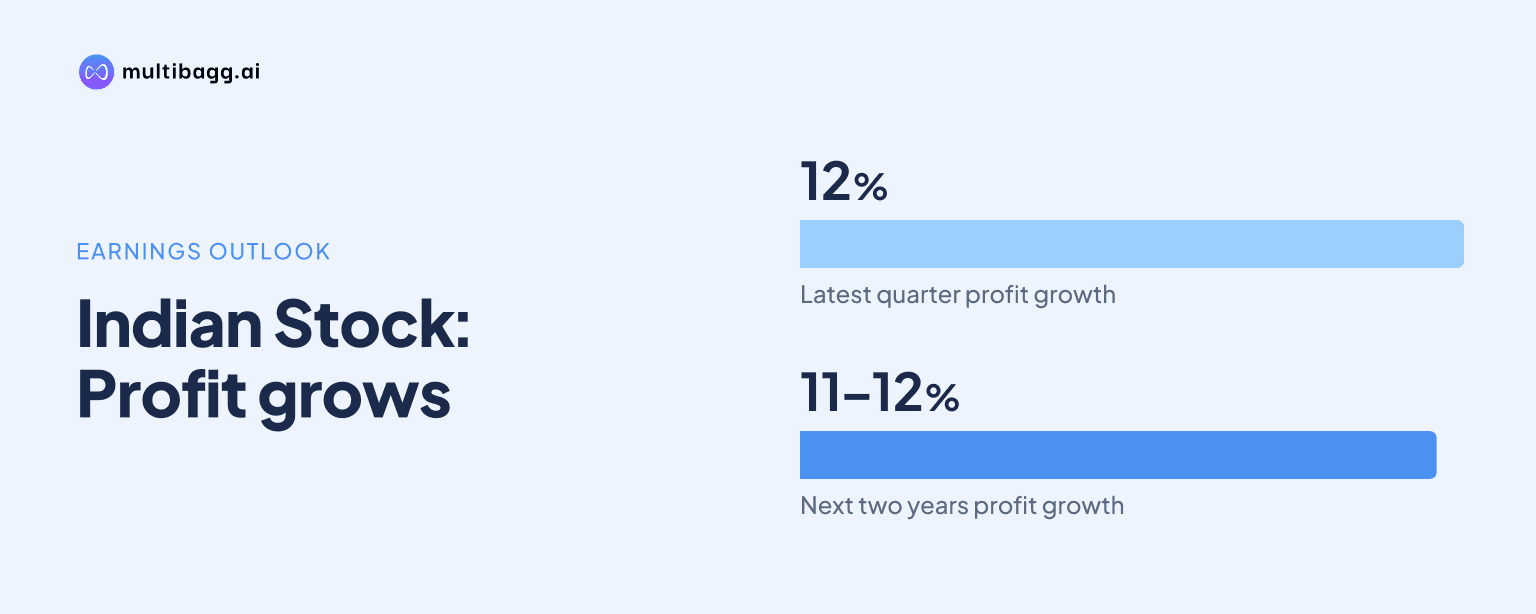
Indian Stock Market investors are seeing early signs of relief after a difficult correction, with Nifty 500 companies reporting adjusted profit growth of close to 12% in the latest quarter, better than the preceding two quarters. The improvement supports a recovery case, but oil, global conditions and valuation expectations still require patience.
Why has the Indian market tested investor patience?
The Indian market has tested investor patience because the decline arrived without a single major domestic crisis and followed a period in which many investors had become used to quick returns. The context describes a five-consecutive-month fall, a stretch said not to have occurred in 29 years, making the drawdown particularly difficult across the market.
Corporate earnings were a central concern during this period. Growth slowed, and the market had to adjust expectations after earlier optimism. One assessment describes the phase from FY24 to FY26 as a consolidation around 8.5%, while another view characterises the market as a "time correction" in which prices consolidate as earnings catch up.
Foreign portfolio selling added to the pressure. Foreign portfolio investors withdrew Rs 2.95 lakh crore, or more than $33 billion, from Indian equities during the calendar year cited in the discussion. That withdrawal raised questions about whether domestic buying could continue to offset overseas selling and whether a rebound could be sustained.
Are earnings showing signs of recovery?
Earnings are showing tentative signs of recovery because the latest Nifty 500 adjusted profit growth of close to 12% was materially better than the previous two quarters. The improvement does not remove uncertainty, but it has been cited as one of several green shoots alongside GST collection trends and proactive RBI management of liquidity and growth conditions.
The outlook remains differentiated across market segments. Market consensus discussed in the context suggests earnings growth of 11-12% for large caps, 14-15% for mid-caps and 18-19% for small caps over the next two years. Motilal Oswal Wealth Management also expects Nifty earnings per share growth of 16% in FY27 and 14% in FY28, compared with 5% in FY26.
These projections are expectations rather than confirmed outcomes. Investors are therefore likely to focus on whether the earnings improvement broadens across sectors and whether margins remain resilient as energy costs work through with a lag.
Got a follow-up? Ask IRIS
Which sectors have better growth visibility?
Discretionary consumption and capital expenditure are the areas identified as having better growth visibility in the current discussion. The case for discretionary consumption is tied to rising disposable income, with India described as a roughly $2,500 per-capita-income economy where incomes are growing close to 10% a year.
The argument is structural rather than a call for immediate returns. Higher disposable income is expected to support discretionary spending over five- and 10-year periods, while portfolio additions should focus on businesses with near-, medium- and long-term growth visibility and good management quality. Capex is also cited as a possible beneficiary of improving conditions.
At the same time, the market debate is not uniformly optimistic. Some commentary warns that valuations imply impatient expectations for a rapid and large follow-through in growth. That creates scope for a near-term reality check even if India retains its longer-term growth potential.
What could determine the next move in the Indian market?
The next move in the Indian market will depend heavily on crude oil, global interest rates, inflation, foreign flows and the durability of domestic earnings. Morgan Stanley cites durable, diversified and decoupled Indian growth, an improving earnings cycle and strong domestic flows as positive drivers, while also flagging elevated oil prices and a global slowdown as risks.
Near-term technical and macro markers are also being watched. A more defensive stance was linked to a sustained Nifty 50 break below the 23,000-23,200 zone or Brent crude returning to $105 a barrel. A more constructive setting was linked to the US 10-year yield holding below 4.8% and Indian inflation peaking, which could allow the RBI to hold rates in December.
Morgan Stanley forecasts the Sensex could reach 95,000 by December 2027, representing a projected 16% rise, with a bull-case target of 1,05,000. Prashant Jain expects the Nifty to compound at 11-12% annually over the longer term, based on real growth of 6-7% and nominal GDP growth of 10-11%. Both views rely on earnings and macro conditions developing as expected.
Conclusion
The Indian market's patience test appears less severe than it did during the correction because earnings have improved, domestic fundamentals remain supportive and sentiment has recovered from a difficult period. However, the evidence points to a recovery that still needs confirmation rather than a settled return to uninterrupted gains.
Investors will next watch whether earnings growth holds, crude oil remains contained and foreign flows stabilise. The key disclosed markers include the 23,000-23,200 Nifty 50 zone, Brent crude at $105 a barrel, the US 10-year yield at 4.8%, inflation trends and the RBI's December rate decision.