










I&PCL H1 profit more than doubles as EBITDA margin reaches 21.6%
Key highlights
- I&PCL reported H1 FY 2026–27 revenue of Rs 111.4 crore, up 26.3% year on year.
- I&PCL’s H1 FY 2026–27 PAT rose 107.2% to Rs 10.8 crore.
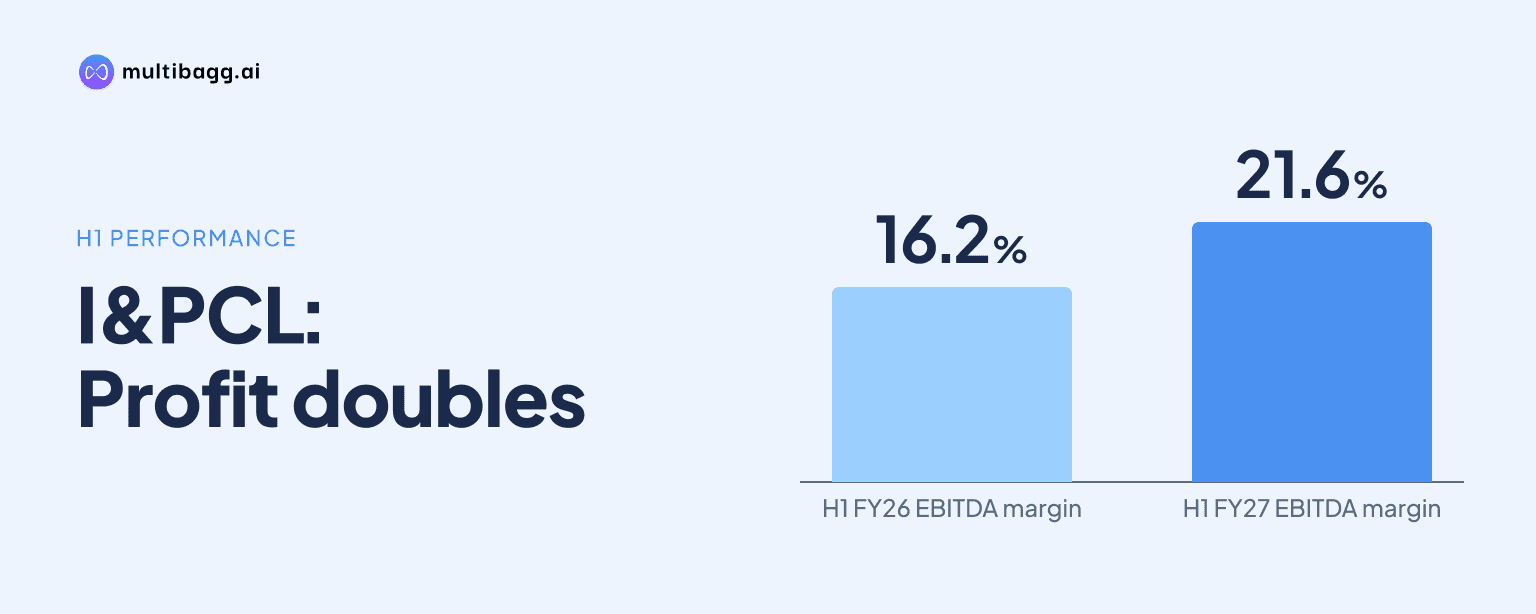
- I&PCL’s EBITDA margin increased to 21.6% in H1 FY 2026–27 from 16.2% a year earlier.
- Aerospace and defence represented 11% of I&PCL revenue in H1 FY 2026–27, versus 6% in FY 2025–26.
powered by IRIS
Investment & Precision Castings Ltd (I&PCL) reported profit after tax of Rs 10.8 crore in the first half (H1) of financial year (FY) 2026–27, up 107.2% year on year, as revenue rose 26.3% to Rs 111.4 crore and EBITDA margin reached 21.6%, from 16.2% a year earlier.
Know Investment & Precision Castings inside out
Results, valuation, peers and who's buying, in one view.
How did I&PCL perform in H1 FY 2026–27?
I&PCL delivered higher revenue, earnings before interest, tax, depreciation and amortisation (EBITDA), and profit in the six months to 30 September 2026. Revenue from operations increased from Rs 88.2 crore in H1 FY 2025–26 to Rs 111.4 crore, while EBITDA rose 67.5% from Rs 14.4 crore to Rs 24.1 crore. Profit after tax (PAT) increased from Rs 5.2 crore to Rs 10.8 crore, meaning H1 PAT was 92% of the Rs 11.8 crore reported for full-year FY 2025–26.
The margin improvement reflected EBITDA growing faster than revenue in the reported half-year. I&PCL’s EBITDA margin expanded by 5.4 percentage points to 21.6% from 16.2% in H1 FY 2025–26. The presentation notes that EBITDA includes other income, and it does not separate the contribution from volume, pricing, product mix, costs or other income to the margin change.
What did I&PCL report for the second quarter?
I&PCL reported Q2 FY 2026–27 revenue of Rs 58 crore, up 8.67% from Rs 53.37 crore in Q1 FY 2026–27 and up 31.55% from Rs 44.09 crore in Q2 FY 2025–26. EBITDA reached Rs 12.91 crore in Q2, increasing 15.17% sequentially and 66.11% year on year. PAT was Rs 5.80 crore, compared with Rs 4.99 crore in the preceding quarter and Rs 3.03 crore in the corresponding prior-year quarter.
The quarterly EBITDA margin reached 22.17% in Q2, above both 20.94% in Q1 and 17.45% in Q2 FY 2025–26. I&PCL’s disclosed annual margin was 12.9% in FY 23, 15.4% in FY 24, 14.0% in FY 25 and 16.7% in FY 26. The company states that the H1 FY 2026–27 figure is for six months and is not comparable with full-year measures.
Got a follow-up? Ask IRIS
How has I&PCL’s revenue mix changed by end market?
I&PCL’s aerospace and defence share rose to 11% of H1 FY 2026–27 revenue from 6% in FY 2025–26, while automotive represented 62% and industrial, energy and general engineering represented 27%. In the prior full year, automotive accounted for 64% and industrial, energy and general engineering accounted for 30%. Aerospace and defence therefore gained 5 percentage points of reported revenue mix, while automotive and industrial each had a lower share.
I&PCL says industrial sales did not fall and that the segment’s lower share resulted because aerospace and defence grew faster. The presentation does not disclose end-market revenue in rupees, so it does not permit calculation of absolute segment growth. The mix shift occurred alongside new programmes for vacuum-melted superalloy aerospace components for HAL and aluminium defence components for MKU, the latter heat treated on I&PCL’s drop-quench line.
I&PCL also added Nadcap accreditation for heat treatment in H1 FY 2026–27, which it describes as another audited special process brought in-house. Its process base includes 38 heat-treatment furnaces, vacuum casting for nickel and cobalt super-alloys, and precision machining capacity. These processes support the company’s stated aim of quoting for higher-value work across aerospace, defence and other end markets.
What is I&PCL spending on capacity and capabilities?
I&PCL spent Rs 5.27 crore on capital expenditure in H1 FY 2026–27, after spending Rs 23.23 crore in full-year FY 2025–26. The company says this investment is funded through internal accruals and debt. Overall gearing was 0.71 times in H1, compared with 0.68 times at 31 March 2026, while interest coverage was 5.12 times, compared with 3.40 times for FY 2025–26.
The stated uses of capital include a lost-foam precision-casting line in installation and trials, more machining capacity to ship additional finished parts from the same castings, and heat treatment, vacuum casting and inspection capability added against confirmed demand. I&PCL’s Board has separately approved capital investment of up to Rs 100 crore for aerospace, defence and energy projects. Management says the programme is intended to strengthen capabilities, expand infrastructure and pursue emerging opportunities, without providing a completion date, revenue target or profit target.
Conclusion
I&PCL’s H1 FY 2026–27 results combined 26.3% revenue growth with a 5.4-percentage-point expansion in EBITDA margin and a 107.2% increase in PAT. Q2 EBITDA margin of 22.17% exceeded Q1’s 20.94%, while aerospace and defence increased from 6% of FY 2025–26 revenue to 11% in H1, changing the disclosed end-market mix.
The next disclosed execution points are management’s second-half plan to move more nominated parts into monthly supply and its focus on new technologies, automation and research and development. Investors can also watch progress on the lost-foam line in trials and the Board-approved investment of up to Rs 100 crore for aerospace, defence and energy projects, for which I&PCL has not disclosed a completion timetable or financial target.