










IRIS RegTech Solutions Limited Reports Over 30% Q2 Revenue Growth
Key highlights
- IRIS RegTech reported revenue growth of over 30% year-on-year in both Q1 and Q2 FY27.
- IRIS CARBON annual recurring revenue increased 52% from March 31, 2026.
- More than 50 clients are using IRIS RegTech's DM platform.
- RegTech revenue of ₹15.8 crore and segment margin of ₹3.55 crore were discussed on the earnings call.
powered by IRIS
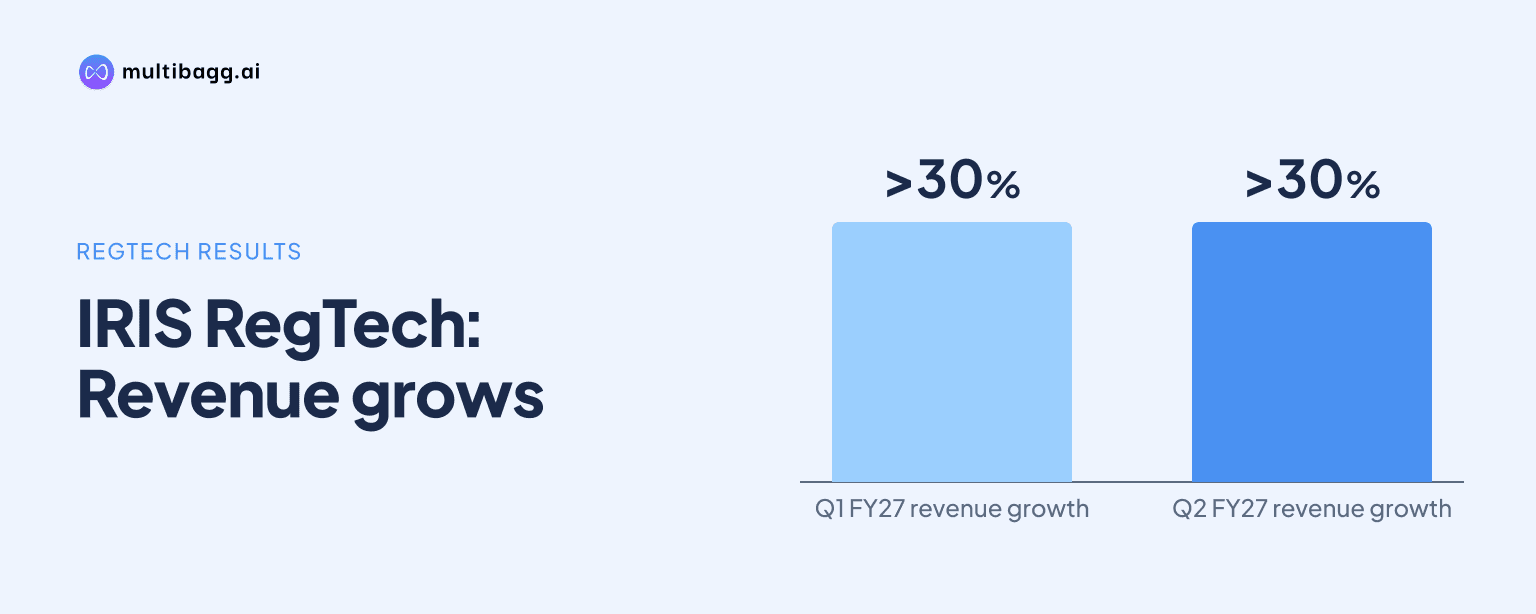
IRIS RegTech Solutions Limited reported revenue growth of over 30% year-on-year in Q2 FY27, extending a similar pace in Q1, while IRIS CARBON annual recurring revenue increased 52% from March 31, 2026. The performance reflected enterprise SaaS traction despite global economic uncertainty and delayed SupTech orders in the Middle East.
Know IRIS Regtech Solutions inside out
Results, valuation, peers and who's buying, in one view.
What did IRIS RegTech report for Q2 FY27?
IRIS RegTech said revenue grew by more than 30% year-on-year in both the first and second quarters of FY27. Management presented the update during its November 6, 2026 earnings call, covering the second quarter and first half of the financial year.
The company attributed the growth momentum primarily to its enterprise SaaS business. Its newer carbon disclosure environment offering, rolled out in the previous financial year, was identified as a major contributor. Management said more than 50 clients are now using its DM platform, with customer feedback being used to improve the product.
Why did enterprise SaaS support IRIS RegTech's growth?
Enterprise SaaS supported IRIS RegTech's performance through higher adoption of its carbon and disclosure-focused offering. The company said the traction was particularly visible in its enterprise SaaS business, where recurring customer subscriptions can provide greater revenue visibility than one-time implementation work.
IRIS CARBON's annual recurring revenue rose 52% from its level on March 31, 2026. Management did not disclose the absolute ARR value in the call excerpt, but the rate of increase indicates that the carbon reporting platform was a meaningful driver of recurring business during the first half of FY27.
The company also said the DM platform had crossed 50 clients. That customer base gives IRIS RegTech direct operating feedback as it develops the offering. However, the call did not provide a client-wise revenue split, contract values, or customer-retention figures.
What factors are affecting IRIS RegTech's near-term outlook?
IRIS RegTech said uncertainty in the Middle East has delayed some SupTech orders, even as its RegTech and enterprise SaaS businesses continued to grow. SupTech refers to technology used by supervisory or regulatory authorities, and order delays can affect the timing of project revenue.
Management also indicated that planned investment in SaaS could limit near-term margin expansion. This points to a balance between funding product development and preserving profitability. The company did not provide a revised margin target or quantify the expected investment during the earnings call material provided.
The wider global economy was described as increasingly uncertain. IRIS RegTech nevertheless said it had maintained growth at a good pace through the first six months of FY27. The contrast between SaaS demand and slower SupTech order conversion is important because the company's growth drivers are not moving at the same speed.
Got a follow-up? Ask IRIS
How does the Q2 FY27 update matter to investors?
The Q2 FY27 update matters because IRIS RegTech has reported over 30% revenue growth in two consecutive quarters, supported by a 52% rise in IRIS CARBON ARR since March 2026. Higher recurring revenue can make the business less dependent on the timing of individual project wins, although the company did not provide its total revenue, total ARR, or EBITDA margin for the quarter in the supplied transcript.
For investors, the key operational markers are the growth in carbon-reporting SaaS, the expansion to more than 50 DM platform clients, and the pace at which delayed SupTech orders are converted. The stated RegTech revenue of ₹15.8 crore and segment margin of ₹3.55 crore provide a view of the segment figures discussed during the call, but no comparable prior-period figures were included in the material.
There was no share-price movement, valuation commentary, or earnings guidance disclosed in the supplied call text. As a result, the available information supports an assessment of operating momentum but does not establish an immediate market impact or a forecast for future profitability.
How does this compare with IRIS RegTech's recent performance?
IRIS RegTech entered FY27 after reporting about 23% total revenue growth and an EBITDA margin of about 14% for FY26, according to its May 2026 earnings call. The reported growth pace of over 30% in each of the first two FY27 quarters is therefore higher than the full-year growth rate cited for FY26.
The change in business mix is also notable. In the earlier period, the company discussed regulatory technology deployments, including a private-cloud use case for PFRDA in India. In FY27, management placed greater emphasis on enterprise SaaS and IRIS CARBON, suggesting that product-led recurring revenue is becoming more prominent in the operating discussion.
Conclusion
IRIS RegTech's Q2 FY27 earnings call showed continued revenue momentum, with growth above 30% year-on-year in Q1 and Q2 and a 52% increase in IRIS CARBON ARR from March 31, 2026. Adoption of the carbon disclosure offering and a DM platform client base of more than 50 supported the update, while delayed Middle East SupTech orders remained a constraint.
Investors should watch the conversion of delayed SupTech opportunities, the effect of planned SaaS investment on margins, and whether IRIS CARBON continues to expand its recurring-revenue base. The company has not disclosed a quantified margin target or detailed FY27 guidance in the supplied earnings-call material.