










Jubilant Line 3 drives 33% CDMO revenue growth during Q2’FY27
Key highlights
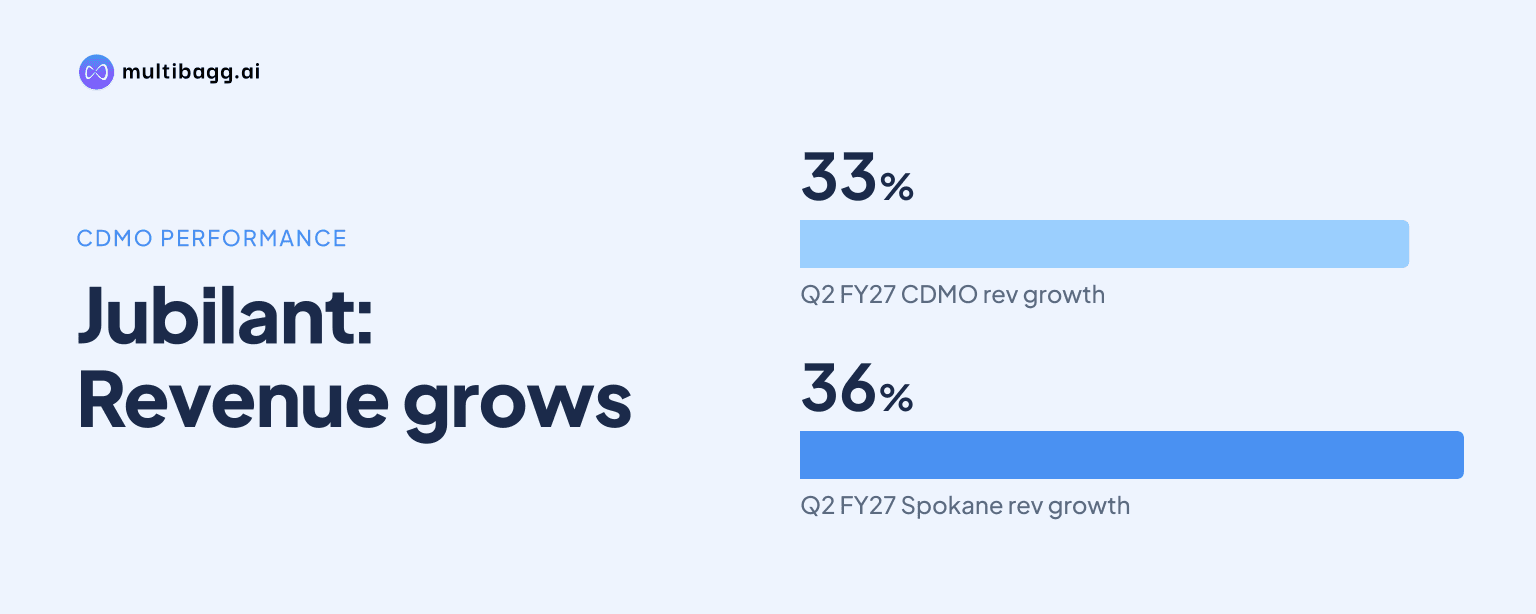
- Jubilant’s CDMO sterile-injectables revenue rose 33% year on year to Rs 522 crore in Q2’FY27.
- Spokane revenue increased 36% year on year to Rs 521 crore in Q2’FY27 as Line 3 scaled up.
- CDMO EBITDA margin fell to 7% in Q2’FY27 from 24% a year earlier, including Montreal remediation costs.
- Jubilant expects Spokane Line 4 technology transfers to start in Q4’FY27 and commercial production in FY28.
powered by IRIS
Jubilant Pharmova’s contract development and manufacturing organisation (CDMO) sterile-injectables revenue rose 33% year on year to Rs 522 crore in the second quarter of fiscal year 2027 (Q2’FY27), driven by incremental revenue from Spokane Line 3, while the company expects Line 4 technology transfers to begin in Q4’FY27 after completing installation and media fills.
Know Jubilant Pharmova inside out
Results, valuation, peers and who's buying, in one view.
How did Jubilant’s Spokane Line 3 affect CDMO sales?
Jubilant’s Spokane Line 3 scale-up was the stated driver of 33% year-on-year growth in total CDMO sterile-injectables revenue in Q2’FY27. Revenue reached Rs 522 crore, up from Rs 393 crore in Q2’FY26 and Rs 496 crore in Q1’FY27. For H1’FY27, total revenue increased 33% to Rs 1,019 crore from Rs 763 crore in H1’FY26.
Spokane revenue rose 36% year on year to Rs 521 crore in Q2’FY27 from Rs 384 crore in Q2’FY26, while H1’FY27 revenue rose 39% to Rs 1,015 crore from Rs 730 crore. Jubilant said Line 3 was scaling faster than the industry benchmark. Spokane generated Rs 521 crore of the segment’s Rs 522 crore Q2’FY27 revenue and Rs 1,015 crore of its Rs 1,019 crore H1’FY27 revenue.
Why did Jubilant’s CDMO margins fall despite revenue growth?
Jubilant’s CDMO sterile-injectables earnings before interest, tax, depreciation and amortisation (EBITDA) fell 61% year on year to Rs 37 crore in Q2’FY27 even as revenue increased by Rs 129 crore. The segment’s EBITDA margin declined to 7% from 24% in Q2’FY26, a reduction of 1,690 basis points. In H1’FY27, EBITDA fell 48% to Rs 81 crore and the margin fell to 8% from 20%.
Jubilant attributed the total segment’s lower year-on-year margin to higher operating expenses, including incremental remediation costs at its Montreal operation. Spokane reported Q2’FY27 EBITDA of Rs 121 crore, 2% below Rs 124 crore in Q2’FY26, while its margin declined to 23% from 32%. Management said the earlier margin was abnormally higher because Line 3 incurred lower costs for only one month; Spokane’s H1’FY27 EBITDA nevertheless increased 18% to Rs 238 crore from Rs 202 crore.
When will Jubilant’s Spokane Line 4 begin commercial production?
Jubilant expects technology transfers for Spokane Line 4 to start in Q4’FY27, with commercial production shown in its timeline for FY28. The company says installation and media fills are complete and that it is building an order-book pipeline for the line. The project is intended to double Spokane capacity.
Jubilant expects Line 4 to reach full utilisation in three and a half years and has disclosed peak revenue potential of USD 80 million to USD 90 million. Its timetable identifies FY26 as the installation phase, FY27 as the media-fill phase and FY28 as the commercial-production phase. These are management plans and potential estimates rather than reported Line 4 revenue, because technology transfers have not yet begun.
Got a follow-up? Ask IRIS
How is Jubilant changing its sterile-injectables product mix?
Jubilant is positioning Lines 3 and 4 as a shift from a traditional, volume-driven sterile-injectables CDMO model towards complex biologics formulations. Its traditional mix is about 80% small molecules and 20% biologics with lower formulation complexity, whereas the projected Line 3 and Line 4 mix is 20% small molecules and 80% biologics. The company has onboarded one of the world’s largest oncology products on Line 3 without naming the product.
Jubilant says the newer lines require specialised filling, tighter aseptic processing windows and more stringent environmental controls. It expects a higher technology-transfer revenue model because such programmes are harder and longer to qualify before commercialisation. Its stated customer base includes five of the top 20 pharmaceutical companies, more than 25 customers worldwide, repeat business above 90%, and an average relationship exceeding five years with its top 10 customers.
What market conditions support Jubilant’s Spokane capacity plan?
Jubilant cites a widening supply-demand gap in sterile-injectable vial filling as support for additional Spokane capacity. It projects demand of 6.8 billion vials in 2027 against supply of 6.1 billion, implying a 700 million-vial gap; in 2023, supply of 5.5 billion vials exceeded demand of 4.9 billion. The company also presents the global CDMO sterile-injectables market as growing from USD 13 billion in 2023 to USD 20 billion in 2027, at a stated compound annual growth rate of about 11%.
Jubilant identifies potential United States manufacturing shifts by innovator pharmaceutical companies, supply consolidation, biologics pipelines and loss of exclusivity as market drivers. It also points to customer switching timelines of about 24 months, typical commercial contracts lasting three years or more with automatic renewal, and more than 10 years of United States Food and Drug Administration-compliant status at Spokane. Management presents these factors as barriers that can make sterile-injectables capacity additions and customer changes lengthy.
Conclusion
Jubilant’s Q2’FY27 sales growth shows Spokane Line 3 contributing material revenue, with total CDMO sterile-injectables sales up 33% and Spokane sales up 36% year on year. The revenue increase has not yet translated into segment profitability: total EBITDA margin was 7%, affected by Montreal remediation costs, while Spokane’s 23% margin was below the unusually elevated prior-year comparison.
The next disclosed milestones are Line 4 technology transfers in Q4’FY27 and planned commercial production in FY28, followed by management’s three-and-a-half-year full-utilisation timetable. Montreal remediation remains in progress, with lean operations planned through FY28 until Line 5 is expected to become operational in FY29; Jubilant’s FY30 target is CDMO revenue of more than twice FY24 and an EBITDA margin above 25%.