










Jubilant Pharmova says Montreal costs reached Rs 357 crore
Key highlights
- Jubilant Pharmova put cumulative Montreal losses at about Rs 357 crore through H1 FY2027.
- Montreal generated a loss of more than Rs 80 crore in Q2 FY2027, including remediation and operating costs.
- Jubilant Pharmova expects H2 FY2027 Montreal burn to be lower than the about Rs 157 crore recorded in H1.
- Jubilant Pharmova expects H2 FY2027 average EBITDA margins in the mid-teens.
powered by IRIS
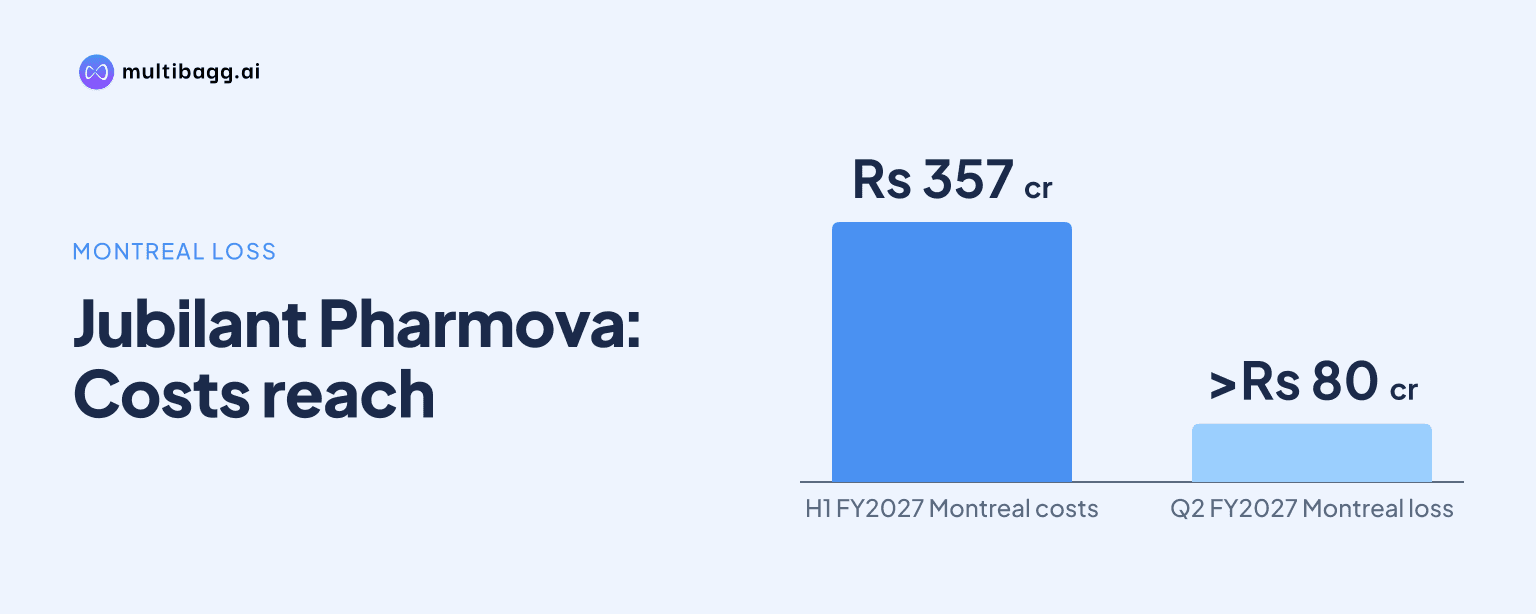
Jubilant Pharmova Limited said Montreal had generated about Rs 357 crore of cumulative losses through H1 FY2027, including about Rs 157 crore in the half year, while management expects its SPECT radiopharma supplies to stabilise in H2 FY2027 and help reduce the site’s cost burden.
Know Jubilant Pharmova inside out
Results, valuation, peers and who's buying, in one view.
How much has Jubilant Pharmova lost at Montreal?
Jubilant Pharmova has incurred about Rs 357 crore of losses at Montreal to date, based on management’s estimate of about Rs 157 crore in H1 FY2027 and roughly Rs 200 crore before that period. Chief Financial Officer Ashish Mukkirwar described this as the loss incurred at the facility so far, where remediation activity followed a warning letter.
The H1 FY2027 loss reflected absent third-party revenue at Montreal, operating expenditure and remediation spending. In Q2 FY2027 alone, Jubilant Pharmova said the Montreal loss was more than Rs 80 crore, comprising remediation costs and operating expenses. Management did not provide a numerical split between remediation, external oversight and under-absorption costs.
The scale of the loss coincided with a period of consolidated growth. Jubilant Pharmova reported H1 FY2027 revenue of Rs 4,599 crore, up 19% year on year, with earnings before interest, tax, depreciation and amortisation, or EBITDA, of Rs 523 crore. Management said Montreal costs and unavailable high-margin SPECT products contributed to a year-on-year EBITDA-margin decline despite growth across businesses.
Why did Montreal reduce Jubilant Pharmova’s margins?
Montreal reduced Jubilant Pharmova’s margins because high-margin single-photon emission computed tomography, or SPECT, radiopharma products were unavailable while the facility continued to carry operating and remediation costs. Management also cited negligible third-party revenue at the site as a factor affecting Q2 and H1 FY2027 profitability.
In Q2 FY2027, Jubilant Pharmova recorded revenue of Rs 2,370 crore, up 21% year on year, EBITDA of Rs 255 crore and profit after tax of Rs 31 crore. Management said the EBITDA margin nevertheless declined year on year, principally because the company lost the contribution from SPECT products and incurred incremental Montreal costs.
An analyst said Radiopharma margins had declined to 32% from 40% over the preceding four quarters. Management said the rising mix of Ruby-Fill, whose margins are currently lower than the overall Radiopharma business, was one factor, alongside the lack of SPECT supply from Montreal. Jubilant Pharmova does not disclose product-level margins and did not quantify the separate effects.
Ruby-Fill continued to expand while SPECT was constrained. Management cited an established expectation of roughly 35% year-on-year Ruby-Fill growth and said its Q2 FY2027 annualised growth rate was 30%. The company has announced new capacity for Ruby-Fill, but management’s near-term case for Radiopharma margin recovery rests mainly on restoring SPECT output.
When does Jubilant Pharmova expect Montreal costs to decline?
Jubilant Pharmova expects its H2 FY2027 Montreal burn to be lower than the loss incurred in H1 FY2027, although management did not give quarterly guidance or a precise end date for the remediation programme. Mukkirwar said normalising production should allow the company to reduce remediation expenditure and pursue cost optimisation in FY2028.
Radiopharma Chief Executive Officer Harsher Singh said the initial response after a warning letter involved costs intended to maintain the ability to manufacture at the site. He said the company had passed the initial 90-day response threshold and expected remediation spending to decrease substantially quarter on quarter, by more than low-double digits, without providing a specific run rate.
The expected reduction has two stated mechanisms. SPECT production returning would absorb a portion of Montreal’s fixed costs through additional revenue, while remediation expenses should decline as the site moves to what Singh described as a steadier state. Management did not say remediation was complete or rule out further operational challenges.
Got a follow-up? Ask IRIS
Will SPECT supplies improve Jubilant Pharmova’s H2 margins?
Jubilant Pharmova expects SPECT supplies from Montreal to stabilise in H2 FY2027, particularly in Q4, supporting both Radiopharma revenue and margins. Management expects H2 FY2027 average EBITDA margins in the mid-teens and a quarter-on-quarter margin improvement across the half year.
Management said normalised SPECT supplies should help Radiopharma move towards its earlier 40% margin level. That statement was a directional expectation rather than a segment-margin target or timetable. The 32% margin level raised by the analyst, compared with 40% over the previous four quarters, shows the reported change during the supply disruption.
Generics launches planned in Q3 and Q4 FY2027 are another part of the H2 margin plan. Management also expects higher production volumes to improve gross margins in most businesses, while higher output at the Spokane plant is expected to aid Allergy Immunotherapy margins and continued new-line activity is expected to support Sterile Injectables revenue.
What could shape Jubilant Pharmova’s recovery after H2 FY2027?
Jubilant Pharmova’s recovery after H2 FY2027 depends on sustained SPECT output, lower Montreal remediation expenditure and commercial progress in other operations. Management expects EBITDA margins and cash flow to improve from FY2028 as new radiopharma products, positron emission tomography, or PET, pharmacies, and Sterile Injectables Lines 3 and 4 begin contributing commercially.
At Spokane Line 3, management said Q2 FY2027 revenue was about Rs 168 crore, based on the stated US dollar revenue figure, from more than 13 technology-transfer projects and more than five customers. Management expects FY2028 to contain both technology-transfer and commercial revenue, with gradual margin improvement, and said a more significant margin improvement should occur in FY2029 as commercial production becomes more substantial.
Jubilant Pharmova expects capital expenditure of about Rs 1,800 crore to Rs 1,900 crore in FY2027, falling to around Rs 1,000 crore in FY2028. Management linked lower capital expenditure, PET pharmacy operations and commercialisation at Lines 3 and 4 to its vision of reaching net debt of zero by the end of FY2030, which remains a management objective rather than a reported outcome.
Conclusion
Montreal has created a quantified financial drag for Jubilant Pharmova, with cumulative losses of about Rs 357 crore through H1 FY2027 and more than Rs 80 crore recorded in Q2 alone. The site’s operating and remediation costs compounded the loss of higher-margin SPECT product sales, helping explain why EBITDA margins declined even as Q2 revenue rose 21% year on year.
The next disclosed milestone is SPECT supply stabilisation, particularly in Q4 FY2027, which management expects to lower H2 Montreal burn below the about Rs 157 crore recorded in H1. Management’s H2 mid-teen EBITDA-margin expectation also depends on Generics launches, higher production volumes and the planned reduction in remediation spending.