










Jubilant Pharmova Limited retains generics doubling plan
Key highlights
- Jubilant Pharmova retained its plan to double generics revenue and reach 15% to 17% EBITDA margin.
- Jubilant Pharmova has secured 13 ANDA approvals since April 2024.
- Jubilant Pharmova continues to target six to eight generics product launches each year.
- Jubilant Pharmova expects generics growth and margin improvement in the second half of the current year.
powered by IRIS
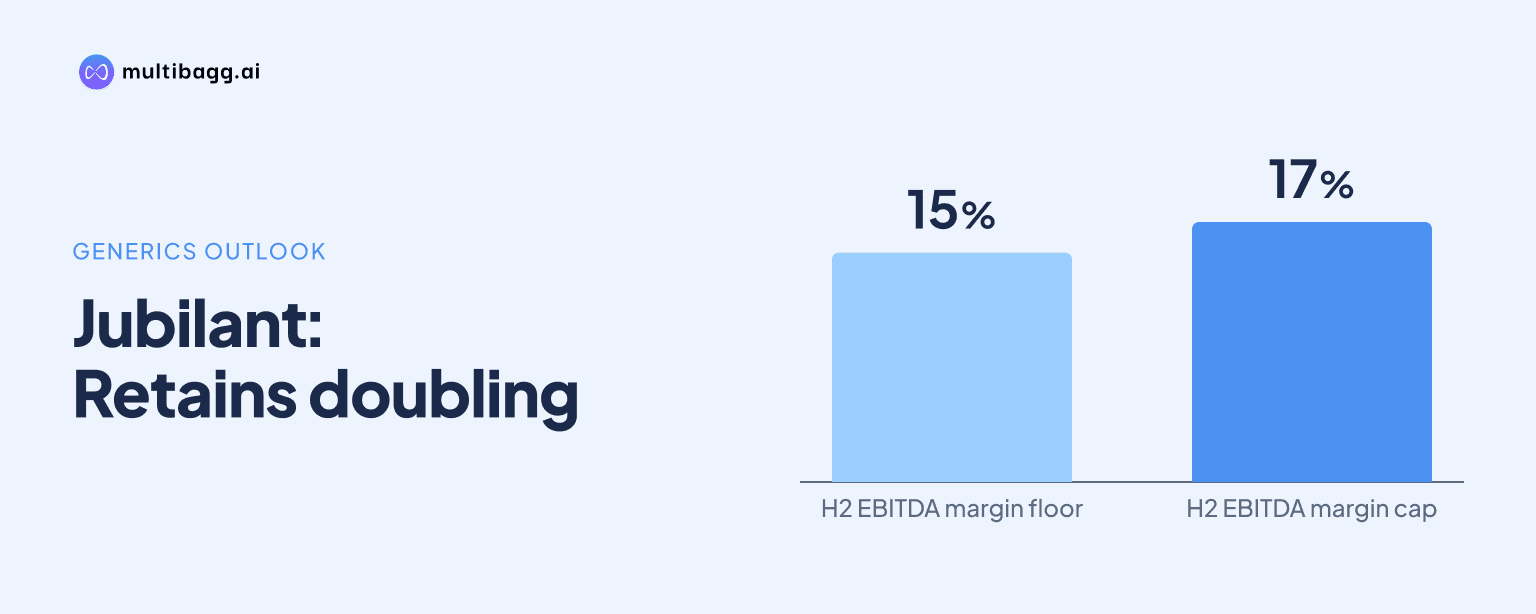
On its November 16, 2026 earnings call, Jubilant Pharmova Limited retained its plan to double generics revenue, citing 13 approvals for Abbreviated New Drug Applications (ANDAs) since April 2024 and six to eight annual launches. Jubilant Pharmova also reaffirmed a 15% to 17% earnings before interest, tax, depreciation and amortisation (EBITDA) margin target for the business.
Know Jubilant Pharmova inside out
Results, valuation, peers and who's buying, in one view.
What is Jubilant Pharmova's generics revenue and margin target?
Jubilant Pharmova continues to target a doubling of generics revenue and EBITDA margin of 15% to 17%. Management said on November 16, 2026 that it stood by the framework presented at its February 2025 investor meeting. The call did not disclose the revenue base to be doubled, a date for achieving the target, or a revised margin range.
The company did not adopt a higher 25% to 30% EBITDA margin scenario suggested by an analyst at a hypothetical Rs 1,000 crore revenue scale. Instead, management repeated the 15% to 17% target and said the trailing 12 months and the last full year were moving in that direction. This separates the company’s stated objective from the analyst’s hypothetical outcome.
Management also said it expected growth and margin improvement in the second half of the current year. It did not quantify either measure for that period, but identified new-product launches and market-share retention or gains in existing products as the mechanisms behind the expected improvement.
What is driving Jubilant Pharmova's generics growth?
Jubilant Pharmova said generics growth is coming from both new launches and share performance in existing products. Management said launches add new revenue, while maintaining or gaining share in selected products provides another source of growth. That means the strategy is not dependent only on the 13 ANDA approvals accumulated since April 2024.
The 13 approvals were secured after the April 2024 closure of the previous United States Food and Drug Administration inspection classified as Voluntary Action Indicated. Jubilant Pharmova said it is monetising these approved ANDAs through market launches. The transcript does not identify the products, launch dates, market sizes or revenue contribution of the approved portfolio.
Product selection is focused on lower-competition opportunities rather than exclusively on products conventionally labelled complex generics. Management said some moderately difficult-to-manufacture products can have limited competition because manufacturers have historically not focused on them. The company’s stated screening criterion is therefore competitive intensity, not solely formulation complexity.
How will Jubilant Pharmova sustain six to eight launches a year?
Jubilant Pharmova maintained guidance to launch six to eight products each year through a mix of approved filings, in-licensing and manufacturing transfers. The 13 ANDA approvals since April 2024 provide one available pool for launches, while partnerships provide additional products. Management did not disclose how many future launches will arise from each route.
Some in-licensed products are received as fully packed products and launched through Jubilant Pharmova’s commercial front ends. Management said this model is used across global markets, not only in the United States. It allows the company to commercialise a product without necessarily first transferring manufacturing to one of its own sites.
Other products involve site transfers, with some manufacturing assigned to sites other than Roorkee. Management said this is intended to avoid placing all transferred products at a single location and to provide a degree of operational de-risking. It gave no count of transfers, recipient sites or products already commercialised through this route.
Got a follow-up? Ask IRIS
Is Jubilant Pharmova reducing generics development spending?
Jubilant Pharmova did not say that research and development spending was minimal or that it had stopped developing products. In response to an analyst’s question on whether the company was only monetising old filings, management said it was both launching approved ANDAs and in-licensing products through partnerships. The call did not quantify generics research and development expenditure.
The operating model differs by product route. Fully packed in-licensed products use the commercial front end, while transferred products require manufacturing at a selected site other than, in some cases, Roorkee. The company did not disclose whether these routes carry different margins, transfer costs or launch timelines.
Management’s 15% to 17% EBITDA margin objective remains the relevant disclosed profitability benchmark. Although the analyst proposed a 25% to 30% margin at Rs 1,000 crore of revenue, Jubilant Pharmova gave no basis to raise its stated target. Its evidence was limited to movement toward the range over the last 12 months and the last full year.
What execution evidence and uncertainties remain for Jubilant Pharmova?
The clearest execution evidence is the 13 ANDA approvals since April 2024 and the continuing guidance for six to eight annual launches. Compared with the accumulated approvals over more than two years, the annual launch number is a forward operating target rather than a record of products already sold. The call does not show how many of the 13 approvals have become commercial launches.
Management’s expectation of second-half growth and margin improvement is also forward-looking. It rests on product launches and market-share performance, but the company did not provide revenue guidance, a current generics EBITDA margin, or launch-level profitability. Those omissions leave the speed of progress toward doubled revenue and the 15% to 17% range unresolved.
Manufacturing diversification provides a disclosed risk-management mechanism, but not a quantified financial forecast. Jubilant Pharmova said it is using sites beyond Roorkee for some transfers, yet it did not say whether transfers were complete or when products from those sites would generate revenue. The commercial output of in-licensed packed products was similarly not quantified.
Conclusion
Jubilant Pharmova’s generics strategy combines 13 ANDA approvals since April 2024, six to eight annual launches, share gains or retention in existing products, in-licensing and manufacturing-site diversification. Management retained both its revenue-doubling objective and its 15% to 17% EBITDA margin framework, rather than endorsing the higher margin case raised by an analyst.
The next disclosed milestone is management’s expectation of growth and margin improvement in the second half of the current year. Readers should watch for evidence that approved ANDAs, fully packed in-licensed products and transfers to sites beyond Roorkee are converting into launches, as well as any updated disclosure on progress toward the February 2025 revenue and margin targets.