










KKC targets Rs 1,500 crore revenue and 800 EBOs by FY28
Key highlights
- KKC targets Rs 1,500 crore revenue in FY28, compared with Rs 1,002 crore in FY25.
- KKC aims for 800 EBOs by FY28, up from 609 EBOs in FY25.
- KKC reported FY26 revenue growth above 20% year on year versus an approximate 15% CAGR path.
- KKC reported EBITDA margin above 19% in FY26 and a net addition of 57 EBOs.
powered by IRIS
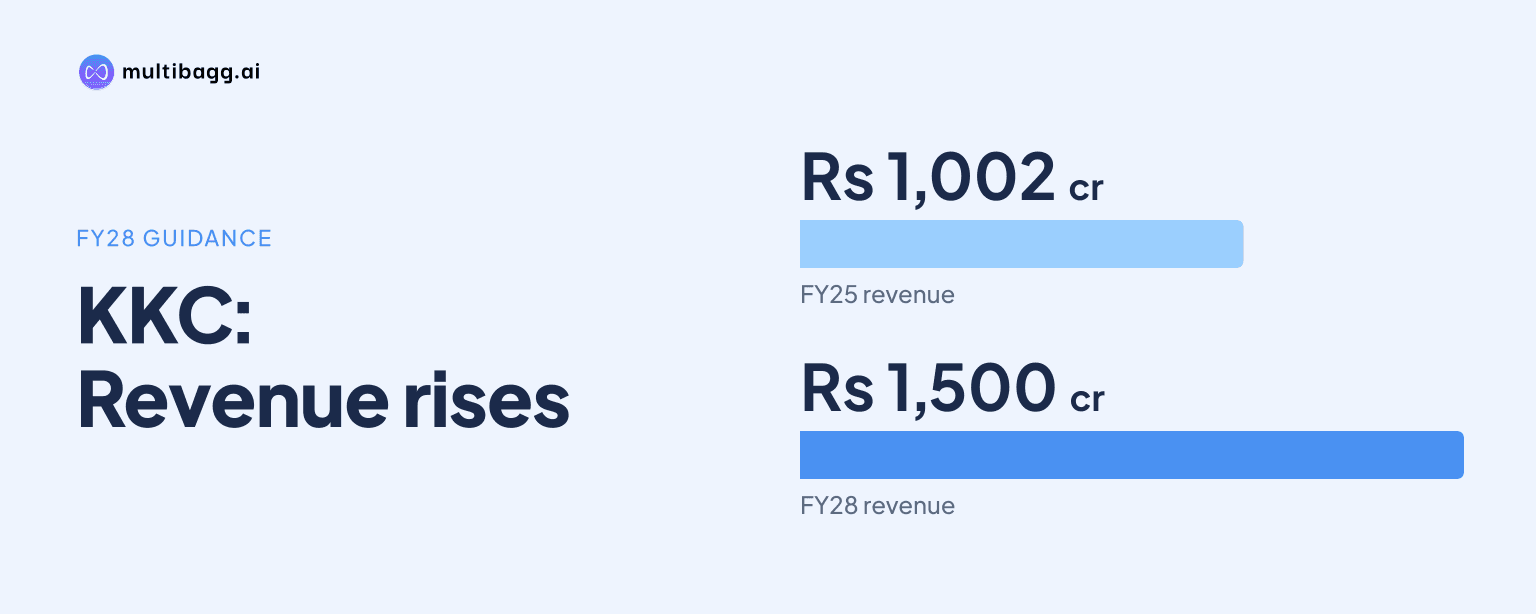
Kewal Kiran Clothing Limited targets Rs 1,500 crore of revenue and 800 exclusive brand outlets (EBOs) by FY28, compared with Rs 1,002 crore and 609 EBOs in FY25. KKC also states a 17%-18% operating-margin range, with the plan supported by store expansion, brand pivots and new category work.
Know Kewal Kiran Clothing inside out
Results, valuation, peers and who's buying, in one view.
What are KKC's FY28 revenue, margin and outlet targets?
KKC's stated FY28 objectives are Rs 1,500 crore in revenue, 800 EBOs and a 17%-18% healthy operating margin. Against the FY25 base of Rs 1,002 crore revenue and 609 EBOs, the targets imply Rs 498 crore of additional revenue and 191 more outlets over the Vision 2028 period.
KKC describes the revenue path under Vision 2028 as requiring an approximate 15% compound annual growth rate (CAGR). Its FY26 progress report says revenue growth exceeded 20% year on year, which management presents as ahead of the approximate 15% CAGR trajectory, although the slides do not disclose an absolute FY26 revenue figure.
How does KKC plan to expand to 800 EBOs?
KKC plans to build its outlet network through separate brand programmes, rather than through a single format. Its channel strategy identifies 600 or more EBOs for Killer X, 125 or more for Lawman and 75 or more for Kraus, alongside wider large-format-store (LFS) counter space for Killer X and focused e-commerce for Lawman.
For Integriti, KKC specifies deeper modern-trade penetration and expansion in tier-2 and tier-3 cities without providing an EBO target. Junior Killer X is to grow through traditional multi-brand outlets (MBOs), shop-in-shop (SIS) placements in MBOs and LFS formats, while easies is positioned around an “honest first and right price” proposition.
KKC says it added a net 57 EBOs in FY26 across Killer, Lawman and Kraus. Its September 2026 outlet table lists 477 Killer outlets, 80 K-Lounge outlets, 80 Lawman plus Integriti outlets and 37 Kraus outlets, for a displayed total of 674 outlets.
The September 2026 total is 65 higher than the FY25 total of 609 EBOs, while KKC separately reports a net FY26 addition of 57 outlets. The presentation labels these disclosures with different periods and does not reconcile the eight-outlet difference between the displayed totals and the reported net addition.
Got a follow-up? Ask IRIS
Which brands and categories support KKC's FY28 strategy?
KKC identifies Lawman, Kraus and Junior Killer X as growth levers alongside Killer X, Integriti and easies. Lawman has initiated a direct-to-consumer (D2C) pivot through EBO launches, and the 2026 milestone in KKC's growth history records its move to a D2C brand; the channel plan calls for 125 or more Lawman EBOs and focused e-commerce.
Kraus is being developed as a women's denim and casualwear brand after KKC acquired a 50% interest in Kraus Jeans in 2024. The FY26 update says Kraus is undertaking a gradual EBO rollout, has activated an export channel and is intended to scale through SIS formats in MBOs, with a plan for 75 or more EBOs.
Junior Killer X is KKC's boys' kidswear brand, and the company says distribution and product-range expansion are generating high-growth momentum. KKC's category map shows a presence in menswear, womenswear and boys' denim and casualwear, while identifying girls' denim and casualwear as a vacuum and marking women's semi-formalwear and menswear formals as pivot areas.
KKC has also begun selective ethnicwear entry to address an adjacent consumption occasion and initiated a footwear foray. The FY26 update says footwear work includes design, sourcing and go-to-market preparation, but the supplied slides provide no revenue target, outlet target or launch date for either ethnicwear or footwear.
What has KKC reported on FY26 execution?
KKC reports FY26 revenue growth of more than 20% year on year, compared with the approximate 15% CAGR associated with its Vision 2028 revenue target. It also reports an earnings before interest, tax, depreciation and amortisation (EBITDA) margin above 19% in FY26, attributing the result to operating leverage and disciplined cost management despite raw-material volatility.
The reported FY26 EBITDA margin is above the 17%-18% operating-margin range displayed for FY28, but the presentation uses different margin measures. KKC does not provide the exact FY26 EBITDA margin, an absolute FY26 revenue number, or a reconciliation between EBITDA margin and operating margin in the supplied material.
The FY26 channel update also says KKC will continue to explore export opportunities for brands including Killer and Kraus. That export activity is described as exploratory, whereas the presentation's explicit numerical Vision 2028 commitments are Rs 1,500 crore of revenue and 800 EBOs.
Conclusion
KKC's Vision 2028 combines a Rs 498 crore revenue increase from its FY25 base with 191 additional EBOs by FY28. The strategy allocates channel roles across Killer X, Lawman, Integriti, Kraus, easies and Junior Killer X, while ethnicwear and footwear remain early-stage category initiatives. Revenue growth above 20% and EBITDA margin above 19% are the FY26 progress measures disclosed by management.
The next disclosed milestones are progress toward 800 EBOs, including Lawman's 125-plus and Kraus's 75-plus EBO plans. Management's continued footwear go-to-market work, selective ethnicwear entry, Kraus export activation and future reporting on the approximate 15% revenue CAGR path will indicate how the FY28 programme is developing.