










KP Green Engineering targets FY27 Rs 1,800 crore, PAT at 5%-7%
Key highlights
- KP Green Engineering reported H1 FY27 total income of Rs 682 crore, up 27% from Rs 536 crore in H1 FY26.
- Management targets FY27 turnover of Rs 1,700 crore to Rs 1,800 crore and indicated H2 revenue of about Rs 1,000 crore to Rs 1,200 crore.
- KP Green Engineering guides PAT margin at 5% to 7% for the next two quarters amid zinc, gas and other input-cost uncertainty.
- KP Green Engineering ended September 2026 with an order book of Rs 1,892 crore and galvanising utilisation above 50%.
powered by IRIS
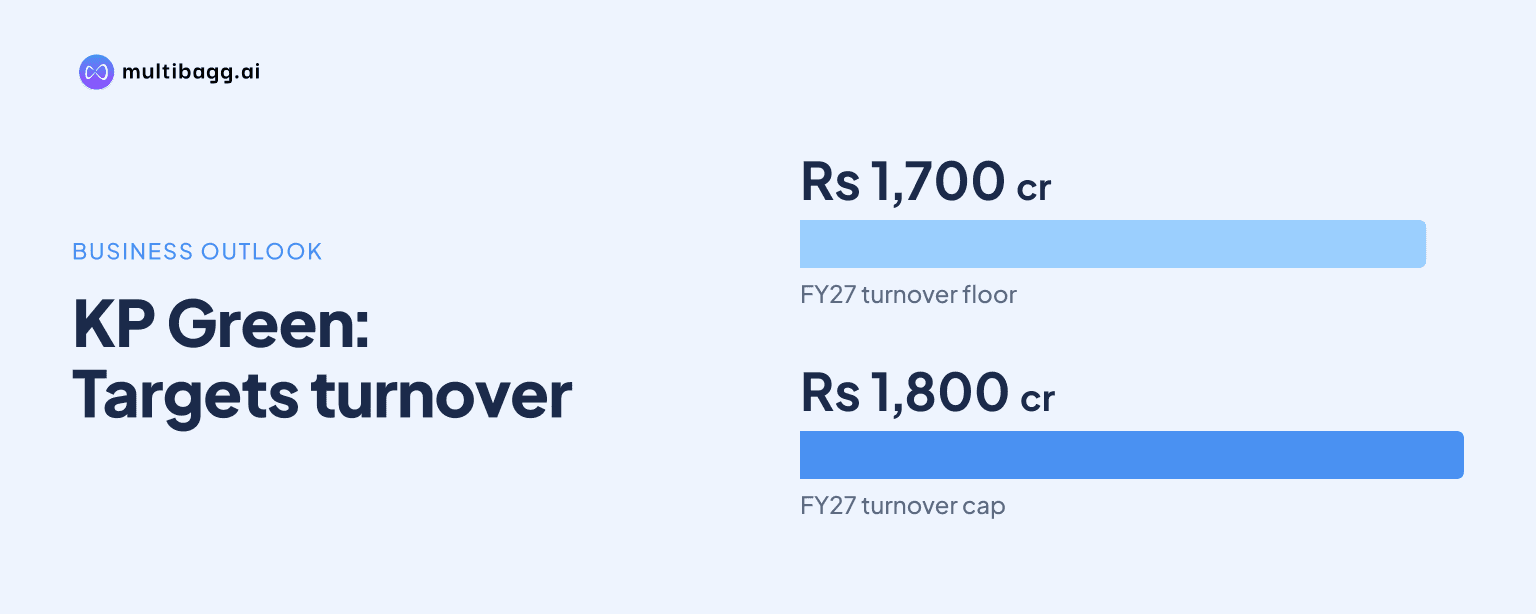
KP Green Engineering Limited is targeting FY27 turnover of Rs 1,700 crore to Rs 1,800 crore after reporting Rs 682 crore of total income in H1 FY27 ended September 30, 2026, while management guides profit after tax margin at 5% to 7% because zinc, gas and other input costs remain uncertain.
Know KP Green Engineering inside out
Results, valuation, peers and who's buying, in one view.
What is KP Green Engineering's FY27 turnover target?
KP Green Engineering is targeting FY27 turnover of Rs 1,700 crore to Rs 1,800 crore, which requires a substantially larger second half than the Rs 682 crore of total income reported in H1 FY27. Management confirmed that H2 FY27 revenue could be about Rs 1,000 crore to Rs 1,200 crore when an investor asked whether that range followed from the full-year target.
Total income rose 27% from Rs 536 crore in H1 FY26 to Rs 682 crore in H1 FY27, while revenue from operations was Rs 679 crore in the latest half. Earnings before interest, tax, depreciation and amortisation, or EBITDA, increased 17% to Rs 119 crore from Rs 102 crore, with an EBITDA margin of about 17.4%. Income therefore grew faster than EBITDA during the period.
Management also referred to a 25% compound annual growth rate, or CAGR, aspiration for the next five years under the KP 3.0 plan, covering group companies including KP Green Engineering. It said more granular FY28 guidance would probably be provided in Q4, leaving the Rs 1,700 crore to Rs 1,800 crore FY27 range as the specific turnover outlook disclosed on the call.
Why is KP Green Engineering guiding PAT margin at 5% to 7%?
KP Green Engineering is guiding PAT margin of 5% to 7% for the next two quarters because management said it cannot predict zinc, gas and other raw-material prices. H1 FY27 profit before tax was Rs 50 crore and PAT was about Rs 32 crore. Management said higher depreciation and interest costs affected PAT after the capacity build-out.
Management said geopolitical developments had raised zinc and gas costs in the past six months, including the latest quarter. Its galvanising operations receive price-variation benefits through the IEEMA equation, according to management, allowing recovery of a large portion of the movement. Yet management said the cost increase was not fully offset and did not forecast lower raw-material costs in H2 FY27.
An analyst noted that interest plus depreciation was almost Rs 65 crore in H1 FY27 and asked whether stable charges could lift H2 profitability as turnover grows. Management said depreciation should be mostly similar in H2 and acknowledged that unchanged depreciation and interest could improve PAT. It nevertheless retained the 5% to 7% PAT-margin range while input-cost volatility remains unresolved.
How will capacity utilisation support KP Green Engineering's H2 plan?
KP Green Engineering expects overall manufacturing capacity utilisation to reach about 70% next year, from about 40% to 50% at the time of the H1 FY27 call. The company has manufacturing capacity of about 4 lakh tonnes and said its rapid capacity expansion over the past three years needs time to be filled with orders and operated efficiently.
The galvanising plant's utilisation has risen above 50%, compared with an earlier 35% to 40% range, management said. It expects utilisation at that facility to reach about 70% by the end of FY27. The plant has 90,000 tonnes per annum of galvanising capacity and a 15-tonne single-dip kettle, and management expects higher utilisation to add value to its products.
Management described H1 FY27 as seasonally slower, noting that the second quarter is typically affected by rain as well as the period's geopolitical conditions. It expects higher growth in H2 but did not provide a separate percentage growth forecast. Management linked future PAT normalisation to increased use of installed capacity, which it said should reduce the relative burden of depreciation and interest.
Got a follow-up? Ask IRIS
Does KP Green Engineering have enough orders for its target?
KP Green Engineering closed September 2026 with an order book of Rs 1,892 crore, which management described as roughly nine to 10 months of revenue at the current run rate. It announced about Rs 770 crore of new orders during the period, including about Rs 240 crore in July, Rs 258 crore in August and Rs 270 crore in October.
The order book provides execution visibility rather than immediate revenue because current orders generally take 12 to 15 months to execute, management said. The company aims to retain 12 to 15 months of orders in hand. Management also said it had executed about Rs 600 crore to Rs 700 crore during the year while adding about Rs 800 crore of orders.
A disclosed Rs 819 crore Bharat Sanchar Nigam Limited, or BSNL, contract covers supply and erection at about 1,280 sites under the BSNL 4G saturation project. Related-party orders from the KP Group accounted for about 17% of H1 sales, compared with 50% last year. Management attributed the lower proportion to higher capacity and larger external orders, rather than a slowdown in KP Group business.
What funding and cash-flow factors are relevant to KP Green Engineering?
KP Green Engineering said its working-capital cycle had stretched because of higher capital expenditure, turnover and sales. Management cited retention payments and later customer receipts as reasons receivables may increase. It expects operating cash flow to become positive from the next H1, probably after March, while seeking to reduce the working-capital cycle.
At September 2026, net worth stood at Rs 491 crore, compared with Rs 382 crore a year earlier, while fixed assets rose to Rs 695 crore from Rs 330 crore. Total debt increased to Rs 447 crore from Rs 196 crore, and the debt-to-equity ratio moved to 0.91 times from 0.5 times. These balance-sheet movements accompanied the company's manufacturing-capacity investment.
Management expects about Rs 300 crore of capital expenditure over the next 18 months but did not specify the H2 FY27 allocation. It said expansion would need both debt and equity. The promoter has committed about Rs 100 crore, including Rs 25 crore after completion of the process in 30 to 60 days and a further Rs 75 crore within about 18 months; land has already been acquired for planned tubular-tower capacity.
Conclusion
KP Green Engineering's FY27 outlook rests on delivering a stronger H2 from its Rs 1,892 crore September order book and increasing utilisation at recently added facilities. The company is targeting Rs 1,700 crore to Rs 1,800 crore of turnover, but management's 5% to 7% PAT-margin guidance shows that sales growth is not expected to translate automatically into higher net profitability while zinc, gas, depreciation and interest costs remain material factors.
The next measures to watch are H2 execution, galvanising utilisation moving toward management's 70% FY27-end target, and the expected Q4 FY28 guidance. Management's expectation of positive operating cash flow from the next H1, alongside the planned Rs 300 crore of capital expenditure over 18 months and promoter funding of Rs 100 crore, will also determine how working capital and financing needs develop.