










Mahanadi Coalfields IPO Opens at ₹129-₹136 Amid Demand Watch
Key highlights
- Mahanadi Coalfields will open its ₹8,981.12 crore IPO for subscription on November 19, 2026.
- The ₹129-₹136 price band requires a minimum retail investment of ₹14,960 for 110 shares.
- The issue is a 100% offer for sale of 66.18 crore shares, representing a 10% stake.
- Mahanadi Coalfields reported FY2026 EBITDA margin of 47.45% and PAT margin of 31.56%.
powered by IRIS
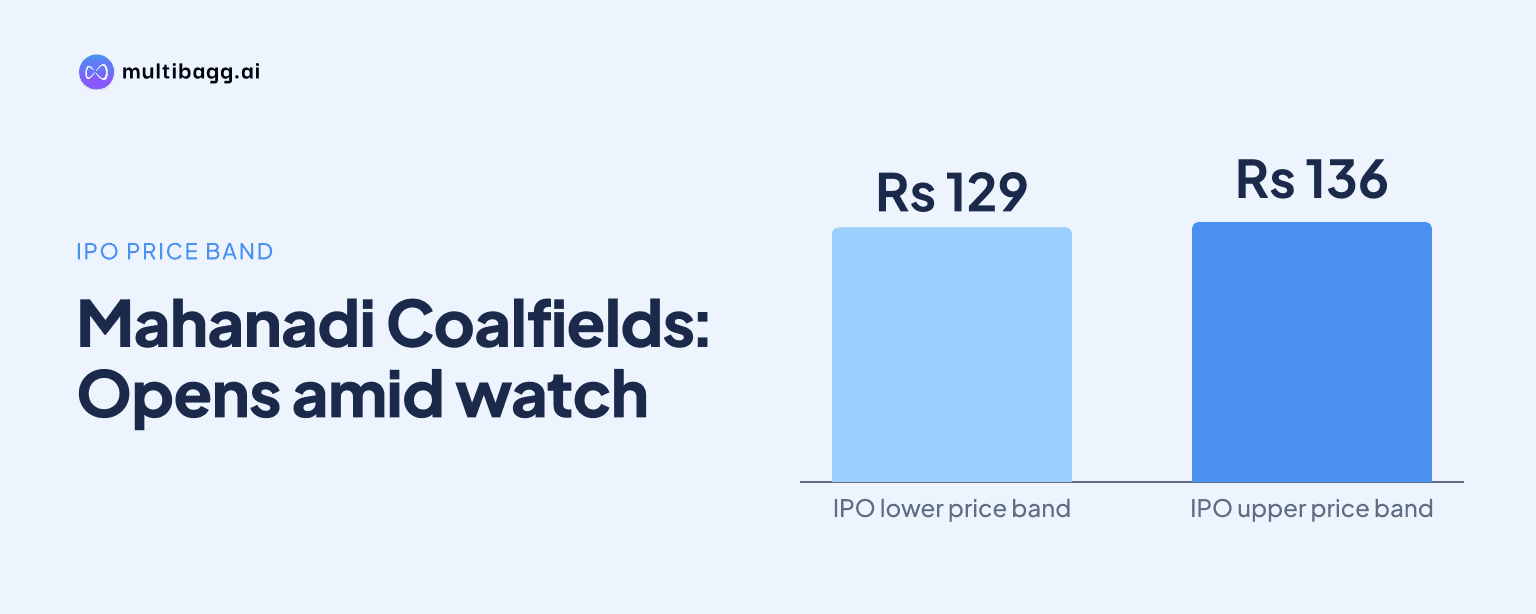
Mahanadi Coalfields Limited will open its ₹8,981.12 crore initial public offering on November 19, 2026, at a price band of ₹129 to ₹136 per share, while subscription data is not yet available and will be central to judging near-term demand.
When does the Mahanadi Coalfields IPO open and close?
Mahanadi Coalfields will accept IPO bids from November 19 through November 23, 2026, with the anchor investor portion scheduled to open on November 18. The issue is proposed to list on both BSE and NSE, subject to the final allotment and listing process.
The basis of allotment is expected on November 25, followed by refunds and credit of shares to demat accounts on November 26. The tentative listing date is November 27. Retail applicants can bid for a minimum lot of 110 shares, requiring an investment of ₹14,960 at the upper end of the price band, and in multiples of that lot thereafter.
Is the Mahanadi Coalfields IPO a fresh issue?
No, Mahanadi Coalfields is a fully offer-for-sale issue in which promoter Coal India Limited will sell up to 66,18,36,300 equity shares. The company will not receive any of the IPO proceeds because no new shares are being issued.
The offer represents a 10% stake in Mahanadi Coalfields. If fully completed, Coal India’s holding would decline from 100% to 90%, while the total outstanding share count of the company would remain unchanged. The proceeds, after applicable expenses, will go to Coal India rather than being used for mine development, expansion or other company funding needs.
This structure matters for investors assessing the transaction. The offer provides a public-market entry point and changes the ownership mix, but it does not itself add growth capital to Mahanadi Coalfields. Public shareholders will also have limited influence over key decisions because Coal India and the Government of India are expected to retain a 90% ownership position after the offer.
Got a follow-up? Ask IRIS
What supports the Mahanadi Coalfields investment case?
Mahanadi Coalfields has a large coal resource base, low-cost mechanised mines and established supply links to India’s power sector, which underpin the long-term case while thermal coal demand remains firm. The company is described as the country’s largest coal producer by output and operates in Odisha.
Its reported profitability is a notable feature of the offer discussion. EBITDA margin was 47.45% in FY2026 and PAT margin was 31.56%, while EBITDA margin remained above 46% in each of the previous three financial years. At the upper price band, the valuation has been cited at about ₹90,009.74 crore, and one analysis estimated a price-to-earnings multiple of around 8.4 times based on FY2026 earnings of about ₹16.16 per share.
Reserve life is another point being discussed. At the FY2026 production run-rate, the draft prospectus estimates that reserves could support roughly 45 years of production. Efficient low-cost production and integrated evacuation infrastructure may remain relevant strengths, but these factors need to be assessed alongside the company’s dependence on thermal power customers and the policy environment.
What could affect Mahanadi Coalfields subscription and listing demand?
Mahanadi Coalfields subscription demand will depend on category-wise participation, especially qualified institutional buyer interest, as well as broader market conditions during the November 19-23 bidding window. Of the issue, 50% is reserved for qualified institutional buyers, 15% for non-institutional investors and 35% for retail investors.
No official subscription figures are available before the issue opens, so conclusions on oversubscription or listing demand would be premature. A grey market premium of ₹3.5 per share was cited on November 17, equal to roughly 3% of the ₹136 upper price band, but this is an unofficial market indicator and cannot establish a listing outcome.
Investors are also weighing business risks. Operations are concentrated in two Odisha coalfields and in non-coking coal, while revenue is substantially tied to power-sector customers. Thermal power demand, timely collections from government customers, dispatch volumes, regulated pricing and the expansion of renewable power are among the operating variables that can influence sentiment.
Conclusion
Mahanadi Coalfields enters the market with a ₹129-₹136 price band, a ₹8,981.12 crore offer-for-sale structure and reported FY2026 EBITDA margin of 47.45%. Its resource base, mechanised operations and power-sector supply relationships support the operating case, while geographic concentration, customer dependence, limited pricing flexibility and a decline in PAT from ₹11,842 crore in FY2024 to ₹10,698 crore in FY2026 require attention.
The next checkpoints are the November 18 anchor book, daily category-wise subscription figures during November 19-23 and the expected November 25 allotment. Investors tracking the longer-term case will also watch dispatch volumes, payment collections from power utilities and whether coal demand remains resilient as renewable capacity expands.