










Marksans Pharma Q2 revenue hits Rs 940 crore, margin 22.8%
Key highlights
- Marksans Pharma reported record Q2 FY27 revenue of Rs 940 crore, up 30.5% year on year.
- Q2 FY27 EBITDA rose 48.3% to Rs 214 crore and EBITDA margin expanded to 22.8%.
- U.K. and Europe revenue grew 65% to approximately Rs 405 crore, while Australia and New Zealand revenue rose 64% to approximately Rs 101 crore.
- H1 FY27 operating cash flow was Rs 322 crore, and September-end net cash was Rs 1,095 crore.
powered by IRIS
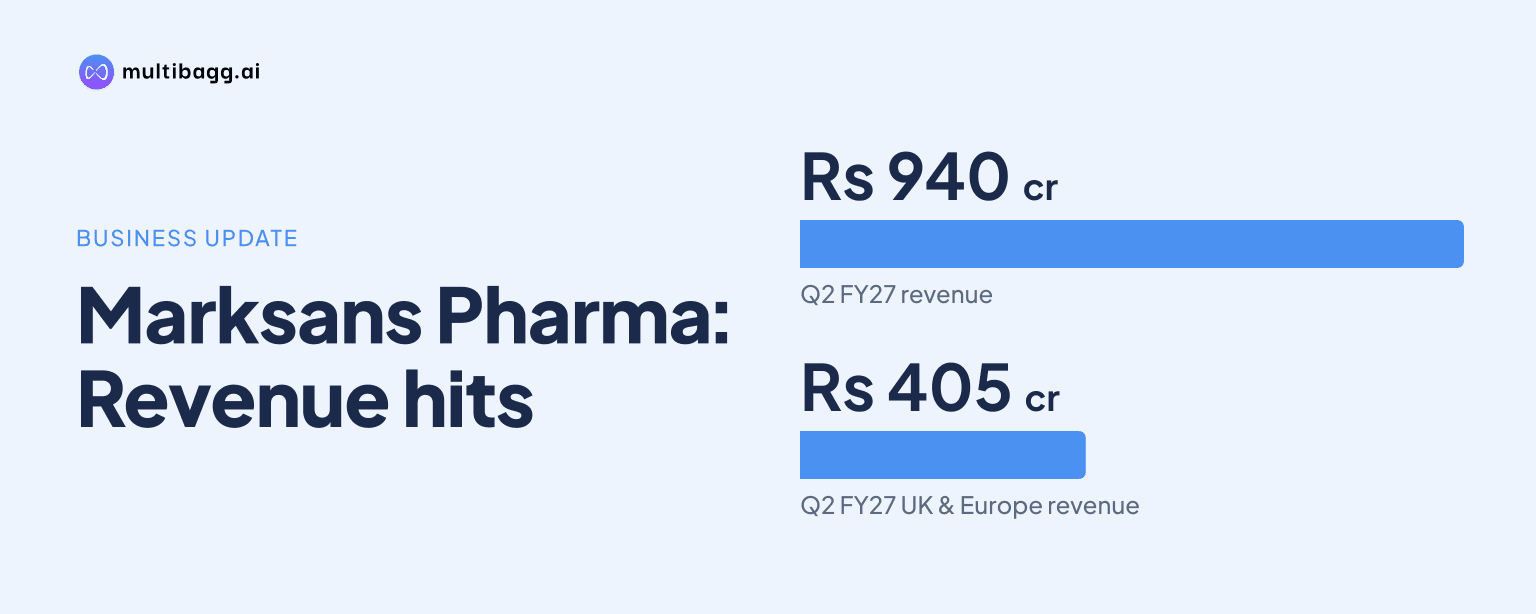
Marksans Pharma Limited reported record Q2 FY27 revenue from operations of Rs 940 crore, up 30.5% year on year, while earnings before interest, tax, depreciation and amortisation, or EBITDA, rose 48.3% to Rs 214 crore and margin expanded to 22.8%. The result was led by U.K. and Europe, Australia and New Zealand, alongside continued North American growth.
Know Marksans Pharma inside out
Results, valuation, peers and who's buying, in one view.
What drove Marksans Pharma's record Q2 FY27 revenue?
Marksans Pharma's Rs 940 crore Q2 FY27 revenue was driven by growth across its major markets rather than one geography or acquisition. Revenue rose 11.8% sequentially, while total income increased 29.2% year on year to Rs 958 crore. Management said the underlying business grew approximately 25% even excluding QliniQ, its Netherlands business.
U.K. and Europe was the fastest large regional contributor, with revenue increasing 65% year on year to approximately Rs 405 crore in Q2 FY27. Management said the region's business still grew 49% excluding acquisitions, following portfolio strengthening, new-product preparation and market-position work during the relatively subdued FY26 U.K. period.
North America remained Marksans Pharma's largest market at Rs 421 crore, or 44.8% of revenue, and grew 8.7% year on year to its highest quarterly level. Australia and New Zealand grew faster, rising 64% to approximately Rs 101 crore, which management attributed to traction in the branded prescription, or Rx, business under Nova. Rest of World shipments were affected by geopolitical disruption in the Middle East and other regions.
How did Marksans Pharma's profitability change in Q2 FY27?
Marksans Pharma's Q2 FY27 EBITDA grew faster than revenue, increasing 48.3% year on year to Rs 214 crore as EBITDA margin widened 274 basis points to 22.8%. A basis point is one-hundredth of a percentage point. The reported margin was above management's stated 20%-21% guidance range, while profit before tax rose 45.1% to Rs 194 crore.
Gross profit increased 33.6% year on year to Rs 550 crore, ahead of the 30.5% rise in revenue, and gross margin improved 135 basis points to 58.5%. However, gross margin was below Q1 FY27's 59.1% because the first quarter had benefited from consumption of lower-cost inventory, while inventory costs increased in the second quarter.
Freight costs nearly doubled in the current environment and accounted for about Rs 20 crore of the sequential increase in other expenses, according to management. Employee costs also increased by about Rs 8 crore as Marksans Pharma added staff and invested in newer markets, while the German business incurred initial startup costs as it prepared for its next phase.
Why did Marksans Pharma's Q2 profit after tax fall sequentially?
Marksans Pharma's Q2 FY27 profit after tax was Rs 144 crore, up 44.8% year on year but below Rs 159 crore in Q1 FY27. Net margin was 15% in the quarter. Management attributed the sequential decline to higher depreciation and amortisation, lower other income and a higher effective tax rate of 25.8%.
The depreciation and amortisation increase followed the start of amortisation on acquisition-related intangible assets. Management also said currency movements had stabilised, reducing other income relative to Q1 FY27. These factors affected profit after tax even as Q2 EBITDA reached a record Rs 214 crore and revenue rose 11.8% sequentially.
For H1 FY27, the comparison was more favourable: revenue from operations grew 32.9% to Rs 1,781 crore, EBITDA increased 74.7% to Rs 427 crore and profit after tax rose 92.5% to Rs 303 crore. H1 EBITDA margin expanded 574 basis points to 24%, while net margin reached 16.6%; management said the half year also benefited from higher other income.
Got a follow-up? Ask IRIS
What does Marksans Pharma's cash position show?
Marksans Pharma generated Rs 322 crore of operating cash flow in H1 FY27, compared with Rs 75 crore in the corresponding prior-year period. Cash conversion, calculated as operating cash flow as a percentage of EBITDA, improved to 75.2% from 30.7%, while capital expenditure of Rs 46 crore left free cash flow of Rs 275 crore.
The working-capital cycle reduced to about 128 days in H1 FY27 from 138 days in FY26. Marksans Pharma deployed about Rs 95 crore on acquisitions and paid around Rs 41 crore in dividends during the half year, yet its net cash position increased by Rs 135 crore.
At the end of September, cash balance and current investments stood at Rs 1,124 crore, with net cash at Rs 1,095 crore and net worth at Rs 3,367 crore. On a trailing 12-month basis, return on capital employed increased to 24.7% from 18.7%, and return on equity rose to 18.6% from 13.6%. Research and development expenditure was 2.6% of H1 FY27 revenue.
What are Marksans Pharma's stated growth plans?
Marksans Pharma said it plans to deepen its existing-market presence, scale the European platform, expand its portfolio and selectively enter markets with suitable opportunities. In Europe, QliniQ contributed approximately Rs 84 crore in H1 FY27, while ABCnow and Marksans GmbH were described as building blocks for the German platform and a broader regional portfolio.
Management said North America's order book remained healthy and that prescription-product price erosion was in single digits. It also cited seasonality in a portfolio tilted toward the October-to-December cold season. Management said it remained optimistic about its U.S. order-book objective over the next three years, though this is a management objective rather than a reported outcome.
Conclusion
Marksans Pharma combined 30.5% Q2 FY27 revenue growth with 48.3% EBITDA growth, led by approximately Rs 405 crore of U.K. and Europe revenue and approximately Rs 101 crore from Australia and New Zealand. The quarter also showed the effect of the broader geographic mix: gross profit grew 33.6% despite higher inventory and freight costs, although profit after tax fell sequentially from Rs 159 crore to Rs 144 crore.
The next areas to watch are management's execution toward its stated Rs 5,000 crore revenue objective within three years, the potential expansion of manufacturing infrastructure, and the recovery of delayed Rest of World shipments. Marksans Pharma said it is in active discussions on adding a manufacturing block or acquiring another plant, supported by Rs 1,095 crore of net cash at September-end.